Free tools Windows power users keep installed
One-click scans. No signup required.
For eligible business driving, compare the standard mileage allowance for each trip’s date with the business-use share of your allowable vehicle costs. Neither method always produces the larger deduction. The right choice depends on your business miles, vehicle costs, business-use percentage, recordkeeping, and—especially—the method you used when the vehicle first became available for business use.
For federal tax purposes in 2026, the business mileage rate is 72.5 cents per mile for trips from January 1 through June 30, then 76 cents per mile for trips from July 1 through December 31. Apply the rate by trip date; using one rate for all 2026 miles will give the wrong result. These are U.S. federal IRS rates, not a statement about state tax treatment.

As an Amazon Associate I earn from qualifying purchases.
How the two deduction methods work
The standard mileage method converts eligible business miles into an allowance using the IRS rate for the date of travel. The actual-expense method totals allowable vehicle costs and deducts only the share attributable to business use. For a mixed-use vehicle, the common allocation is business miles divided by total miles for the period.
| Method | Basic calculation | What it covers |
|---|---|---|
| Standard mileage | Eligible business miles multiplied by the applicable IRS business rate for each trip date | The rate accounts for vehicle operating costs and depreciation. Do not also deduct the same vehicle’s gas, repairs, insurance, registration, lease payments, or depreciation under the actual-expense method for that period. |
| Actual expenses | Allowable vehicle costs multiplied by the business-use percentage, with depreciation or lease costs treated under the applicable rules | Potentially includes fuel, oil, tires, repairs, insurance, registration, licenses, garage rent, depreciation for an owned vehicle, or lease payments for a leased vehicle. |
Use the same vehicle, period, and business miles when comparing the two calculations. Do not count commuting as business mileage: ordinary travel between home and a regular workplace is generally commuting, not business travel. Keep tolls and parking attributable to business travel separate from ordinary commuting costs. IRS Publication 463 (2025) explains the federal treatment of vehicle costs and substantiation; check its current-year guidance for your facts.
#1 Best Overall

- KEEP PERFECT RECORDS: Adams Vehicle Mileage and Expense Journals help you log business use of your car or truck with year start and year end odometer readings and flawless daily records
- GET THE BEST DEDUCTION: 588 entries capture the date, odometer readings, total miles and business purpose—everything you need to document business use for the IRS
- SUMMARIES MAKE TAX TIME EASY: Annual summary pages hold monthly mile totals to calculate percentage of business use; monthly maintenance totals help you deduct unreimbursed vehicle expenses
- INCLUDES 6 RECEIPT POCKETS: Don’t forget to save receipts; you get 2 double-sided pockets for oil changes and other service; 2 pockets for repairs, and 2 pockets for parking and tolls
- KEEP IT IN THE CAR: This portable 5-1/4 x 8-1/4 booklet was meant to travel with you; keep one in each glove compartment for a complete record of business use
Which method is more likely to be worth calculating?
Start by calculating both methods if you are eligible to choose. High business mileage and relatively low operating costs per mile can make the mileage method attractive. High business-allocated costs can make actual expenses worth examining. Those are screening clues, not guarantees: depreciation or lease rules, eligibility limits, and the amount of personal use can change the result.
- Consider mileage first if your business miles are substantial, your expense records are limited, or you value a simpler calculation—and your vehicle’s history allows the method.
- Calculate actual costs if business use is high or the vehicle has significant allowable business-allocated costs, such as fuel, insurance, repairs, and depreciation or lease costs.
- Do not decide from one expense alone. Compare the total allowable business deduction under each eligible method, not just fuel costs or the headline mileage rate.
The IRS says the standard mileage rate is based on an annual study of fixed and variable automobile operating costs. Its 2026 rate notice describes the rate as an optional method; taxpayers with adequate records may substantiate actual allowable costs instead. A larger deduction is not useful if the method is unavailable or the records do not support it.
A simple side-by-side example
Suppose a vehicle has 5,000 eligible business miles from January through June 2026 and 4,000 from July through December. The mileage calculation is 5,000 × $0.725, or $3,625, plus 4,000 × $0.76, or $3,040—a total of $6,665. This is only a mileage-method illustration; it assumes the trips qualify and the taxpayer is allowed to use that method.
For an actual-expense comparison, imagine allowable vehicle costs for the same period total $15,000, including any depreciation or lease cost permitted under the rules, and the vehicle was driven 18,000 total miles, of which 9,000 were business miles. The business-use share is 50%, so the illustrative allocated amount is $7,500. The example does not establish that each cost or depreciation amount is deductible; it shows why you need the same period, vehicle, and mileage basis for a fair comparison. In a real return, method restrictions, cost-specific rules, and adequate records still control.
Federal mileage rates for 2026
These are IRS optional rates per mile. The business rate changed during the year, so divide business trips into the correct date ranges. The IRS attributed the midyear revision to increased fuel prices. The medical and qualifying moving figures below apply only to eligible uses; the moving rate is limited to categories allowed under federal law.
| Use | January 1–June 30, 2026 | July 1–December 31, 2026 |
|---|---|---|
| Business | 72.5 cents per mile (IRS Notice 2026-10) | 76 cents per mile (IRS Announcement 2026-11) |
| Medical and qualifying moving | 20.5 cents per mile (IRS Notice 2026-10) | 23.5 cents per mile (IRS Announcement 2026-11) |
| Charitable service | 14 cents per mile | 14 cents per mile |
The charitable rate is fixed by federal law, as described in the IRS’s 2026 rate notices. These medical, moving, and charitable rates are not substitutes for the business rate. For comparison, the 2025 federal business rate was 70 cents per mile; do not use it to calculate 2026 business travel. IRS Publication 463 (2025) and IRS Notice IR-2025-128 document that prior-year rate.
Rank #2
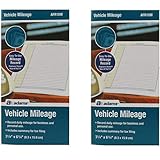
- Sold As 2 Journals
- Adams Vehicle Mileage 3 1/4 x 6 1/4
- Record daily mileage for business and personal use
- Includes summary for tax filing
The rates in the table are federal optional rates, not a promise that every mile driven for one of those purposes qualifies for a deduction. In particular, the moving rate applies only to qualifying categories under federal law, and the medical and charitable categories have their own eligibility rules. Keep the type of trip distinct when you total mileage so you do not apply the business rate to another kind of travel or vice versa.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteHow to compare the methods step by step
- Confirm that the driving is eligible business travel. Separate business trips from personal trips and ordinary commuting. For each business trip, record the date, destination, business purpose, and miles.
- Separate mileage by rate period. Total eligible business miles through June 30, 2026, and from July 1, 2026, onward. Multiply the first total by $0.725 and the second by $0.76. Do not apply a single annual rate to both periods.
- Calculate the business-use percentage for actual expenses. For the same vehicle and period, divide business miles by total miles. Keep the underlying totals, including personal miles, so the percentage can be reconstructed.
- Gather allowable actual-cost records. Collect records for fuel, oil, tires, repairs, insurance, registration, licenses, garage rent, and other relevant costs. For an owned vehicle, determine allowable depreciation; for a leased vehicle, determine the allowable business share of lease costs.
- Apply the business-use share. Multiply eligible mixed-use costs by the business-use percentage, following the rules for each expense and depreciation or lease cost. Do not include personal-use costs.
- Check the vehicle’s method history and restrictions. Before choosing the larger calculation, verify that the method is permitted given when the vehicle first became available for business use, prior depreciation choices, lease terms, and any applicable vehicle or business restrictions.
- Compare the allowed totals, then retain the backup. Keep the mileage calculation, expense records, allocation, and evidence of business purpose with your tax records. If depreciation, a lease, a vehicle conversion, multiple vehicles, or a prior election complicates the calculation, get tax advice before filing.
For a practical worksheet, make one line for each rate period and one column for each method. Under mileage, enter only eligible business miles and the applicable rate. Under actual expenses, list each allowable vehicle cost, calculate the business-use percentage for the matching period, and apply it as appropriate. Leave out operating costs and depreciation represented by the mileage rate if you are calculating that method. Keep a note of any separate business parking or toll amounts rather than silently adding them into the rate calculation.
This comparison is easiest when the underlying data covers the same vehicle and period. If one set of cost records covers a full calendar year but the mileage or business-use calculation covers only part of it, reconcile the periods before comparing. A rough estimate may help you decide whether to gather more records, but do not treat it as the final deduction.
Method choices can affect later years
Owned vehicle: the first business-use year matters
For an owned vehicle, the first year it is available for business use is a key decision point. To use the standard mileage rate for an owned car, a taxpayer generally must choose it in that first year. If actual expenses are used in that first business-use year, the taxpayer generally cannot switch to the standard mileage rate for that car in a later year.
If the standard mileage method is chosen in the first business-use year, switching to actual expenses later can still affect depreciation. IRS Publication 463 (2025) explains that a switch from mileage to actual expenses may require straight-line depreciation and can prevent use of MACRS depreciation. Because the consequence can extend beyond the year being calculated, compare the methods before making the initial choice rather than treating it as a routine annual change.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchLeased vehicle: the choice generally lasts through the lease
If you use the standard mileage method for a leased vehicle, you generally must continue using it for the entire lease period, including renewals. The choice is therefore not simply a year-by-year comparison. Review the lease history and the rules in IRS Publication 463 (2025) and the Instructions for Form 2106 (2025) before selecting a method.
Rank #3

- Comprehensive Package for Long Term Use: this package comes with 6 auto mileage and expense notebooks; Each mileage log book for car contains 32 pages; This sufficient quantity enables you to keep track of your expenses for a longer period
- Ideally Sized for Convenience: with dimensions of 6.3 x 3.3 inches, the vehicle mileage log book is the ideal size to carry around; Its compact nature ensures you can easily tuck it into your glove compartment or bag, ready to jot down important information whenever the need arises
- Quality Material for Ease of Use: the vehicle book is made from quality paper, providing a smooth writing surface for all your record keeping needs; This ensures clear documentation of all your auto mileage and expenses for easy reference
- Organized Layout for Detailed Record Keeping: each car mileage log book boasts an organized layout with appropriate categories; You can track different types of expenses like mileage, oil changes, parking charges, and even cleaning and repair costs; The 2 page layout allows you to track expenses by day over a 12 months period, with monthly and annual summary pages on the back for easy accurate recording; This gives you a clear and broad view of your vehicle's running costs
- Ideal for Divers: the mileage tracking book constitutes the ideal tool for divers with features specifically designed for auto mileage and expense logging; They provide a systematic way of recording mileage, gas usage, oil changes, and other vehicle related expenses incurred
Prior deductions and special situations
Depreciation methods, prior elections, vehicle characteristics, business-use percentage, and other restrictions can affect eligibility or the amount allowed. The general comparison is not enough to resolve every special case. Verify the rules for the tax year being filed, particularly if the vehicle changed from personal to business use, is leased, or has a complicated depreciation history.
These method rules are why “which is bigger this year?” is not always the first question. First establish which methods are available for this vehicle in this year, given its prior use and elections. Then compare the allowable amounts. A larger theoretical total under a method you cannot use does not determine the deduction.
What actual expenses can include—and how to allocate them
Actual expenses may include fuel, oil, tires, repairs, insurance, registration, licenses, garage rent, and other allowable vehicle costs. For an owned vehicle, depreciation may be included subject to the applicable rules and limits. For a leased vehicle, eligible lease costs may be included instead of depreciation. The list of costs does not mean every charge is deductible in full: business use and applicable tax rules determine the allowable amount.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
For a vehicle used both personally and for business, the business-use percentage is commonly calculated as business miles divided by total miles. For example, if a vehicle’s records show 8,000 business miles out of 20,000 total miles for the relevant period, the business-use percentage is 40%. That arithmetic illustrates the allocation only; it does not establish that any particular expense or depreciation amount is allowable. Maintain total, business, and personal mileage records that support the calculation.
Do not combine methods for the same vehicle and period by claiming the mileage allowance and then adding the operating costs or depreciation already represented by that rate. Business parking fees and tolls may be separately deductible under IRS rules when attributable to business travel; they do not turn commuting into business travel. Confirm the treatment in the current IRS publication for your circumstances.
When sorting receipts, separate vehicle operating expenses from costs that need a different treatment, such as depreciation for an owned car or lease payments for a leased car. The method comparison is not simply “all receipts versus the mileage allowance”: the actual-cost calculation must include only amounts allowed for the vehicle and business use, while the mileage rate already accounts for operating costs and depreciation. Keep enough detail to identify what each payment covered and which vehicle it relates to.
Rank #4

- Sold as 1 EA.
- Mandatory records for all who use their automobile for business purposes. Records mileage, parking fees and tolls.
- Features a detachable year-end summary for tax advisor.
- Undated-start any time.
- Good for one full year.
Records to keep for either method
Good records establish both that the trip or expense occurred and that it had a business purpose. IRS guidance calls for substantiation of business use and expenses; an app or paper logbook is a recordkeeping aid, not proof that a trip qualifies by itself.
- For every business trip: date, starting point and destination, miles driven, and business purpose. Record trips close to when they occur rather than relying on memory at tax time.
- For a mixed-use vehicle: beginning and ending odometer readings or equivalent records that establish total miles, as well as business and personal mileage.
- For actual expenses: receipts, bills, or other records identifying the cost, date, vehicle, and amount. Keep records for depreciation or lease costs as applicable.
- For the calculation: retain the rate period used, mileage totals, business-use percentage, and how each expense was allocated.
A useful trip record answers more than “how far did I drive?” It should let you identify when the trip occurred, where it went, why it was business-related, and how many miles were attributable to it. A calendar entry or appointment record may help explain a trip’s purpose, but keep the mileage details too. For actual expenses, organize supporting documents so the expense total can be tied to the vehicle, period, and allocation in your calculation.
A business mileage-tracking app or vehicle mileage logbook can help capture trip details. Neither guarantees compliance or decides whether a trip is deductible; review and retain the information needed to substantiate the claim.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Employees and state taxes are different questions
This comparison is primarily for self-employed taxpayers and business owners. Under the general federal rule described in IRS Publication 463 (2025), unreimbursed employee vehicle expenses are not deductible as miscellaneous itemized deductions, subject to statutory exceptions. A W-2 employee should not assume that choosing one of these methods creates a federal deduction; reimbursement arrangements and any applicable exception need separate review.
The rates and method discussion here concern U.S. federal tax treatment. State tax rules, business structure, reimbursement arrangements, vehicle class, depreciation limitations, business-use percentage, and special exceptions can change the result. Check the applicable rules and forms for the state and tax year at issue.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →A practical decision checklist
- Are the miles genuinely for business rather than commuting or personal use?
- Do you have the trip records and business-purpose details to substantiate those miles?
- For 2026, did you apply 72.5 cents per mile through June 30 and 76 cents per mile from July 1?
- Can you document the total miles and business-use percentage needed for an actual-expense calculation?
- Have you included only allowable business portions of costs and handled depreciation or lease payments under the applicable rules?
- Does the vehicle’s first business-use year, method history, or lease term limit your choice?
- Are you an employee, or do state rules or another special circumstance require a separate analysis?
If the mileage method is allowed and produces the larger supported amount, it may be the simpler choice. If the business share of actual costs is greater, actual expenses may be preferable—but method history and depreciation rules can outweigh that year’s arithmetic. For an owned vehicle, leased car, vehicle conversion, multiple vehicles, or prior method election, a tax professional can help verify which comparison is legally available.
Frequently Asked Questions
Can I deduct gas and repairs if I use the standard mileage rate?
Generally, no. The standard mileage rate already accounts for vehicle operating costs and depreciation, so you do not also deduct gas, repairs, insurance, registration, lease payments, or depreciation for the same vehicle and period under the actual-expense method. Business-related parking fees and tolls may be separately deductible under IRS rules; check current guidance for your facts.
Can I switch from the standard mileage rate to actual expenses?
For an owned vehicle, the first year it is available for business use is especially important. If you chose the standard mileage rate in that first year, switching to actual expenses later may be possible, but depreciation treatment can be affected: a switch may require straight-line depreciation and can prevent MACRS depreciation. If you used actual expenses in the first business-use year, you generally cannot later switch that car to the standard mileage rate. For a leased vehicle, using the mileage method generally means continuing it for the entire lease term, including renewals.
Are commuting miles deductible as business mileage?
Ordinary travel between home and a regular workplace is generally commuting, not business travel. Keep commuting separate from eligible business trips, and retain trip dates, destinations, miles, and business purposes for the miles you claim.
Recommended Free Tools
Can a W-2 employee claim either vehicle deduction?
Do not assume so. The general federal rule is that unreimbursed employee vehicle expenses are not deductible as miscellaneous itemized deductions, subject to statutory exceptions. Reimbursement arrangements and any exception need separate review.
What records should I keep to support a vehicle deduction?
For business trips, record the date, starting point and destination, miles, and business purpose. For mixed use, keep total and business mileage information, such as odometer readings, so you can support the business-use percentage. For actual expenses, retain receipts or bills showing the amount, date, vehicle, and type of cost, along with records for depreciation or lease costs as applicable. A logbook or app can help capture details but does not itself establish that a trip qualifies.
The Bottom Line
There is no universal winner between the standard mileage rate and actual vehicle expenses. Compare the eligible business miles at the rate for each trip date with the allowable business-use share of actual costs, then confirm that your vehicle’s history, lease terms, records, and tax-year rules permit the method. For 2026 business driving, use 72.5 cents per mile through June 30 and 76 cents per mile beginning July 1. Keep trip and expense records either way.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →



