For U.S. federal tax purposes, physical silver bullion held as an investment can be a collectible. If you sell it for more than its adjusted basis, the gain is generally a capital gain: a holding period of one year or less means short-term treatment at ordinary graduated rates, while a gain on silver held for more than one year may fall under the collectibles rules, which have a maximum 28% rate. That 28% is a ceiling, not an automatic tax bill; the regular tax computation applies when it produces a lower result.
What tax rules apply to silver?
This overview covers U.S. federal income tax for an individual selling physical silver held as a capital asset. The IRS includes metal such as silver bullion in its discussion of collectibles. That classification matters mainly when a gain qualifies for long-term treatment: the maximum rate for net gain from collectibles is 28%, rather than the usual long-term capital-gain rates that often apply to other assets. The IRS says to use the regular tax computation if it results in lower tax. See IRS Publication 550 (2025) and IRS Topic 409.

As an Amazon Associate I earn from qualifying purchases.
The rate category does not mean every person who sells silver owes 28%. Your tax depends on whether the sale produced a gain or loss, how long you held the asset, and the tax computation for your return. Tax is not generally calculated by applying a rate to the entire sale price: the starting point is the difference between the amount realized and adjusted basis.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
These rules should not automatically be applied to silver held through a fund, partnership, trust, business, or retirement account. Those structures may have different tax treatment. State and local tax treatment also depends on jurisdiction and is not addressed by the federal IRS guidance cited here.
#1 Best Overall

- ► These silver bars feature a mirror like finish
- ► Small pieces of silver are great for barter, collectors’, add to your collection or start yours today
- ►1 gram .999 FINE Pure Silver Bars or Rounds, size’s may vary,
- ► Designs are selected at random and may include military and religious themes and animals
- ►10 one gram pure fine silver ingots
How to work out whether a sale produced a gain
For a capital-asset sale, the basic calculation is:
Gain or loss = amount realized − adjusted basis
Amount realized is the amount you received in the transaction; adjusted basis is your tax basis after any applicable adjustments. In a straightforward purchase-and-sale situation, your records of what you paid and what you received are central to the calculation. The sale price alone does not tell you the taxable gain.
For example, suppose an investor sells silver for $1,400 and the adjusted basis for the silver sold is $1,000. The calculation produces a $400 gain before applying the relevant holding-period and tax rules. This illustration shows the arithmetic only; it does not determine the seller’s tax due. A sale below adjusted basis can instead produce a loss, subject to the rules that apply to the taxpayer and transaction.
Free tools Windows power users keep installed
One-click scans. No signup required.
Keep documentation that lets you establish the purchase cost, sale proceeds, and acquisition and sale dates. Basis may require fact-specific adjustments. Do not assume the same basis method applies to silver received as a gift or inheritance, silver held in a business, or silver inside a retirement account. The IRS’s general capital-transaction reporting guidance is in Instructions for Form 8949.
When you have multiple purchases, avoid treating all the silver as one undated holding. The calculation needs to match the amount received to the silver sold and to the basis and acquisition date relevant to that property. Keep records organized by transaction or lot so you can support both the arithmetic and the holding-period classification. If records are incomplete or the basis is uncertain, do not substitute the original purchase price for a fact-specific basis determination.
Rank #2

- Exceptional Craftsmanship: This pack of 20 One Ounce copper bar reflects superior quality and detailed artistry, supporting American craftsmanship and excellence.
- .999 Fine Copper Purity: Made with .999 fine copper, this bar ensures exceptional purity and durability, making it a standout addition to any collection or investment portfolio.
- Iconic Walking Liberty Design: Featuring the timeless Walking Liberty, a stunning depiction of Lady Liberty striding confidently with a flowing gown against a radiant sunrise, symbolizing freedom, progress, and heritage.
- Perfect Dimensions: Compact and sleek at 2 x 1.12 x 0.12 inches, the bar is easy to store, display, or gift—ideal for both collectors and first-time investors.
- A Versatile Gift & Functional Keepsake: The perfect gift for collectors, students, or enthusiasts, this bar also serves as a stylish paperweight for desks, blending elegance with everyday functionality.
Why the holding period changes the tax treatment
The key dividing line for this overview is one year:
- Held one year or less: the gain is generally short-term. Net short-term capital gain is taxed at ordinary graduated income-tax rates.
- Held more than one year: the gain is generally long-term. If the silver is a collectible, the collectibles rate rules may apply to the net gain.
Count the holding period using the dates relevant to the particular transaction and confirm the treatment under the instructions for the tax year you are filing. Do not infer long-term treatment just because the sale occurred in a later calendar year: the relevant question is whether the asset was held for more than one year.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchFor eligible long-term collectible gain, 28% is a maximum rate, not a flat rate charged to every seller. IRS Topic 409 describes net capital gains from collectibles as taxed at a maximum 28% rate. The IRS also says the regular tax computation applies if it yields a lower tax. The outcome depends on the taxpayer’s return and applicable computation; the figure alone is not enough to calculate a bill.
This is an important distinction from the more familiar long-term capital-gain rates that often apply to other assets. The collectible classification can mean a higher maximum rate applies, but it does not set an automatic rate for every dollar of gain. Short-term gains have a different framework: net short-term capital gains are taxed at ordinary graduated rates rather than receiving the collectibles maximum-rate treatment described for long-term gain.
How to report a silver sale on a federal return
For most individuals selling a capital asset, the usual path is to report the transaction on Form 8949 and summarize capital gains and deductible losses on Schedule D (Form 1040). The IRS Schedule D instructions include a 28% Rate Gain Worksheet for relevant collectibles gain or loss. Use the forms and instructions for the tax year of the return, since the applicable versions can change. The current guidance cited here includes the 2025 Instructions for Schedule D and the Instructions for Form 8949.
Rank #3
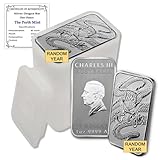
- Purity: .9999 Fine Silver
- Dimensions: 47.6 x 27.6 mm: Thickness: 3.57 mm
- Metal Content: 1 Troy Ounce per coin; Total: 10 Troy Ounces
- Depending on the year you receive, the coin may feature either Queen Elizabeth II or King Charles III.
- Five Coins per Purchase: Each order includes five coins. We select random-year coins from the same tube, so all five coins in your order will typically be from the same year. Mixed-year orders are unlikely.
- Gather transaction records. Identify the silver sold, the date acquired, the date sold, the amount received, and records supporting adjusted basis.
- Calculate the gain or loss. Compare amount realized with adjusted basis for the property sold. Keep the calculation tied to the specific transaction rather than treating all sale proceeds as gain.
- Determine the holding period. Establish whether the asset was held one year or less or more than one year. This determines whether short-term or long-term rules generally apply.
- Report the capital transaction. Follow the applicable Form 8949 instructions and transfer or summarize the amounts as directed on Schedule D.
- Apply the collectibles worksheet when applicable. If the transaction involves relevant long-term collectibles gain or loss, consult the 28% Rate Gain Worksheet in the Schedule D instructions and follow that tax year’s directions.
Form 8949 and Schedule D serve related but distinct roles: the former is the usual place to list capital transactions, while Schedule D summarizes capital gains and deductible losses as directed by its instructions. The worksheet is not a substitute for reporting the transaction; it helps apply the relevant collectibles calculation when applicable. Follow the current-year forms rather than carrying forward an assumption about a line, category, or worksheet from a prior return.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Receiving a tax information form does not by itself decide whether the transaction is taxable, and not receiving one does not remove a taxpayer’s own reporting obligation. Keep the broker’s records alongside your purchase documents so that any reported proceeds can be reconciled with your basis and return entries.
Why a silver sale may not come with Form 1099-B
A broker does not necessarily have to issue Form 1099-B for every precious-metal sale. IRS information-reporting exceptions depend on details such as the metal’s form, whether it is eligible for trading under a CFTC-approved regulated futures contract, and whether the quantity meets the minimum contract quantity. The instructions also address aggregation during a 24-hour period and an anti-avoidance qualification. These are broker information-reporting rules, not a calculation of the seller’s taxable gain.
Because the relevant tests are technical and depend on the transaction, do not use the presence or absence of Form 1099-B as a substitute for determining your own reporting duties. For the applicable details, consult the IRS Instructions for Form 1099-B (2026) and the IRS correction to the precious-metal Form 1099-B instructions.
In other words, two questions must stay separate: whether a broker has an information-reporting duty for a particular sale, and whether you have a taxable capital transaction to report. A missing 1099-B does not establish that no gain occurred or excuse reporting. Likewise, receiving the form does not establish the amount of your gain, because the gain calculation depends on amount realized and adjusted basis.
Rank #4
Cases where the general bullion explanation may not fit
The answer can change when the asset or ownership arrangement is not a personal capital asset consisting of physical bullion. Before applying the general rules, identify what was sold and who owned it.
- Physical bullion held personally: This is the situation addressed by the general discussion above; IRS Publication 550 identifies silver bullion among collectibles.
- Fund, partnership, or trust interest: The item sold is an interest in an entity or arrangement, not necessarily the bullion itself. Do not assume the physical-metal collectible rule alone determines its treatment.
- Business inventory or business-held silver: Business activity can affect how a sale is classified and reported. The individual-investor explanation does not settle those facts.
- Retirement-account ownership: The account and its rules may affect taxation; do not report it automatically as a personal sale of bullion.
- Gift or inheritance: The basis may depend on circumstances not resolved by the general capital-gain formula. Establish the applicable basis before calculating gain or loss.
For these situations, determine the relevant ownership and basis rules before relying on a generic bullion calculation. A tax professional can help apply current federal and jurisdiction-specific rules to unusual ownership histories or records. The same caution applies when comparing transactions: physical bullion, an interest in an entity, business inventory, and retirement-account assets are not interchangeable tax categories simply because each may relate to silver.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Records and decisions to check before filing
- Confirm that the sale was of physical silver owned as a capital asset, rather than an entity interest, business inventory, or retirement-account asset.
- Match the sale proceeds to the silver actually sold and retain the supporting sale record.
- Locate records showing when and how the silver was acquired and what basis applies.
- Verify the holding period for each lot or transaction instead of assuming all silver was held for the same length of time.
- Use the correct tax-year Form 8949 and Schedule D instructions, including the collectibles worksheet if applicable.
- Report the transaction based on the tax rules even if no Form 1099-B arrives; reconcile any information return you do receive with your own records.
The federal sources in this article provide general rules, not a determination for every seller. The IRS guidance cited here does not settle all inherited- or gifted-property basis questions, business treatment, retirement-account cases, state or local rules, or seller-specific adjustments.
Frequently Asked Questions
Is silver bullion taxed as a collectible?
For U.S. federal capital-gain purposes, IRS Publication 550 (2025) includes silver bullion in its discussion of collectibles. That treatment applies to the physical bullion situation described here; do not automatically extend it to a fund, partnership, trust, business, or retirement-account interest.
Do I pay 28% tax when I sell silver?
Not automatically. The 28% figure is a maximum rate for eligible net long-term collectibles gain, not a flat tax on every sale or on all proceeds. Your result depends on whether you have a gain, the holding period, and your tax computation; the IRS says the regular computation applies if it produces a lower tax.
Best Value

- Element-inspired Ingot bar design
- Sophisticated addition to any workspace
- 99.9% fine silver-plated finish for lasting shine
- You will receive one paperweight per purchase
- One-pound weight for practical use and impressive presence
How do I report selling silver on my tax return?
For most individual capital-asset sales, report the transaction on Form 8949 and summarize it on Schedule D (Form 1040), following the instructions for the tax year being filed. The Schedule D instructions include a 28% Rate Gain Worksheet for relevant collectibles gain or loss.
Do I get a 1099-B for selling silver?
Not necessarily. Broker reporting exceptions for precious metals depend on factors such as the metal’s form, whether it is eligible for trading under a CFTC-approved regulated futures contract, and whether the quantity meets the minimum contract quantity. Whether a broker issues Form 1099-B is separate from your own obligation to determine and report a taxable sale.
Is tax based on the full silver sale price?
Generally, the capital gain or loss calculation starts with amount realized minus adjusted basis. The amount you received is not automatically all taxable gain; retain records supporting the proceeds, basis, and acquisition and sale dates.
The Bottom Line
For a U.S. individual selling physical silver bullion as a capital asset, calculate gain or loss using amount realized minus adjusted basis, then determine the holding period and follow the applicable Form 8949 and Schedule D instructions. Long-term collectible gain can face a maximum 28% rate, but that is not an automatic tax on sale proceeds, and the regular tax computation applies when lower. A missing Form 1099-B does not by itself remove the reporting obligation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




