Property and casualty (P&C) insurance is a broad category of coverage for losses involving property and liability. Property coverage can pay for covered damage to your home, belongings, or car; liability coverage can help when you are legally responsible for injuring someone or damaging their property. Homeowners, renters, and auto insurance are familiar examples. The label alone does not guarantee a particular loss is covered: the policy’s terms, exclusions, limits, deductible, and applicable state rules determine what protection you have.
What does “property and casualty” mean?
“Property” refers to insured things—such as a house, personal belongings, or vehicle—that may be damaged, destroyed, or stolen. “Casualty” commonly refers to liability protection for harm to other people or their property. The National Association of Insurance Commissioners (NAIC) defines casualty insurance as liability insurance for negligent acts and omissions, and lists workers compensation, errors and omissions, fidelity, crime, glass, boiler, and various malpractice coverages as examples. P&C is an umbrella term for property protection and casualty or liability lines; classifications can vary by jurisdiction and insurer. NAIC insurance glossary
As an Amazon Associate I earn from qualifying purchases.
These parts address different financial problems. If a covered event damages your own insured property, property coverage may apply. If you are legally responsible for injury or damage to someone else, liability coverage may respond, subject to its terms and limits. A policy can include one or both kinds of protection.
Is auto insurance property and casualty insurance?
Yes. Auto insurance is a common personal-lines example of P&C: liability coverages address harm you may cause to others, while collision and comprehensive can cover specified damage to your own car. What is included, and what is required, depends on the policy and state. NAIC auto insurance guide
#1 Best Overall

- Store (Family) Papers Safe & Sound: Keep all your essential papers safely in one spot with ZICOTOs’ important document organizer. Swiftly locate anything from legal to medical papers for the whole family. Ditch the paper chaos, embrace order & enjoy the simplicity with the Zicoto expanding file folder
- Organize It Like a Pro: Get super organized with 8 large, numbered envelopes (9.5x12”), each holding 40+ letter-sized sheets. Perfect for documents, passports, photos, and more. The document folder organizer transforms your paper clutter into a masterpiece of order!
- Customize to Your Needs: The important document folder organizer binder lets you label each section your way with a customizable table of contents, numbered envelopes and a sticker sheet with blank & pre-named stickers. Your Binder, your way - organizing has never been this easy!
- Ample Space for Everything: The 12.8x10.83” document organizer folio is perfect for your 8.5x11" letter size or A4 papers. Need more room? No worries, the life binder includes a handy back pocket for extra documents, notes and more. Keep everything neatly stored and easily accessible
- Stylish & Practical Premium Design: Featuring a chic linen cover in modern sage with classy golden edges, the expanding file folder looks as good as it functions. An elastic band keeps everything in place - no more loose papers flying around!
Liability and injury-related coverages
- Bodily injury liability can address covered claims when you are legally responsible for injuring someone in an auto accident.
- Property damage liability can address covered damage you cause to another person’s property, such as their vehicle.
- Uninsured or underinsured motorist coverage may help in covered situations involving a driver with no insurance or insufficient insurance.
- Medical payments or personal injury protection (PIP) may be available or required in some states, with details determined by state law and the policy.
Damage to your own vehicle
- Collision generally addresses covered damage to your car from a collision with another vehicle or object.
- Comprehensive generally addresses many non-collision causes, such as theft, fire, severe weather, or vandalism. Covered causes and exclusions depend on the contract.
NAIC guidance says collision and comprehensive are not generally required by state law, though a lender or lessor may require them for a financed or leased car. State-required auto coverages and minimum limits differ, so check your state’s rules and loan or lease terms. For details, see the NAIC’s auto coverage explainer.
How do homeowners and renters insurance fit?
Homeowners policies commonly combine protection for the home and belongings with liability coverage. The policy may include several coverage parts, but their availability and limits depend on the form you buy.
Rank #2
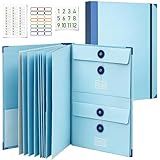
- Keep Important Family Records Together:Keep birth certificates, passports, insurance paperwork, medical records, tax documents, legal papers and other essential family records in one organized place instead of spreading them across drawers, cabinets and separate folders.
- 12 Sections for Different Document Sizes:Three vertical, three horizontal and six half-size sections give different types of paperwork their own space, making this document folder organizer easier to use for full-size papers, passports, certificates, cards and smaller records.
- Fits Standard Letter-Size Papers:Sized for standard 8.5 × 11 in documents, the full-size sections hold important papers while half-size sections provide convenient space for passports, certificates, cards and smaller records.
- Made for Important Life Events:Use this folder for important documents for estate planning, moving, emergency preparedness, insurance matters and other major life events, helping essential family information stay organized and easier to access when needed.
- Practical Home Filing for Everyday Records:Use this family document organizer for household paperwork, personal records, tax-season documents and frequently needed files. A practical home document organizer for keeping important information organized and easier to find throughout the year.
Common homeowners coverage parts
- Dwelling covers the insured home for covered causes of loss.
- Other structures may cover structures on the property separate from the home, such as a detached garage.
- Personal property may cover belongings, subject to limits, exclusions, and the policy’s valuation rules.
- Loss of use or additional living expense may help with qualifying extra living costs if a covered loss makes the home uninhabitable.
- Personal liability may respond to certain claims that you are legally responsible for injury or property damage.
- Medical payments may cover certain medical expenses for others, as described in the policy.
Renters insurance generally focuses on a tenant’s belongings and personal liability rather than the building itself. A renter should check what the policy covers and what the landlord’s insurance is responsible for; do not assume the landlord’s policy insures the tenant’s possessions. The NAIC’s homeowners consumer guide explains common coverage components.
Flood, earthquake, and how property is valued
Standard homeowners coverage does not necessarily cover flood or earthquake losses. Flood insurance is commonly a separate policy; earthquake protection may require an endorsement or separate policy, depending on the product. Check the contract and consider whether separate coverage is needed for risks in your area. NAIC homeowners insurance topic page
Rank #3

- Perfect auto car document holder, keeps your registration and insurance paperwork, business cards, emergency information all well organized and looks better than papers just scattered in the glove box.
- Clear and easy to read both documents when you open it up, which is easy and stress-free to reach for your documents, knowing exactly where they are when asked.
- This practical wallet case is perfect to maintain your car paperwork secured and protected. With 5 clear sleeves for your gas card, car registration and insurance informations in.
- Excellent quality with beautiful sleek and trim design, this holder is made of durable PU leather and heavy duty vinyl PVC.
- Dimensions: 9.5" x 5.1"(24cm x 13cm) - Wisdompro slim, lightweight car insurance registration holder is perfect for placement in any glovebox or console.
For covered personal property, a policy may settle a claim on a replacement-cost or actual-cash-value basis. Replacement cost estimates the cost to repair or replace without subtracting depreciation; actual cash value accounts for depreciation. The specific definition, limits, and claim conditions in the policy govern what you receive.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Does P&C cover every kind of loss?
No. P&C is a category, not a promise that every accident or type of damage is insured. A policy applies only as its contract provides. Home policies may define coverage through named perils or through exclusions; even a policy described as broad or “all-risk” remains subject to exclusions, limits, and conditions. An auto policy’s comprehensive coverage likewise applies to covered non-collision causes, not every conceivable loss.
Rank #4

- 👁️Quick Accessible: Inside the car insurance and registration card holder, the clear inner material makes you easy to find documents when you open it up, you can see exactly what they are and quickly show them when asked, even no need to take the stuff out.
- 💼Document Well Organized: The car document holder keeps your car documents organized and keep them tidy and secured, which make it easy to quickly identify and reach paper or cards in the folder. The glove box organizer for car has 6 compartments to keep all your car essential auto car essentials organized.
- 🧲Hidden Magnetic Closure: The glove box document holder are built with hidden magnetic closure, which will keep your car paperwork organizer neat and tidy and ensure the certifications stay closely and and completely protective within the registration pouch.
- 💖Premium Material: The car manual holder is made from high-quality ECO-friendly PU leather material. The car insurance holders with the best sewing and crafted is durable, wear-resistant, and has a luxurious look. This material of the registration holders is durable, wear resistant and waterproof. The insurance card holder for car has a clear window so you can easily see all the documents when you open it up.
- 🌷Compact Size: With the perfect size dimensions of 5.0in x 9.4in x 0.4in, this vehicle license and registration holder for car will fit into glove compartments, sun visors, door holders, consoles, etc. The glove box organizer is precisely designed to fit all of your car documents.
Before relying on a policy, identify the property, people, and events it covers; read exclusions and any endorsements; and check limits, sublimits, and deductibles. If a risk is excluded or limited, ask your insurer or a licensed agent whether another policy or endorsement is available.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsWhat other kinds of P&C insurance are there?
The category extends beyond personal homes and cars. The NAIC’s casualty examples include workers compensation, errors and omissions, fidelity, crime, glass, boiler, and malpractice coverages. Some address liability exposures; others cover specified losses. Their scope varies substantially by product, jurisdiction, and contract, so the name of a line is not enough to determine what a particular policy covers. NAIC insurance glossary
How to compare P&C policies
A lower premium does not necessarily mean equivalent protection. Compare the contract details side by side, especially when quotes use different limits, deductibles, or settlement methods.
- List what and who are insured. Confirm the covered property, people, vehicles, and situations.
- Check covered causes and exclusions. Look for risks that are excluded, restricted, or available only through an add-on.
- Compare limits and sublimits. A limit caps payment for a covered claim; a sublimit may cap payment for a particular category of property or loss.
- Compare deductibles. This is the amount you generally pay toward a covered claim before the insurer pays, subject to the policy’s terms.
- Review the settlement basis. Check whether claims are settled at replacement cost or actual cash value and how those terms are defined.
- Compare premiums only after coverage. Evaluate price alongside the protection actually offered, not as a substitute for it.
- Check outside requirements. Confirm applicable state auto requirements and any lender or lessor requirements for a vehicle.
Rules, available forms, insurer offerings, exclusions, and endorsements vary. This is a U.S.-centered overview, not state-specific coverage advice. The NAIC auto explainer is dated June 11, 2026, and its homeowners topic guidance was last updated October 25, 2025. For a decision about a particular loss or required coverage, read the policy and consult your state insurance department or a licensed insurance professional.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




