Dyed diesel is fuel marked with red dye to identify it for certain uses that are exempt from federal diesel excise tax. It is not a general-purpose discount: eligibility depends on the fuel’s use and federal tax rules, and using it for a taxable purpose—such as driving a highway truck—can trigger tax and penalties. This is a U.S. federal overview; state and local rules may differ.
What is dyed diesel?
For federal excise-tax purposes, dyed diesel is diesel fuel marked to distinguish fuel intended for specified nontaxable uses. IRS Publication 510 describes qualifying fuel as containing Solvent Red 164 at the required concentration, with no other dye, or a dye type and concentration approved by the Commissioner. The dye must be applied indelibly by mechanical injection. IRS Publication 510 (December 2025) also requires a legible warning on applicable shipping documents and at retail pumps or delivery facilities:
“DYED DIESEL FUEL, NONTAXABLE USE ONLY, PENALTY FOR TAXABLE USE.”
The color is a regulatory identifier, not a guarantee that every sale or use is tax-free.
Recommended Free Tools
#1 Best Overall

- Accurate Detection in Seconds: Identify water contamination quickly, ensuring diesel quality and protecting your engine.
- Compatible with All Diesel Systems: Perfect for diesel tanks, backup generators, boats, trucks, and agricultural equipment.
- Easy-to-Use Testing Solution: Simple instructions make testing your fuel hassle-free—no special tools required.
- Reliable Results, Every Time: Trusted by professionals for routine maintenance and preemptive quality checks.
- Portable & Cost-Effective: Compact kit for on-the-go testing—save time and money by catching issues early.
How is dyed diesel different from regular diesel?
The useful distinction is how the fuel is marked, what uses qualify, and how federal excise tax applies—not a demonstrated difference in engine performance or fuel formulation. The IRS sources cited here do not establish that dye makes diesel more powerful, less efficient, lower quality, or mechanically incompatible.
| Factor | Dyed diesel | Regular highway diesel |
|---|---|---|
| Identification | Indelibly dyed to identify fuel intended for qualifying nontaxable uses under federal rules. | Undyed fuel; IRS farmer guidance describes it as taxed fuel for highway use. |
| Federal excise-tax treatment | Generally not subject to federal diesel excise tax when the statutory conditions are met; the LUST tax may still apply. | Ordinary highway diesel is generally sold with applicable federal tax. |
| Use | Limited to uses that meet an applicable federal nontaxable-use category and any other requirements. | Used for taxable purposes such as ordinary highway driving. |
| Performance | Not established as different by the IRS tax sources cited here. | No comparative performance finding is established by those sources. |
The IRS explains the conditions for dyed-fuel treatment and the continuing LUST tax in Publication 510; its farmer guidance distinguishes undyed, taxed fuel for highway use in Publication 225 (2025).
Rank #2
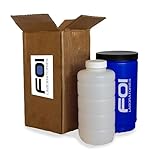
- LAB TESTING NOT INCLUDED — This purchase is the life-safety FOI diesel fuel sample collection and shipping kit. It provides the materials and documentation needed to properly collect in continuity and submit a diesel fuel sample to a laboratory. Laboratory analysis and testing fees are purchased separately.
- FIRST STEP IN THE CONTINUITY WORKFLOW — The standby sample kit establishes the prepared starting point for an FOI fuel-quality event. Having the correct sampling materials, documentation, and shipping pathway, stand-by ready, allows the continuity workflow and chain of custody to begin at the time the sample is taken rather than after materials must be sourced.
- ESTABLISHES DOCUMENTED SAMPLE CUSTODY — The included Sample Information Form (SIF), container, secondary containment, absorbent materials, isolation packaging, and instructions support a documented chain of custody, tracking the sample from the source thru final record.
- WHAT'S INCLUDED — A engineered life-safety diesel-compatible sample container, secondary containment, absorbent material, isolation packaging, shipping carton, Sample Information Form, and collection/shipping instructions for shipping a diesel sample safely.
- LABORATORY ANALYSIS AVAILABLE SEPARATELY — After collection, the sample may be submitted to FOI Laboratories for the appropriate ASTM D975 / NFPA 110 fuel-quality testing package. Laboratory testing is not included with the purchase of this kit.
Which uses may qualify for dyed diesel?
The IRS Instructions for Form 720 list federal nontaxable-use categories that include farm use, off-highway business use, exports, fuel used in a boat engaged in commercial fishing, and certain specified bus uses. These are categories with their own conditions, not blanket permission for every farm vehicle, piece of equipment, or trip on private property. Consult the applicable category and facts before relying on the exemption. IRS Instructions for Form 720 (June 2026)
A farm connection does not automatically permit highway use
The IRS gives the example of a diesel truck used both on a farm and on the highway: it should use undyed, taxed fuel. A highway trip does not become a nontaxable use simply because it is related to the farm business. IRS Publication 225 (2025)
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Rank #3

- Made in United States
Can you use red diesel in a road truck?
For ordinary highway driving, no: use undyed, taxed diesel. A vehicle’s connection to farming or another qualifying business does not by itself make its highway fuel eligible for the nontaxable treatment. Federal categories are specific, and state or local rules may add requirements; check with the relevant tax or fuel regulator for your jurisdiction.
What are the federal penalties for taxable use?
IRS Publication 510 (December 2025) says a penalty may apply when a person knowingly or with reason to know sells, holds, or uses dyed fuel for a taxable use, or alters the dye. The federal penalty is the greater of $1,000 or $10 per gallon of dyed diesel or kerosene involved. After a first violation, the $1,000 amount increases according to the number of violations. The penalty is in addition to any tax imposed on the fuel. These are federal figures from the IRS; they do not describe every state or local consequence. IRS Publication 510
Rank #4
- Accurate Detection in Seconds: Identify Acid Number quickly, ensuring diesel quality and protecting your engine.
- Compatible with All Diesel Systems: Perfect for diesel tanks, backup generators, boats, trucks, and agricultural equipment.
- Easy-to-Use Testing Solution: Simple instructions make testing your fuel hassle-free—no special tools required.
- Reliable Results, Every Time: Trusted by professionals for routine maintenance and preemptive quality checks.
- Portable & Cost-Effective: Compact kit for on-the-go testing—save time and money by catching issues early.
Does dyed diesel always mean tax-free fuel?
No. The federal treatment depends on the fuel meeting the applicable dye and handling requirements and being used in a qualifying nontaxable category. Qualifying dyed diesel is generally exempt from the federal diesel excise tax, but the IRS says the LUST tax may still apply. The exemption should not be treated as permission to use the fuel for taxable purposes. IRS Publication 510
What changed for certain dyed fuel removed from a terminal after 2025?
A federal provision added by Public Law 119-21 allows an eligible claimant to seek payment equal to federal excise tax previously paid on certain diesel or kerosene later removed from a terminal as eligible dyed fuel for nontaxable use. The IRS says it applies to eligible dyed fuel removed on or after December 31, 2025, and requires, among other conditions, that the claimant paid the earlier tax and that the fuel was removed as eligible dyed fuel. It is a limited tax-recovery process for qualifying claimants, not a general exemption for every buyer or use. See the IRS excise-tax overview and Internal Revenue Bulletin 2026-04.
Quick Recap
Best Value
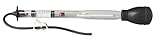
- OTC's 6750 Diesel Fuel Hydrometer allows technicians to quickly troubleshoot engine performance problems and measure #1 and #2 grade diesel fuel quality
- Hydrometer measurements are given as an American Petroleum Institute (API) gravity reading when testing diesel fuel composition and combustion characteristics
- Fuel is drawn into the hydrometer tube which then floats the internal bulb float; Internal float contains a thermometer that is used to compensate the API reading for the highest accuracy
- Hydrometer Scale: 30 to 110; Correction Scale: +2.5 to -5.0; applications include #1 and #2 grade diesel fuels
- Similar to OE tool number J-38641-D; Instructions included
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




