There is no single definition of accidental damage that guarantees cover under every home insurance policy. The policy wording, the cover section you bought, what caused the damage and any exclusions all matter. For UK policies that do not define the term, the Financial Ombudsman Service (FOS) uses a fallback meaning: damage that is unforeseen and unintentional, which can include loss of function as well as visible physical damage. That fallback does not replace the terms of your own policy.
What does accidental damage mean?
Insurers may define accidental damage differently in their policy wording. If a policy has no definition, the FOS says: “We say accidental damage is something that’s: unforeseen; unintentional; not just physical damage – it can also include loss of function.” A blocked drain is one example of loss of function.
The FOS also puts the point plainly: “If your policy doesn’t have a definition of accidental damage, we’ll apply our own.” This is the Ombudsman’s approach to complaints, not a universal definition that overrides an insurer’s wording. Some policies use additional terms such as “sudden,” “breakage” or “external force”; check what your policy says rather than assuming any one of these is always required. Financial Ombudsman Service: Accidental damage.
Is accidental damage included in home insurance?
Not necessarily. Accidental damage may be excluded from a policy’s standard cover, offered as an optional extra, or available for one part of the policy but not another. Check the schedule and wording that applied when the damage happened, and confirm that the relevant cover was selected for the affected item.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →#1 Best Overall

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
Keep three questions separate when considering a claim: was the item covered under the relevant section, does the event meet that section’s definition of accidental damage, and does an exclusion apply? A spill or breakage may be an event worth checking against the wording, but the event alone does not establish that a claim is covered. The insurer may settle an accepted claim through repair, replacement or cash, depending on the case. Financial Ombudsman Service: Home and buildings insurance.
Buildings or contents: which cover applies?
Buildings insurance generally relates to the structure and permanent fixtures and fittings; contents insurance generally relates to household belongings. The same incident can be treated differently under the two sections. A fixture integrated into the property may be treated as buildings, while a removable belonging is usually contents, but the policy wording controls how a particular item is classified.
Rank #2
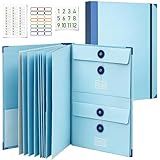
- Keep Important Family Records Together:Keep birth certificates, passports, insurance paperwork, medical records, tax documents, legal papers and other essential family records in one organized place instead of spreading them across drawers, cabinets and separate folders.
- 12 Sections for Different Document Sizes:Three vertical, three horizontal and six half-size sections give different types of paperwork their own space, making this document folder organizer easier to use for full-size papers, passports, certificates, cards and smaller records.
- Fits Standard Letter-Size Papers:Sized for standard 8.5 × 11 in documents, the full-size sections hold important papers while half-size sections provide convenient space for passports, certificates, cards and smaller records.
- Made for Important Life Events:Use this folder for important documents for estate planning, moving, emergency preparedness, insurance matters and other major life events, helping essential family information stay organized and easier to access when needed.
- Practical Home Filing for Everyday Records:Use this family document organizer for household paperwork, personal records, tax-season documents and frequently needed files. A practical home document organizer for keeping important information organized and easier to find throughout the year.
Check both the schedule and the definitions in your policy if it is unclear which section applies. Do not assume that accidental-damage cover selected for contents also applies to buildings, or vice versa. Financial Ombudsman Service: Home and buildings insurance.
What is usually excluded?
Common exclusions include wear and tear, gradual deterioration, deliberate acts and defective workmanship. The exact exclusion and its application depend on the policy wording and circumstances. A problem that developed over time is not necessarily treated as accidental damage simply because it became obvious recently. For an explanation of gradual damage and related cover questions, see the FOS guidance on gradual damage.
Free tools Windows power users keep installed
One-click scans. No signup required.
Rank #3

- High-Quality Materials: Protect your files with ENGPOW fireproof accordion file organizer.It is made of 3-layered non-itchy silicone-coated fiberglass which withstand the temperature up to 2200℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof File Folder is fireproof&Water-resistant,which can effectively protect your important documents in a fire,flood,and wet weather. They will further keep your files intact.Giving you time to save your important documents when disaster strikes
- Accordion File Organizer: A Safe Enough Folder to Keep Your Files. Say goodbye to cluttered files and disorganization with ENGPOW's file organizer folders. Compared with other folders,our fireproof folders is allows you to neatly store and classify letter/A4 files, receipts, cards, USB drives, pen, passports and more in a safe and orderly way. Perfect for daily file filing and storage.The Non-dusty material can prevent dust from sticking to the outside of our folder,always keep it neat and tidy.
- Large Capacity: 14.2" x 10.4" x 2", Compared with other folders, our Accordian File Organizer adopts a multi-layer design that can meet all your storage needs.These include 13 accordion Pockets with labels(each expanding to 1.2 inches),1 zipper pocket,2 pen slot,6 card slots,4 small mesh bags,4 medium mesh bags,and 1 main pocket. You can securely store all your important documents and other items in this fireproof expanding file folder while effectively classifying and finding your files.
- Innovative Humanized Design: Design with a strong grab handle for carrying everything you needed easily. Featuring a double zipper for convenient opening and closing,you won't have to worry about losing any important documents. The included colorful labels make categorizing your files effortless. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place.
- Trusted after sales service: In the event of an emergency, our fireproof accordion file organizer folders are lighter, easier to carry than fireproof safes and quick to grab and go. We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
Does noticing damage recently mean it happened suddenly?
No. The date damage was first noticed and the date it was caused are not necessarily the same. A FOS case study concerned a policy requiring unforeseen physical damage caused suddenly. The policyholder saw cracks in a garage and considered the damage sudden because the cracks had not been visible a week earlier. Reports attributed the movement to a lack of support that had developed over months or years. The Ombudsman agreed that the wording concerned when the damage was caused, not when it became visible. Read the FOS case study.
That case does not mean every newly noticed crack is excluded. Its outcome turned on the policy wording and evidence about the cause. If an insurer says damage was gradual rather than sudden, ask which wording it relied on and how it reached that view.
Rank #4

- 【EXPANDABLE STORAGE FOR IMPORTANT DOCUMENTS】Expandable accordion compartments provide additional space for passports, birth certificates, insurance policies, wills, tax records, medical records, property documents and other important paperwork.
- 【TABS AND POCKETS FOR QUICK ORGANIZATION】Labeled tabs and multiple pockets help organize legal documents, financial records, household paperwork and emergency information for faster retrieval whenever needed.
- 【LARGE CAPACITY DOCUMENT ORGANIZER】Designed to organize growing collections of important documents, estate planning files, insurance information and personal paperwork while keeping everything neatly separated.
- 【FLEXIBLE HOME FILING SOLUTION】The expandable accordion design adapts to increasing storage needs while fitting neatly inside cabinets, shelves, closets, home offices or safes.
- 【READY FOR EVERY STAGE OF LIFE】Keep important documents organized and easy to access for emergencies, tax season, travel, relocation and future planning. Ideal for growing families, homeowners and caregivers.
What evidence can help with a claim?
The FOS says it may consider expert opinions, photographs, reports from surveyors or loss adjusters, and the policyholder’s account of what happened. Keep records that may help explain both the event and its timing:
- Photographs showing the damage, ideally taken as soon as practical.
- A note of what happened and when you first noticed the damage.
- Relevant receipts, messages and correspondence with the insurer.
- Any expert, surveyor or loss-adjuster report you already have.
Records can help establish the facts, but keeping them does not guarantee that a claim will be accepted.
Best Value

- ORGANIZE UP TO 2,000 SHEETS:Store tax records, medical documents, insurance papers, receipts, school assignments, and office files in one place. Expands up to 12 inches and holds up to 2,000 sheets of A4 or letter-size paper.
- STANDS UPRIGHT FOR EASY ACCESS:Unlike traditional accordion folders, the flap can be secured behind the folder using the rear locking hole. Keep documents visible and within reach while sorting, reviewing, or filing paperwork on your desk.
- SORT BY MONTH OR CATEGORY:Includes 12 monthly labels, 24 blank labels, and 12 dividers for flexible organization. Easily manage bills, invoices, projects, household records, school subjects, or client files.
- LARGE TABS & UPGRADED INDEX CARD:Large 4.5 × 1.5 cm tabs provide more writing space for clear labels. The upgraded front index card features larger writing grids, making notes and file references easier to read.
- SOFT-TONE DESIGN & EVERYDAY PROTECTION:Features dividers in Dusty Blue, Blush Pink, Warm Beige, Butter Yellow, Sage Green, and Lavender for easy visual organization. Made from lightweight water-resistant PP material with a flap cover and elastic cord closure to help keep documents protected and organized.
How to check your cover or challenge a rejection
- Find the right documents. Locate the policy schedule and wording that applied when the damage happened.
- Identify the policy section. Work out whether the affected item falls under buildings, contents or another section.
- Check the cover and definition. Confirm that accidental damage was included or added for that section. Look for definitions or requirements involving “accidental,” “sudden,” “breakage” or “external force.”
- Read the exclusions. Pay particular attention to wording about wear and tear, gradual damage, deliberate acts and defective workmanship.
- Document what happened. Record when the damage occurred, if known, and when it was first noticed; take photographs and retain relevant reports or communications.
- Ask the insurer to explain its decision. Ask which policy term or exclusion it applied and how that applies to the evidence about the cause and timing.
- Use the complaint route if you disagree. Make a complaint to the insurer first. If the issue remains unresolved, the FOS explains how it assesses home-insurance complaints and what evidence it may consider. Its guidance cannot determine the outcome of an individual claim in advance.
The FOS considers the cover a customer had, the applicable definition and exclusions, what happened and the available evidence. A general guide cannot establish whether a particular claim should be paid.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




