PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchFor everyday purchases in India, neither UPI nor a debit card has one universal all-in cost or limit that applies to every customer. NPCI’s UPI FAQ gives an ordinary ceiling of up to ₹1 lakh per transaction, but banks can apply lower internal limits and special higher ceilings are limited to specified categories and eligible merchants. Debit-card purchase limits and issuer fees depend on the bank and card. If a payment is unauthorised, RBI customer-liability rules turn on what caused the loss and how quickly it is reported—not simply on which payment method was used.
Choose based on the merchant’s options, your bank’s current limits and fees, and how you want to authorise the payment. For either method, report suspected fraud to your bank promptly through official channels.
As an Amazon Associate I earn from qualifying purchases.
UPI vs debit cards: how the payment is authorised
Both methods can draw on a bank account, but they take different routes and ask you to approve the payment differently. That distinction matters when checking a limit, deciding what details to protect, or reporting a problem.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →UPI moves money between bank accounts
The National Payments Corporation of India (NPCI) describes UPI as an instant payment system built over IMPS infrastructure. A UPI app lets you initiate a bank-account payment, and your UPI PIN authorises the bank transaction. The PIN is sensitive: NPCI warns users not to share it. A payment can be made only where the merchant supports UPI and the relevant app, account and bank are functioning.
#1 Best Overall
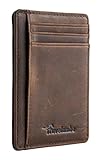
- Super Minimalist & Slim: Only 0.12" thick, sizing 3.1" x 4.4" x 0.12" extremely convenient to be carried around in your front or back pocket
- RFID Blocking Tested & Approved by Independent Lab Tests: Our wallets have been tested for 13.56 mhz frequency in which our credit cards, debit cards, driver license and id cards operate. please be noted that the signal of some id badge, access cards and hotel room cards which operates in 142 khz, can not be blocked by this wallet
- Enhances Personal Security: We leverage top rfid technology to block rfid signals used to electronically scan your wallet as someone passes by unnoticed. this keeps your vital information in driver license, debit cards and credit cards from being stolen
- Functionality: Our rfid wallet not only offers security, it's also very functional. it features 6 card slots for you to place your most frequently used cards
- Hand Made: Handcrafted with care, our Travelambo wallet preserves leather's natural softness and shape, made by skilled artisans using traditional tools
UPI payments are not the same as card payments merely made through a phone. The payment instruction is a bank-account transaction through UPI. This is why a UPI transaction limit, an app’s own controls and your bank’s internal controls can all be relevant.
A debit card uses the issuer’s card arrangement
A debit card authorises a purchase against the account linked to the card through the card-payment process. The issuing bank sets the terms and may provide controls for transactions or channels. The evidence here does not establish one national debit-card purchase ceiling or a single fee schedule, so the number that matters is the one for your specific bank account and card.
At checkout, merchant acceptance also matters: a shop may accept one method and not the other, or offer both. If a transaction is declined, check the issuer’s or app’s controls and available balance as well as the merchant’s acceptance; a published ceiling alone does not guarantee that a particular payment will go through.
Free tools Windows power users keep installed
One-click scans. No signup required.
What the UPI limit means—and what it does not
NPCI’s UPI FAQ states that the limit for a normal UPI transaction is up to ₹1 lakh per transaction. The FAQ page’s publication date is not stated in the retrieved material, so treat that as the ordinary limit stated by the FAQ and confirm the current rule in your bank or app before relying on it for a particular payment.
Rank #2

- Slim, Stylish & Ultra Portable: Designed for modern minimalists, our slim wallets for men and women measure only 4.5" x 3.16". Its minimalist profile slides easily into your front pocket, purse, or travel bag—perfect for those who value convenience without sacrificing style
- Large Capacity: Despite its thin shape, this minimalist RFID front pocket wallet features 8 card slots. This card case securely holds your credit cards, driver’s license, debit cards, and IDs, keeping your essentials neatly organized and always within easy reach
- RFID Blocking Security: Outfitted with advanced RFID blocking technology to help shield against electronic scanning and protect your personal information while you travel, shop, or commute
- Durable & Modern: Crafted from premium microfiber leather with fine stitching, this luxurious card holder wallet combines refined style with lasting strength. Designed to withstand everyday use while maintaining its sleek, modern look—perfect for travel, work, shop and more
- Perfect Unisex Gift Idea: A stylish and practical gift for men and women alike. With its versatile design, this RFID wallet is perfect for birthdays, holidays, anniversaries, or any occasion for the traveler, professional, or minimalist in your life
“Up to” is important. It is a ceiling, not a promise that each user can send ₹1 lakh in one payment. NPCI’s circular dated 28 August 2025 says that enhanced limits apply to verified merchants in selected categories, while member banks may set their own internal limits within NPCI ceilings. P2P payments continue under existing guidance; the special merchant-category ceilings should not be applied to an ordinary person-to-person transfer. The circular excerpt available here does not provide the specific enhanced category amounts, so no higher figure should be assumed from the ordinary limit.
- Transaction type: The ordinary FAQ figure and selected higher merchant-category ceilings are not interchangeable.
- Bank rules: A bank may set an internal cap below the NPCI ceiling.
- App or account controls: A user-facing app or account setting may further affect what can be sent.
- Payment context: Eligibility for a higher category limit depends on the category and verified-merchant conditions; it is not a general increase for every UPI payment.
For a large purchase, check the payment type, the current app and bank limits, and the merchant’s eligibility before reaching checkout. If your bank’s limit is lower than the amount due, the NPCI ceiling does not override it.
Debit-card limits are issuer-specific
The sources establish no single nationwide debit-card purchase limit or daily purchase cap. A card’s applicable limit is set through the issuer’s terms and controls, and may depend on the account or card. Do not use a limit reported for another bank’s card as a national standard.
Before a planned large purchase, open your bank’s current card controls or fee and service schedule. Confirm the limit for the type of transaction you intend to make and whether any change takes effect immediately. If the available control is unclear, ask the bank through an official channel rather than assuming an ATM withdrawal limit, online-payment setting or contactless setting is also the in-store purchase limit.
Rank #3

- STYLISHLY SMALL, SLIM & DISCREET: Measuring just 3 1/8" x 4 7/16", our RFID front pocket wallet is designed to be super thin and exceptionally slim. Its modern, minimalist profile fits perfectly in your pocket, purse, or travel pack without adding bulk.
- SURPRISINGLY SPACIOUS: Though slim, it features 8 slots to easily organize your essentials. Comfortably holds your driver's license, credit cards, debit cards, and membership cards, keeping everything you need right at your fingertips.
- ADVANCED RFID BLOCKING: Our slim wallets for men and women are outfitted with advanced RFID SECURE Technology. They block electronic signals to keep your identity protected while you travel, shop, or explore, safeguarding you from digital theft.
- DURABLE & STYLISH FAUX LEATHER: Crafted from premium synthetic leather, this minimalist wallet sleeve combines a luxurious look and feel with everyday functionality. Its durable construction is designed to withstand the rigors of daily use, travel, and shopping.
- THE PERFECT UNISEX GIFT: With its sleek design and practical security features, this wallet is a popular choice for both men and women. It arrives ready for gifting, making it an ideal present for the frequent traveler, minimalist, or anyone in your life!
Fees: separate merchant charges from bank fees
There is no support for a blanket claim that every UPI payment is free in every arrangement, nor for one universal debit-card fee. The customer’s possible costs depend on the payment arrangement, merchant checkout and bank terms.
UPI charges
NPCI’s FAQ says customers pay no charge for the particular PPI-on-UPI transactions described there. That statement is limited to those transactions; it does not establish that every UPI payment, account, merchant service or related arrangement is free of any possible charge. Read the amount and any fee shown in the app or at checkout before authorising payment.
Debit-card MDR is not the same as every card-related fee
RBI guidance says payment gateways and payment aggregators must not pass debit-card merchant discount rate (MDR) to customers. That narrow rule should not be confused with the issuer’s separate charges or with every possible checkout fee. RBI guidance also says other charges, such as a convenience fee, must be disclosed before payment.
A bank may have separate terms for card issuance, annual charges, replacement charges or account conditions. Check the current schedule for your own account and card; do not infer that the merchant’s MDR rule removes those issuer charges. Likewise, a disclosed convenience fee is a separate checkout charge, not the same thing as MDR.
Rank #4

- Ultra Slim and RFID Blocking Wallet: This thin card wallet is equipped with advanced RFID blocking technology. It protects your valuable information like ID and credit cards from unauthorized scans. It also allows you to bring it along in your handbag, backpack, front pocket, or purse
- Functional Front Pocket Wallet: Despite its thin design, this credit card holder has ample space to store your cards: 6 card slots, 1 ID window for easy access to your driver's license or ID card, and 1 side compartment for cash / currency
- Credit Card Holder: Ultra-slim and lightweight, at just 4.4" x 3.14" x 0.11" and 1.05 oz, our card holder is crafted from premium lychee leather. It's the minimalist's choice for carrying essential cards with ease, and it adds no bulk to your pocket or purse
- Front Pocket Design: This slim women's card holder is designed for everyday use. Whether you’re shopping, traveling, or heading to the office, this card holder perfectly adapts to your lifestyle
- Perfect Gifts: This credit card holder with exquisite clear box makes a perfect gift for your loved ones on their Birthday, Anniversary, Mother’s Day, Valentine’s Day or Christmas. It’s the best choice for travel, dating, working, shopping, exploring or daily use, etc
Compare the actual checkout, not a shorthand claim
When deciding which method costs less for one purchase, inspect the final amount for each available option and check whether the bank applies a relevant account or card charge. A fee displayed by a merchant, a bank fee and a payment-network charge are not interchangeable labels. If a charge is unclear, ask the merchant or bank what it covers before completing the transaction.
At a glance: which differences matter?
| Question | UPI | Debit card |
|---|---|---|
| Where the payment draws from | Bank account through UPI, an instant system built over IMPS infrastructure. | Account linked to the debit card, under the issuing bank’s card terms. |
| How the customer authorises | UPI PIN authorises the bank transaction; NPCI says not to share it. | Authorisation and available controls depend on the card and issuer. |
| Published ordinary purchase limit | NPCI FAQ: up to ₹1 lakh per normal transaction; bank internal limits can be lower. | No single nationwide purchase cap established; check the issuer’s current limit. |
| Higher limits | NPCI’s 28 August 2025 circular covers selected categories and verified merchants; banks may set lower internal limits. It does not make special merchant limits general P2P limits. | Issuer-specific limits and controls; check the current card terms. |
| Customer charges | NPCI’s no-charge statement applies to the particular PPI-on-UPI transactions it describes, not every arrangement. | RBI guidance bars passing debit-card MDR to customers; disclosed convenience fees and separate issuer fees are distinct questions. |
| Problem or suspected fraud | Raise or track a grievance through the participating bank’s UPI app; report suspected fraud to the bank. An initiated UPI payment cannot be stopped. | Contact the issuing bank promptly through official channels and preserve the transaction details. |
The table describes rules and source-backed distinctions, not a guarantee of acceptance or successful authorisation at every shop. Your account, bank, app, card and merchant can change the practical outcome.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What to do if a payment is wrong, unauthorised or missing
Do not wait to see whether a suspicious transaction resolves itself. Notify your bank promptly: under RBI’s customer-liability framework, reporting time and the cause of the loss affect the outcome. Use contact details in the official bank app, on the bank’s own site or on your card—not a number sent by an unsolicited caller or message.
For a UPI payment
- Record the transaction details. Keep the date, amount, recipient or merchant information, transaction reference and any app status or message.
- Contact your participating bank through an official channel. NPCI directs users to the bank for suspected fraudulent or unidentified transactions. Tell the bank whether you made the payment, authorised it, or do not recognise it.
- Raise or track the UPI grievance in the participating bank’s UPI app. NPCI’s FAQ points users to that route. Keep the complaint number and any response.
- Use NPCI’s complaint portal as a routing channel when appropriate. NPCI says it passes complaints to the relevant member, which is responsible for resolution. For suspected fraud, the bank remains the first point of contact.
An initiated UPI payment cannot be stopped, according to NPCI’s FAQ. That makes it especially important to check the recipient and amount before approving and to report a mistaken or unauthorised transaction as soon as you identify it. Do not share your UPI PIN with anyone claiming they need it to reverse or investigate a payment.
Best Value

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
For a debit-card transaction
- Contact the card-issuing bank immediately. Report the transaction as unauthorised or disputed and ask what steps are needed to secure the card and account.
- Follow the bank’s instructions for access and card controls. Use official bank channels to ask about blocking or restricting the card, and whether further action is needed on the account.
- Save evidence and the complaint reference. Keep the transaction entry, date, amount, merchant name as shown by the bank, messages and complaint number.
- Ask the bank to explain the applicable liability and resolution timeline. The result depends on the facts, reporting time and current rules; do not assume that a disputed transaction will be automatically reimbursed.
How RBI’s unauthorised-transaction framework affects liability
RBI directions on customer liability for unauthorised electronic banking transactions distinguish among bank-side deficiency, a third-party breach and customer negligence. The applicable result depends on which situation fits and when the customer reports the transaction after receiving the bank’s communication.
- Bank-side deficiency: The directions provide zero-liability cases where the loss is attributable to the bank’s deficiency.
- Third-party breach: Certain third-party breaches can fall within zero-liability treatment when reported promptly under the directions.
- Customer negligence: If a customer shares credentials, the directions say the customer bears the loss up to the time of reporting.
The directions cited are dated 6 July 2017. They also specify a shadow reversal within 10 working days after notification in covered zero- or limited-liability cases, and resolution within the bank’s policy timeline, not exceeding 90 days under those directions. These are details of the cited framework, not a blanket promise that every disputed payment will be reversed on that schedule. Applicability and amendments should be confirmed with the bank and current RBI directions.
When reporting, describe exactly what happened, including whether you shared a PIN, password, one-time password or other credential. Do not omit a relevant fact: the distinction between a third-party breach and customer negligence can affect the liability assessment. Ask the bank to identify the rule and timeline it is applying to your case.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitchesPractical choice for everyday purchases
Check UPI first when its bank-account route and merchant support suit the purchase
UPI can be a straightforward option where the merchant accepts it and your account, app and bank allow the amount. For an unusually large transaction, verify the applicable ordinary or category limit and bank cap rather than assuming the published ceiling is available to you. Confirm the recipient and amount before entering the PIN.
Use a debit card when card acceptance or issuer controls suit the purchase
A debit card is a practical alternative where it is accepted and its current issuer terms fit your needs. Check the bank’s card-specific purchase limits and any relevant fees, especially before a large purchase or when your card has transaction controls enabled.
For either method, make the decision at checkout
- Confirm that the merchant accepts the method and that the displayed recipient or merchant is correct.
- Check the final amount and any disclosed convenience fee before authorising.
- Use only your own secure device and never disclose a UPI PIN or card credentials to someone who contacts you.
- Save the transaction reference or receipt until the purchase is settled.
- If anything looks unfamiliar, pause and contact the bank or merchant using an official channel.
Neither the UPI ceiling nor a card’s acceptance guarantees that a payment will be authorised. The most useful comparison is the actual transaction you are about to make: its amount, merchant, applicable bank limit, displayed fee and the payment route you can securely use.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




