Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →If you need to send money to someone’s bank account, use IMPS when speed matters or NEFT when batch processing is acceptable. If you are paying a shop or online seller, a debit or credit card may fit better. These options do different jobs: IMPS and NEFT move money between bank accounts, while cards are primarily merchant-payment instruments.
Before choosing, check the recipient or merchant, the bank’s channel limits and charges, and how quickly the payment needs to arrive. The guidance below reflects the cited official service information; bank, channel and card terms can vary.
As an Amazon Associate I earn from qualifying purchases.
The practical question is not simply “Which method is fastest?” It is first “Where does the payment need to go?” Then consider timing, amount, cost, verification and what to do if the payment does not complete as expected. That approach helps avoid treating a merchant card payment as though it were a bank transfer—or assuming that every bank applies the same limits and fees.
Recommended Free Tools
Choose by payment job, not just by speed
Start by identifying where the money needs to go. A bank transfer sends funds to a beneficiary’s bank account. A card payment is made to a merchant through card acceptance channels. A card is therefore not a direct substitute for an account-to-account transfer, even if both can be used to pay someone in some contexts.
#1 Best Overall
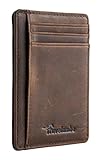
- Super Minimalist & Slim: Only 0.12" thick, sizing 3.1" x 4.4" x 0.12" extremely convenient to be carried around in your front or back pocket
- RFID Blocking Tested & Approved by Independent Lab Tests: Our wallets have been tested for 13.56 mhz frequency in which our credit cards, debit cards, driver license and id cards operate. please be noted that the signal of some id badge, access cards and hotel room cards which operates in 142 khz, can not be blocked by this wallet
- Enhances Personal Security: We leverage top rfid technology to block rfid signals used to electronically scan your wallet as someone passes by unnoticed. this keeps your vital information in driver license, debit cards and credit cards from being stolen
- Functionality: Our rfid wallet not only offers security, it's also very functional. it features 6 card slots for you to place your most frequently used cards
- Hand Made: Handcrafted with care, our Travelambo wallet preserves leather's natural softness and shape, made by skilled artisans using traditional tools
- Sending to a bank account: consider IMPS for a real-time transfer or NEFT if half-hourly batch processing is acceptable.
- Paying a merchant: consider a debit or credit card if the merchant accepts it and the card’s terms suit the purchase.
- Paying in person without connectivity: check whether you and the merchant have an eligible offline payment instrument enabled.
For example, if you are paying a person who has given you bank-account details, compare IMPS and NEFT. If you are checking out on a merchant’s website or paying at a shop, first look at the methods the merchant accepts; a card may be appropriate there, but it is not simply another way to route money into any beneficiary account. If your phone or payment location has no internet or telecom connectivity, the offline-payment framework is relevant only if the instrument and provider support that use and the user has opted in.
This distinction also keeps the comparison fair. IMPS and NEFT are transfer systems, so their central questions are how quickly funds are expected to reach the beneficiary, what amount the bank and channel allow, and how to verify the destination. For cards, the key questions are whether the merchant accepts the card and whether the issuer’s terms and any transaction-specific charges make it suitable. There is no single ranking that covers all these jobs.
IMPS: use it when an account transfer is urgent
NPCI describes IMPS as a real-time payment service available around the clock, including holidays. That makes it the clearest fit among these options when the recipient needs an account transfer promptly. NPCI’s IMPS overview states a per-transaction limit of ₹5 lakh for all channels except SMS and IVR. The limit that applies to your transaction may be lower or otherwise channel-specific, so verify it with your bank before sending.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsIn practical terms, “real time” is the reason to consider IMPS when waiting for a batch is undesirable. Its round-the-clock availability means the service is not described as limited to ordinary banking hours, and its availability includes holidays. Still, service availability does not mean every bank, account or channel will necessarily let you send the amount you want at that moment. Bank rules and channel-specific conditions remain important.
The ₹5 lakh figure is the NPCI-stated per-transaction limit for most channels, not a guarantee that any customer can make a ₹5 lakh payment through every app or account. SMS and IVR are explicitly exceptions to that headline limit, and your bank may have its own applicable limits or controls. For a large or time-sensitive transfer, check the limit shown by the bank before you rely on IMPS. If the app or channel will not allow the amount, do not assume that switching to a different channel automatically removes the restriction; confirm the bank’s rules.
Check the channel, fee and beneficiary details
Do not assume that every bank offers the same IMPS limit, supported channel or charge. Check your bank’s current tariff and the limit shown in the app or other channel you intend to use. Enter the beneficiary details carefully and review the displayed recipient name, where available, before confirming.
Make the checks in the same channel you plan to use, since the applicable cap and terms can depend on that channel. A fee should also be checked against the bank’s current tariff rather than inferred from another bank’s offer or from a general comparison. No universal IMPS fee is stated here, so treat a bank’s displayed charge or tariff as the relevant information for your own transfer.
Rank #2

- Slim, Stylish & Ultra Portable: Designed for modern minimalists, our slim wallets for men and women measure only 4.5" x 3.16". Its minimalist profile slides easily into your front pocket, purse, or travel bag—perfect for those who value convenience without sacrificing style
- Large Capacity: Despite its thin shape, this minimalist RFID front pocket wallet features 8 card slots. This card case securely holds your credit cards, driver’s license, debit cards, and IDs, keeping your essentials neatly organized and always within easy reach
- RFID Blocking Security: Outfitted with advanced RFID blocking technology to help shield against electronic scanning and protect your personal information while you travel, shop, or commute
- Durable & Modern: Crafted from premium microfiber leather with fine stitching, this luxurious card holder wallet combines refined style with lasting strength. Designed to withstand everyday use while maintaining its sleek, modern look—perfect for travel, work, shop and more
- Perfect Unisex Gift Idea: A stylish and practical gift for men and women alike. With its versatile design, this RFID wallet is perfect for birthdays, holidays, anniversaries, or any occasion for the traveler, professional, or minimalist in your life
Recipient verification matters even when speed is the priority. A real-time service can move a payment promptly, but speed does not make an incorrectly entered destination safer. Review the details before authorizing the transaction, use any available recipient-name display as a check, and independently verify the beneficiary’s information. If you are unsure, pause and confirm with the intended recipient rather than sending first and trying to correct it later.
NEFT: choose it when batch processing is acceptable
NEFT is a bank-transfer system that operates 24×7, every day of the year. It is not restricted to banking hours. The Reserve Bank of India says the system processes transfers in 48 half-hourly batches. A beneficiary credit is expected within two hours of the relevant batch settlement, so NEFT is not necessarily instant. See the RBI’s NEFT FAQ for the operating model and system rules.
The batch model is the key comparison with IMPS. NEFT is available at night, on weekends and on holidays, but the transfer is processed through a sequence of half-hourly settlements rather than being described as real time. The two-hour beneficiary-credit expectation is measured from the relevant batch settlement. It is not a promise that every transfer will be credited immediately after you press send, and it should not be rewritten as “NEFT only works during banking hours.”
That makes NEFT a reasonable option when the amount is being transferred to a bank account and the batch-based timing is acceptable. If a recipient needs funds urgently, the difference between real-time service and a batch-based process may matter; check the current status and timing offered by your bank rather than assuming the transfer will be instant. If a payment can tolerate the NEFT processing model, round-the-clock operation means you need not wait for the next working day simply because it is outside standard banking hours.
Limits and charges depend partly on your bank
The RBI sets no minimum or maximum amount per NEFT transaction at the system level. That does not guarantee an unlimited transfer through an individual bank app: banks may set channel, risk or account limits. Check the applicable limit before initiating a large payment.
This distinction is particularly important for readers searching for the maximum NEFT amount. There is no RBI-set single-transaction floor or ceiling for NEFT itself, but that system rule does not erase the limits a bank may apply in its app, at a branch or through another channel. A bank may also apply risk controls. Therefore, “NEFT has no RBI-set maximum” is accurate; “you can send any amount from every bank app” is not.
RBI guidance says online NEFT transfers from savings bank accounts are free. That policy should not be generalized to branch transactions, other account types or every channel. Check your bank’s current tariff for the transfer method and account you will use.
Rank #3

- STYLISHLY SMALL, SLIM & DISCREET: Measuring just 3 1/8" x 4 7/16", our RFID front pocket wallet is designed to be super thin and exceptionally slim. Its modern, minimalist profile fits perfectly in your pocket, purse, or travel pack without adding bulk.
- SURPRISINGLY SPACIOUS: Though slim, it features 8 slots to easily organize your essentials. Comfortably holds your driver's license, credit cards, debit cards, and membership cards, keeping everything you need right at your fingertips.
- ADVANCED RFID BLOCKING: Our slim wallets for men and women are outfitted with advanced RFID SECURE Technology. They block electronic signals to keep your identity protected while you travel, shop, or explore, safeguarding you from digital theft.
- DURABLE & STYLISH FAUX LEATHER: Crafted from premium synthetic leather, this minimalist wallet sleeve combines a luxurious look and feel with everyday functionality. Its durable construction is designed to withstand the rigors of daily use, travel, and shopping.
- THE PERFECT UNISEX GIFT: With its sleek design and practical security features, this wallet is a popular choice for both men and women. It arrives ready for gifting, making it an ideal present for the frequent traveler, minimalist, or anyone in your life!
When comparing costs, identify both the account type and how you will initiate the transfer. The free-online-transfer guidance specifically refers to online NEFT transfers by savings bank account holders. It does not establish that branch-assisted NEFT, other account types, or every other transfer service is free. Nor does it set a universal IMPS fee. The safest comparison is to check the tariff for the exact bank, account and channel you intend to use before confirming.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Cards: use them for merchants, subject to acceptance and terms
Debit and credit cards are generally used to pay merchants, rather than to transfer money directly into a beneficiary’s bank account. A card is a sensible option for an online purchase or an in-store payment when the merchant accepts it. Whether it is preferable depends on the merchant’s available payment methods and your card’s issuer terms.
Think of a card decision as a merchant checkout decision, not an account-transfer decision. The merchant must accept the card through the relevant channel. The issuer’s terms and the details of the transaction affect whether the card suits you. If the person you are paying needs money credited to a bank account, use a transfer option designed for that task rather than assuming that a card payment can do the same job.
- Confirm the merchant accepts the card and check for any transaction-specific fee before paying.
- For a credit card, consider the cost of carrying a balance and the issuer’s applicable terms; for a debit card, consider the linked account and transaction conditions.
- Do not assume a particular rewards rate, fee, protection or acceptance level applies universally. These vary by card, issuer, merchant and transaction.
A comparison should therefore avoid claims such as “cards are always cheaper,” “credit cards always earn a particular reward,” or “every merchant accepts cards.” The information here does not establish issuer-specific rates, card fees, protections or acceptance. Check the terms for the card you hold and the checkout information for the merchant. A purchase’s convenience is not the only consideration if the card has a cost or if the terms of a credit balance matter to you.
RBI’s framework also permits opted-in offline proximity payments using cards and other instruments within specified small-value limits. This is a specialized offline use, not a general claim that every card works without connectivity. The framework defines an offline payment as one that does not require internet or telecom connectivity to take effect. See the RBI offline payments framework.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOffline proximity payments are distinct from an ordinary card transaction that depends on connectivity. The framework concerns eligible instruments and opted-in use within limits; it does not mean that a physical card will work offline at any shop or that all cardholders have the feature. Check the provider’s availability and the instrument’s rules before relying on it, especially if connectivity is likely to be absent.
Small in-person payments without connectivity
For eligible offline payment instruments, the general limit under the RBI framework is ₹500 per transaction and ₹2,000 stored total. UPI Lite has enhanced limits of ₹1,000 per transaction and ₹5,000 total. These are framework limits, not a guarantee that every bank, provider or instrument offers offline payments to every customer. Availability depends on the provider and instrument, and the user must have opted in.
Rank #4

- Ultra Slim and RFID Blocking Wallet: This thin card wallet is equipped with advanced RFID blocking technology. It protects your valuable information like ID and credit cards from unauthorized scans. It also allows you to bring it along in your handbag, backpack, front pocket, or purse
- Functional Front Pocket Wallet: Despite its thin design, this credit card holder has ample space to store your cards: 6 card slots, 1 ID window for easy access to your driver's license or ID card, and 1 side compartment for cash / currency
- Credit Card Holder: Ultra-slim and lightweight, at just 4.4" x 3.14" x 0.11" and 1.05 oz, our card holder is crafted from premium lychee leather. It's the minimalist's choice for carrying essential cards with ease, and it adds no bulk to your pocket or purse
- Front Pocket Design: This slim women's card holder is designed for everyday use. Whether you’re shopping, traveling, or heading to the office, this card holder perfectly adapts to your lifestyle
- Perfect Gifts: This credit card holder with exquisite clear box makes a perfect gift for your loved ones on their Birthday, Anniversary, Mother’s Day, Valentine’s Day or Christmas. It’s the best choice for travel, dating, working, shopping, exploring or daily use, etc
There are two figures to keep separate: the amount of a single offline payment and the total stored-value limit. Under the general framework, an offline transaction is limited to ₹500 and the instrument’s stored total is limited to ₹2,000. UPI Lite has separately stated enhanced limits of ₹1,000 per transaction and ₹5,000 total. Do not mix the UPI Lite figures with the general offline limits, or assume that the enhanced limits apply to every instrument.
These limits make the offline framework relevant to small in-person purchases, not a substitute for an unrestricted transfer to another bank account. The user must have opted in, and the provider and instrument must support the feature. If either side cannot use an eligible method, the framework limits alone do not make the payment possible. Confirm availability and the rules before you are in a situation where there is no connectivity.
Free tools Windows power users keep installed
One-click scans. No signup required.
Compare the options against your situation
| Your situation | Relevant option | Why it fits | What to check |
|---|---|---|---|
| Urgent bank-to-bank transfer | IMPS | NPCI describes it as real time and available 24×7, including holidays. | Bank and channel limit, fee, availability and beneficiary details. The NPCI stated ₹5 lakh limit excludes SMS and IVR channels. |
| Bank transfer where half-hourly batch processing is acceptable | NEFT | Runs 24×7 in 48 half-hourly batches, with beneficiary credit expected within two hours of relevant batch settlement. | Bank-specific channel limits and any applicable tariff. No RBI-set single-transaction floor or ceiling does not mean every bank channel is uncapped. |
| Online or in-store merchant payment | Debit or credit card | Cards are designed primarily for merchant payments and may be accepted through card channels. | Merchant acceptance, transaction fees and issuer terms. These vary by card and transaction. |
| Small in-person payment with no internet or telecom connectivity | Eligible offline payment instrument | RBI’s framework allows opted-in offline proximity payments. | Provider and instrument availability, opt-in status, and the applicable transaction and stored-value limits. |
The table is a starting point, not a claim that one method wins in every case. For a person-to-person bank transfer, urgency points toward IMPS and tolerance for batch processing makes NEFT relevant. For a shop or online seller, card acceptance and terms are decisive. For an offline small-value proximity payment, the instrument and opt-in status determine whether the framework applies. If the payment does not fit one of these situations, check the bank or provider’s actual service terms rather than extrapolating from the comparison.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Verify the recipient and know what to do if a payment fails
RBI directed a no-charge bank-account name lookup facility for NEFT and RTGS, comparable to recipient-name checks already available in UPI and IMPS. Use the displayed recipient name as a check, and independently verify the beneficiary’s account details before confirming; a name lookup does not replace careful entry of the payment details. See the RBI’s account-name lookup direction.
Use the name lookup as an additional verification step, not as a substitute for checking the account details through a trusted source. If the displayed name does not match what you expect, pause and confirm the destination before proceeding. Recipient checks are useful for reducing the chance of sending money to the wrong beneficiary, but the responsibility to review and confirm the payment remains with you.
If your account is debited but the beneficiary is not credited, keep the transaction reference and contact your sending bank or payment provider. RBI’s failed-transaction framework says certain domestic IMPS and UPI account-transfer failures should be auto-reversed by T+1; a delay beyond the prescribed timeline can trigger compensation of ₹100 per day. Merchant-payment failures follow different timelines, so do not assume the account-transfer rule applies to a card or other merchant transaction. Consult the RBI failed-transaction framework for the relevant transaction category.
The words “certain” and “prescribed timeline” matter: the rule is not a guarantee that every debit will be reversed immediately or that every payment type follows the same clock. If a transfer appears incomplete, preserve the reference and report the issue to the sending bank or payment provider. Distinguish an account-transfer failure from a merchant-payment failure when describing the problem, because RBI’s framework lists different timelines for those categories. Do not apply the IMPS/UPI account-transfer T+1 rule to a card purchase without checking the relevant merchant-transaction rule.
Best Value

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
A simple decision checklist
- Is the recipient a person or a merchant? For an account beneficiary, use a transfer rail; for a shop or online seller, consider a card if accepted.
- For an account transfer, how urgent is it? Choose IMPS when real-time service matters; choose NEFT if half-hourly processing and the stated credit expectation suit your timing.
- Will your bank allow the amount through this channel? Check the app or bank’s current terms, especially for large transfers and channel-specific limits.
- What will it cost? Check the current tariff. RBI guidance makes online NEFT transfers from savings accounts free, but that does not establish charges for every other channel or option.
- Have you verified the destination? Review the recipient name where available and confirm the beneficiary or merchant details independently before authorizing payment.
For a final check, match the choice to the job rather than selecting by brand or habit. If you need a prompt bank-account transfer, confirm that IMPS is available to you and that your bank allows the amount. If the transfer can use NEFT’s batch process, check the applicable bank limit and tariff, then allow for the batch-based credit expectation. If you are paying a merchant, confirm acceptance and look at the particular card’s terms. If you expect to be offline, confirm the eligible instrument, opt-in status and small-value limits in advance.
There is no need to assume that one option replaces UPI in every situation. The useful alternative depends on whether you are transferring to a bank account, paying a merchant, or making an eligible small in-person payment without connectivity. Checking destination, timing, bank or issuer terms and applicable limits before confirming is more reliable than relying on a generic claim about speed or cost.
Frequently Asked Questions
Is NEFT available at night, on weekends and on holidays?
Yes. RBI says NEFT operates 24×7 every day of the year. It processes transfers in 48 half-hourly batches, so round-the-clock availability does not mean each payment is credited instantly. Beneficiary credit is expected within two hours of the relevant batch settlement.
Is IMPS instant, and is it available 24×7?
NPCI describes IMPS as a real-time service available around the clock, including holidays. The applicable amount limit and channel availability can still depend on your bank. NPCI states a ₹5 lakh per-transaction limit for all channels except SMS and IVR; check your bank for the limit that applies to your channel.
What is the maximum amount I can send through NEFT?
RBI sets no minimum or maximum amount per NEFT transaction at the system level. Your bank may still set limits through its app, account, channel or risk controls, so check the applicable limit before sending a large amount.
Is NEFT free in India?
RBI guidance says online NEFT transfers from savings bank accounts are free. Do not assume that this covers branch transactions, other account types or every channel. Check your bank’s current tariff for your specific transfer.
Can I use a debit or credit card to send money to someone’s bank account?
Cards are primarily merchant-payment instruments and are not direct substitutes for account-to-account transfer rails. Use IMPS or NEFT when the task is sending money to a beneficiary’s bank account; use a card for a merchant if it is accepted and the card’s terms suit the purchase.
What are the limits for offline payments without internet or telecom connectivity?
Under RBI’s general offline framework, the limit is ₹500 per transaction and ₹2,000 stored total. UPI Lite has enhanced limits of ₹1,000 per transaction and ₹5,000 total. Availability depends on the provider and instrument, and the user must have opted in.
What should I do if my account is debited but the recipient is not credited?
Keep the transaction reference and contact your sending bank or payment provider. RBI’s framework says certain domestic IMPS and UPI account-transfer failures should be auto-reversed by T+1; a delay beyond the prescribed timeline can trigger ₹100 per day compensation. Merchant-payment failures have different timelines, so confirm which transaction category applies.
The Bottom Line
Use IMPS when a bank-account transfer is urgent, NEFT when its 24×7 half-hourly batch process is acceptable, and a debit or credit card when paying a merchant that accepts it. Check your bank’s actual channel limit and tariff, verify the destination, and do not treat a card as a direct replacement for an account transfer. Offline payments are a separate, opted-in small-value use with provider-dependent availability and specified limits.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →



