Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Probably not. DICGC’s 2025 directions list balances held in FCNR accounts among items excluded from the base used to calculate insured banks’ deposit-insurance premiums. That is strong evidence that FCNR(B) balances are not covered, even at a bank that participates in DICGC. However, DICGC’s public consumer guide does not expressly say that FCNR(B) deposits are uninsured, so this conclusion should be understood as an inference from its specific premium-reporting treatment—not as a verbatim consumer-facing ruling. A promotional or “special” interest rate does not, by itself, establish an insurance exception.
Why FCNR(B) insurance is uncertain
FCNR(B) stands for Foreign Currency Non-Resident (Bank). The Reserve Bank of India treats it as a distinct foreign-currency deposit arrangement in its Master Directions – Interest Rate on Deposits.


DICGC’s general consumer guide says it insures deposits such as savings, fixed, current and recurring deposits, subject to exclusions. Its guide does not expressly name FCNR(B) deposits in that list. But DICGC’s 2025 Master Directions specifically include “Balance held in FCNR Account” among items excluded from the premium calculation framework for insured banks. Because that direction concerns the premium base rather than a direct consumer eligibility ruling, it is most accurate to say that the official treatment strongly indicates FCNR(B) balances are outside DICGC cover.
Does a special rate change the answer?
No evidence in DICGC’s cited guidance establishes that a special, promotional or unusually high interest rate creates an exception to the treatment of FCNR balances. The interest rate and the deposit’s insurance classification are separate issues: a rate offer does not establish that the balance qualifies for DICGC protection.
#1 Best Overall
For a specific offer, ask the bank to identify the exact account classification and confirm in writing whether the balance is treated as an FCNR(B) deposit. If the answer remains unclear, ask DICGC whether that precise classification is covered. Do not rely on an advertised rate, the word “deposit,” or the bank’s scheme membership as proof of product-level eligibility.
Why the ₹5 lakh limit may not protect an FCNR(B) balance
DICGC’s public guide states a maximum of ₹5,00,000 per depositor per bank for eligible deposits, including principal and interest, when held in the same right and capacity. Eligible accounts at the same bank are aggregated across its branches. This is a ceiling for deposits that qualify; it does not make an otherwise excluded category eligible.
Rank #2
Bank participation and product coverage are therefore separate questions. A bank’s DICGC-insured status does not, on its own, establish that every kind of balance it accepts is insured. DICGC’s general limit and exclusions are set out in its Guide to Deposit Insurance.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What to verify before booking an FCNR(B) offer
- Issuing bank: Confirm which bank accepts the deposit and whether it participates in DICGC.
- Account classification: Ask whether the specific product is booked as an FCNR(B) account or under another deposit category.
- Booking location and terms: Confirm where the account is booked and review the product’s written terms; do not infer insurance treatment from the marketing name.
- Coverage confirmation: Request the bank’s written explanation and, if needed, ask DICGC about the exact classification.
DICGC’s 2025 directions list FCNR account balances as an excluded premium-base item; the reviewed DICGC sources do not state a separate numeric insured limit for FCNR(B) balances.
Recommended Free Tools
Quick Recap
Best Value
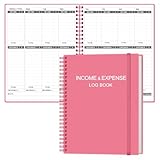
- EASY TO MANAGE - Use this income & expense log book to record your income and expenses each day.Keep your budget in balance, and develop good bookkeeping habits to meet your financial goals
- ACCOUNTING FOR THE WHOLE YEAR - This account ledger notebook is undated and is used to lasts a whole year.The keeping log has 1 page Year Overview, 53 weekly spreads, 2 pages annual summary, 10 notes pages, to track weekly and yearly income & expenses
- HIGH QUALITY - The accounting bookkeeping tracking ledger log book is used to high quality 100gsm pure white paper, teal elastic band and a back pocket for extra space. Make sure you have enough space for all financial activities
- UNIQUE DESIGN & A4 SIZE - Income and expense log book cover is lovely, golden spiral bound design, size of 8" x 10.5". Just the perfectly size to fit in your backpack, purse or laptop case. Without taking up your space and always helping you keep track of your small business
- THE PERFECT GIFT - Income & expense notebook as gift for woman & man. Use it to track your week-to-week progress, make efficient adjustments whenever needed
Rank #3

- FOR LANDLORDS and MORE: Adams Money/Rent Receipt books let you offer receipts for rent payments, in-home day care, craft fair sales and other cash transactions
- 200 TWO-PART CARBONLESS RECEIPTS: Get 4 perforated customer receipts per page; the yellow copy stays behind in your book
- SPIRAL-BOUND EFFICIENCY: A neat spiral keeps your duplicates in numerical order for a permanent record of transactions
- CONSECUTIVELY NUMBERED: Large 6-digit numbers in the upper right hand corner help you thumb through orders quickly, Consecutively numbered makes tracking easy
- 200 SETS PER BOOK: Stock up so you never run out; books provide 200 sequentially numbered carbonless sets
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




