Missing a life insurance premium does not always end coverage on the due date. Your policy may include a grace period, during which coverage continues, but if the premium remains unpaid after the applicable period, the policy may lapse. The exact deadline and any chance to reinstate coverage depend on your policy and applicable state law, so contact the insurer promptly and ask for the dates and requirements in writing.
What happens after you miss a premium payment?
- The premium comes due. Check the policy for its payment schedule and how the insurer treats a payment’s receipt or posting date.
- A grace period may apply. The policy may remain in force during this period even though the premium has not been paid. The National Association of Insurance Commissioners (NAIC) model provision describes continued coverage during grace, but it is model language—not a guarantee that every policy uses the same period. NAIC model provision compilation.
- The policy may lapse if payment remains overdue. The Texas Department of Insurance says, “If you don’t pay the premium within the grace period, your policy will lapse.” That is general Texas consumer guidance; your contract and governing state law determine your actual dates and rights. Texas Department of Insurance, Life insurance guide.
A missed due date and a lapse are not necessarily the same event. Ask the insurer whether your coverage is still active and what exact date and amount apply to your account.

As an Amazon Associate I earn from qualifying purchases.
How long is the grace period?
There is no single number that can safely be applied to every U.S. life insurance policy. The NAIC model provision lists minimum periods of 7 days for weekly-premium policies, 10 days for monthly-premium policies, and 31 days for other policies. These are periods in a model provision, not a statement that every insurer or state follows those terms. NAIC model provision compilation.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Texas’s Office of Public Insurance Counsel says, “Most policies have a 31-day grace period after your premium’s due date.” The word “most” matters: this is Texas consumer guidance, not a universal rule or a substitute for checking your contract. Texas Office of Public Insurance Counsel, Life Insurance – Know Your Rights.
#1 Best Overall
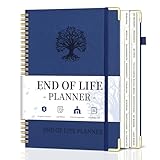
- What You Left Behind When You Left: This end of life planner with tabs meticulously covers 16 different sections, ensuring all key details are recorded. From personal information to final wishes, all necessary information that loved ones may need is carefully organized.
- Thoughtful Design: Featuring a B5 size (7.9" x 10.4"), our peace of mind planner is equipped with twin-wire spiral binding for 360° flexible page turning. It comes with an inner pocket, pen holder, and elastic band for organization flexibility.
- Comprehensive Structure: The death book planner includes 16 detailed sections such as catalog pages, personal and family info, medical info, property and financial assets, beneficiaries, pet info, insurance coverage, active accounts, memberships, funeral arrangements, and final wishes.
- Exclusive Features: The final wishes organizer planner is printed in large font on 100GSM non-bleed paper, easy to read. Special gold corner protection design effectively safeguards the cover from damage. Includes 8 blank note pages to meet diverse note-taking and planning needs.
- Ideal for Seniors and Adults: Our estate planning organizer helps to document and clearly communicate lifelong aspirations. Ensure family can accurately execute wishes without overlooking any details, providing peace of mind.
Look in your policy for the grace-period clause, then ask the insurer to confirm the final date to pay while coverage remains in force. Do not calculate a deadline from a general article alone; the payment frequency, policy terms, state law, and account details can matter.
What to do right away
- Contact the insurer using its official customer-service channel. Ask whether the policy is active, in its grace period, or lapsed. Request the answer in writing.
- Confirm the payment deadline and amount. Ask what must be paid, whether interest or policy indebtedness is included, and which payment methods and posting dates count under your contract.
- If it has lapsed, ask about reinstatement immediately. Get the application requirements, any deadline, and the effective date in writing before assuming coverage has been restored.
- Keep records. Save the insurer’s response, any application or conditional receipt, payment confirmation, and information about when the payment was received or posted.
Useful questions to send the insurer include:
- Is my policy still in its grace period, or has it lapsed?
- What is the exact deadline and total amount required to keep coverage in force or seek reinstatement?
- Do I need to submit a reinstatement application or evidence of insurability?
- Are interest or policy-loan balances due?
- When would reinstated coverage take effect, and would any limitations apply?
- Which payment methods and posting dates count under this contract?
Can you reinstate a lapsed policy?
Possibly, but reinstatement is conditional and policy-specific. It is not an automatic right in every situation, and no general article can establish that an insurer will approve your request.
Rank #2

- ORGANIZE ALL YOUR IMPORTANT INFORMATION: This estate planning organizer with tabs covers 16 different components that encompass all crucial details, carefully organizing essential information that your loved ones may need, from personal information to final wishes.
- USER-FRIENDLY DESIGN: Our B5 size (7.9 "x10.6") funeral planning book features a convenient twin-wire spiral binding for 360° flexible page turning. Specially added gold corner protection design, carefully protect the cover from damage. In addition, it comes with an inner pocket for keeping important documents organized.
- REASONABLE ORGANIZATION STRUCTURE: This death planner organizer comprises 16 detailed sections, encompassing catalog pages, personal and family info, medical info, property details, financial assets, beneficiaries, pet info, insurance coverage, active accounts, memberships, funeral arrangements, final wishes and so on.
- EXCLUSIVE ARRANGEMENT: The final wishes organizer planner is printed in large font on 100GSM non-bleed paper. In addition, 8 blank note pages are also included in this peace of mind planner to meet your diverse note-taking and planning needs.
- SUITABLE FOR SENIORS & ADULTS: This when i die book planner will help you carefully document and clearly communicate your lifelong aspirations. With this notebook, your family can fulfill your last wishes accurately, ensuring that every detail is not left out and giving you peace of mind.
State-law examples illustrate why the contract and jurisdiction matter. Massachusetts law describes an example in which an insurer’s acceptance of overdue premium without an application can reinstate coverage, while a policy may instead require an application and issue a conditional receipt. North Carolina law gives an example involving a written application, evidence of insurability satisfactory to the insurer, overdue premiums, and policy indebtedness. These are different state examples, not a combined nationwide checklist. Massachusetts General Laws, Chapter 175, Section 140; North Carolina General Statutes, Section 58-58-20.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsAsk the insurer for the complete reinstatement terms that apply to your policy, including the deadline, payment amount, application and health-evidence requirements, and when coverage would resume. Do not assume that submitting a form or making a payment by itself restores coverage.
Rank #3

- 📓End of Life Planner - Provide your loved ones with the clarity and guidance they need with end of life planning book. By putting your affairs in order, you leave a thoughtful guide that alleviates uncertainty and burden, bringing peace of mind to those you care about most.
- 📓Comprehensive Layout - The death book planner is structured in two main parts: Practical Information and Personal Wisdom, comprising 16 sections in total, such as: Personal, Medical, Arrangements, Dependents, Finance, Business, Beneficiaries, Key Contacts, Property, Insurance, Pets, Accounts, Memberships, My Wishes and Advice, Last Words.
- 📓Durable and Easy to Read - This A5-format beneficiary planner (6.4" x 8.5") features a durable leather cover with hardcover binding. The interior is printed on thick 120 GSM paper with bold, enlarged fonts for easy reading.
- 📓Convenient and Organized - The funeral planning book features an integrated pen loop for your writing instrument, an expandable back-pocket for storing important documents, and a delicate ribbon bookmark to easily keep your place as you complete each section.
- 📓Thoughtful Gift - Our parents often recognize the need for organization but don't know where to start. Gifting this estate planning organizer shows you care, making those discussions easier and more productive, giving them a welcomed and simple way to get everything in order.
Does the type of life insurance change your options?
Term life
Term life provides coverage for a set period. The policy’s terms determine what happens if a premium is missed and whether reinstatement is available. NAIC, Life Insurance.
Whole life and other cash-value coverage
Whole-life policies have nonforfeiture values under state law; depending on the policy, value may be paid in cash or applied through another insurance option if the policy ends after missed payments or is surrendered. Cash value is not a promise that an overdue premium will be paid automatically. NAIC also explains that policyholders may borrow against cash value, which can affect policy indebtedness. Check your contract and account statement to find out what options and values, if any, apply to your policy. NAIC, Life Insurance; NAIC, Whole Life Insurance.
Do not assume your policy has an automatic premium loan provision or a particular nonforfeiture option. Ask the insurer what is actually included in your contract and what value remains.
Free tools Windows power users keep installed
One-click scans. No signup required.
Where to get help if the insurer’s answer is unclear
Start with the insurer’s written explanation and the policy’s premium, grace-period, and reinstatement provisions. If you still need help understanding your rights, contact your state insurance department. The NAIC provides information on finding state insurance department resources and licensed agents and companies. NAIC consumer resources.
Quick Recap
Best Value
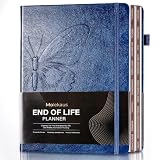
- 【Convenience for Family, Reduce Stress】With this end of life planner, make necessary final arrangements and emergency preparedness guidelines to ensure your loved ones have everything they need. Helping you organise things more conveniently during difficult times can reduce your stress and confusion. It will also help your family handle all matters with ease.
- 【Larger font for easy use】This end of life planner organizer binder uses bold fonts and high-contrast ink, making it suitable for elderly people, ensuring their eyes can read comfortably. The extra-large text layout minimises eye fatigue and provides ample space for handwritten details—perfect for recording sensitive information during multiple reviews.
- 【Stay organized and feel at ease】Our guide features 16 friendly sections designed to help you record your legal, medical, financial, and end-of-life wishes. We're here to help you communicate your needs clearly and effectively, making it simpler to keep everything in order.
- 【Convenient Design, Long-lasting Durability】This 7x10 inch estate planning organizer is equipped with a pen loop for easy access, an elastic closure band to secure the contents, a ribbon bookmark for quick positioning, and an expandable back pocket for storing loose documents. It uses thick acid-free paper, reinforced perfect binding, and a sturdy cover, allowing you to rely on it for many years.
- 【The thoughtful gift】This estate planning binder journal is a wonderfully thoughtful gift! It comes beautifully packaged and offers both practicality and meaning. With its timeless design, it’s the perfect way to help your loved ones navigate those sensitive conversations with warmth and empathy.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




