Yes, 60% is a credible forecast—but it is not the latest number available, and it does not mean hyperscalers will own 60% of all data centers. Synergy Research Group estimated that hyperscale operators accounted for 44% of global data-center capacity at the end of the first quarter of 2025 and projected a share of about 60% by 2030. Its newer Q4 2025 update put hyperscalers at 48% and projected 67% by 2031.
The crucial distinction is that “hyperscaler capacity” includes capacity these companies operate through both owned facilities and leases. The market is moving toward hyperscaler control of a majority of capacity, but the exact timing depends on AI and cloud demand, power availability, construction, financing, supply chains, and regulation.
As an Amazon Associate I earn from qualifying purchases.
The forecast behind the headline
The original forecast, reported on June 27, 2025, came from Synergy Research Group analysis of the global data-center market. At the end of Q1 2025, hyperscale operators represented 44% of worldwide data-center capacity. Synergy projected that their share would rise to approximately 60% by 2030.
The same analysis counted 1,189 large hyperscale facilities at the end of Q1 2025. Hyperscale infrastructure was projected to grow roughly threefold over the forecast period, with hyperscale-owned infrastructure growing at least 20% annually worldwide. Total capacity was expected to expand at double-digit annual rates across all major regions.
#1 Best Overall

- Sturdy:4u server rack is construct from cold rolled steel, with a weight capacity of 110lbs(50kg); Electrostatic powder coat prevents rust and corrosion,quality finish
- Direct use:Open and use, not having to assemble it.Network rack can be placed flat or mounted on the wall,also can be installed vertically under the table
- Design Features:maximum mounting depth of 14 in,cables can be fixed on the side panel;Open frame server rack achieves effortless inspection, replacement and assemble
- Installation:wall mount network rack is easy to install,with instructions or videos for reference;Equipped with multiple accessories, suitable for different needs
- Application:EIA/ECA-310-E Compliant;wall mounted 4u rack fits all 19" racks and cabinets to hold various IT, network, and AV equipment;wall mount rack available in 4U, 6U, and 8U to choose
Enterprise-owned, or on-premises, facilities represented approximately 34% of capacity in 2025, down from about 56% six years earlier. Synergy projected that share to fall to approximately 22% by 2030.
Those figures describe a major change in the infrastructure mix, but they are forecasts—not settled facts. “Will command” is headline language; the more accurate wording is that Synergy projected hyperscalers to account for about 60% of capacity by 2030.
The latest baseline is already higher
Synergy’s subsequent update, covering Q4 2025, provides a more current starting point. According to its latest analysis:
| Period | Hyperscaler share | On-premises share | Other stated detail |
|---|---|---|---|
| 2018 | Approximately 24% implied | 56% | Historical comparison in the later update |
| Q1 2025 | 44% | 34% | Original forecast baseline |
| Q4 2025 | 48% | 32% | Non-hyperscale colocation: 20% |
| 2030 | About 60% | 22% | Original forecast |
| 2031 | 67% | 19% | Newer forecast |
The later update also counted 1,360 large hyperscale facilities. Nearly 60% of hyperscaler capacity was in facilities that the operators had built and owned themselves; the remainder was leased.
The Q4 2025 figure and the 2031 projection should not automatically be treated as a perfect replacement for the original 2030 forecast. Synergy would need to confirm that the releases use identical definitions, geographic coverage, capacity measurements, and operator classifications. Still, the direction is clear: hyperscaler-associated capacity is growing faster than the rest of the market.
A 60% share in 2030 can reasonably be inferred from a trajectory reaching 67% in 2031, but that is an inference rather than a directly published 2030 figure in the newer summary.
What “hyperscaler” means
Hyperscalers are very large cloud, internet, and digital-platform companies that operate infrastructure at global scale. Common examples include Amazon Web Services, Microsoft Azure, Google Cloud, Meta, Oracle Cloud, Alibaba Cloud, and Tencent Cloud.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsThe term is an industry category, not a universal accounting classification. Different research firms may include different operators or apply different thresholds. For example, McKinsey identifies major cloud service providers as important drivers of AI-ready data-center demand, but its workload and capacity categories should not automatically be assumed to match Synergy’s.
“Capacity” does not mean facility ownership
This is the most important qualification in the forecast. Data-center capacity is commonly expressed through IT power capacity, measured in megawatts or gigawatts, although research firms may distinguish among installed, live, commissioned, contracted, or planned capacity.
A hyperscaler can obtain capacity in several ways:
- Self-built campuses: The operator develops and owns the facility.
- Leased wholesale space: A data-center company owns and operates the building while the hyperscaler leases substantial capacity.
- Build-to-suit facilities: A third party develops a customized site under a long-term agreement.
- Colocation and reserved capacity: The operator contracts for power, racks, or suites inside a provider’s facility.
As a result, “hyperscalers command 60% of capacity” is not the same as “hyperscalers own 60% of data centers.” Companies such as Equinix, Digital Realty, QTS, CyrusOne, NTT, and Vantage can remain important infrastructure owners even as hyperscalers account for a growing share of the space and power they provide.
Why hyperscaler capacity is expanding
Cloud migration
Businesses continue moving workloads from internal server rooms and corporate data centers to public cloud and colocation environments. Cloud providers offer elastic capacity, managed databases, analytics, security services, global networking, and faster deployment.
This does not mean every application should move to public cloud. But commodity workloads, variable demand, geographically distributed services, and cloud-native applications are structurally favorable to hyperscale infrastructure.
AI training and inference
Artificial intelligence is accelerating an existing cloud and digital-services trend. AI training requires large clusters of GPUs or other accelerators, high-speed interconnects, substantial storage, dense power feeds, and advanced cooling. Inference can require a more distributed footprint to meet latency and data-sovereignty requirements.
McKinsey estimates that AI-ready data-center demand could grow at an average annual rate of 33% from 2023 through 2030 in its midrange scenario. It also estimates that roughly 70% of total data-center demand could require facilities capable of supporting advanced AI workloads by 2030.
Rank #2
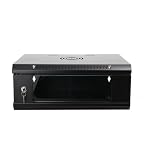
- 『Network Organizer』: Do you find a suitable storage device for multi server in home or office? Our network cabinet is specially designed to keep network accessories in order. We provide 2U/4U/9U/15U server cabinets, you can choose any size according to your needs.
- 『Better Heat Dissipation』: The vents on the server rack cabinet speed up airflow level and reduce IT equipment's overheating. And the top cooling fan holes to increase wall mount server rack's cooling performance.
- 『Safe Server Case』: The reinforced tempered glass door on the network rack wall mount makes you clear to see all network equipments. Besides, the key can ensure the security of data and equipment. Our wall mount server rack is ideal for use in public places such as office, school and factories.
- 『Durable Network Enclosure』: Crafted from cold-rolled steel and powder coated with black finishing surface, the wall mount network rack is sturdy and not easy to deform, providing a long service life.
- 『Easy to Assemble』: Our wall mount server cabinet has all accessories in a package, and the item structure is very simple, you can install it quickly.
BCG projects that generative AI could account for about 60% of data-center power-demand growth from 2023 through 2028, while representing approximately 35% of total power demand by 2028 in its base case.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchAI is a major accelerator, not the only source of demand. Search, streaming, advertising, social networks, online commerce, enterprise software, storage, and traditional cloud workloads continue to consume infrastructure.
Economies of scale
Large operators can spread the cost of power procurement, custom servers and accelerators, networking, cooling, security, facilities engineering, data replication, and software orchestration across enormous workloads. That scale can make hyperscaler infrastructure attractive even when the customer ultimately uses a third-party facility.
The market can grow while on-premises loses share
A falling on-premises percentage does not necessarily mean that the absolute amount of private infrastructure immediately shrinks. The denominator—the total data-center market—is expanding rapidly.
JLL’s 2026 Global Data Center Outlook projects approximately 200 gigawatts of global data-center capacity by 2030 and about 97 GW of additional capacity from 2026 through 2030. Its framework includes colocation, build-to-suit, hyperscale owner-occupied, and on-premises capacity.
Recommended Free Tools
JLL separately projects 70 GW of hyperscale owner-occupied capacity by 2030 and 105 GW of leased colocation and build-to-suit capacity. These categories are not interchangeable with Synergy’s market-share figures, but they illustrate why ownership and control must be separated.
Goldman Sachs Research estimates approximately 122 GW of global data-center capacity online by the end of 2030 and projects hyperscalers plus wholesale operators to account for about 70% of that capacity. Goldman’s figure combines categories that Synergy discusses separately, so it should not be presented as a competing estimate of hyperscaler-only share.
Why colocation remains central
Hyperscaler growth does not mean hyperscalers will build every campus themselves. Their operating model is increasingly dual-sourced: self-build strategic sites while leasing or contracting for capacity where a third-party provider can deliver power and space faster or more economically.
That creates demand for power-secured campuses, wholesale colocation, build-to-suit development, interconnection services, liquid-cooling systems, backup generation, and specialized facilities engineering. A hyperscaler-heavy market can therefore benefit third-party data-center operators rather than eliminate them.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →For infrastructure investors and developers, the most valuable asset may not be an empty building. It may be a site with reliable power, transmission access, permits, fiber connectivity, cooling capability, and a credible delivery schedule.
The constraints that could change the forecast
Power and grid access
Power availability is increasingly more restrictive than land or shell construction. In some markets, hyperscalers are securing land and power 24 to 36 months before planned commissioning. Data Center Knowledge, citing DC Byte analysis, describes this power-first approach to development.
Goldman Sachs estimates that roughly $720 billion in grid investment through 2030 could be needed to support rising data-center demand. Transmission permitting and construction can take years, creating a serious risk that a planned data center is ready before the grid connection is.
AI economics and oversupply
Capacity plans depend on the economics of AI, not simply on enthusiasm for it. If AI adoption, usage, or monetization disappoints, operators may delay projects, reduce orders, or leave some capacity underutilized. Goldman Sachs has identified the possibility of an oversupply cycle from 2027 onward if supply catches up with demand faster than expected.
Efficiency improvements
More efficient models, chips, cooling systems, and inference techniques could reduce the capacity needed for a given amount of computing work. Efficiency may lower demand per task while total usage still rises, making the net effect difficult to predict.
Rank #3

- Spacious Chassis: This massive 4U server case has 8 internal 3.5" HDD bays plus room for 3 additional 5.25" devices
- Expandable & ATX/CEB Compatible: 7 PCI expansion slots and ATX and CEB motherboard compatibility give you growth options for all of your needs
- Quiet Cooling: 4 pre-installed cooling fans provide excellent airflow and heat protection at reduced noise. 2 front 120mm PWM fans and 2 rear 80mm fans ensure your drives and chassis avoid overheating
- Desired Features: Front panel LED indicators for power, HDD, and LAN status monitoring allow quick, easy visual assessment. Additional utility with 2 x USB 3.0 port and built-in front panel lock provides extra security for your server case
- Rackmount Design: Standard 4U rackmount form factor allows easy installation in server racks and data center environments with included mounting hardware for professional deployment
Construction, financing, and equipment
Data centers require large upfront investments, long construction cycles, specialized labor, transformers, switchgear, networking equipment, cooling systems, and advanced accelerators. Higher financing costs, equipment shortages, labor constraints, or supply-chain disruptions can slow the buildout even when customer demand is strong.
Permitting, water, and communities
Projects can face grid-interconnection queues, environmental review, zoning restrictions, water-use disputes, noise complaints, and local opposition. A global forecast does not mean every proposed location will be approved or completed.
Regional regulation and sovereignty
Data-localization requirements, export controls, national-security rules, and restrictions on advanced accelerators can produce a more regional infrastructure market. BCG notes that customer requirements and national rules can determine where data is processed.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →The shift is not evenly distributed around the world
The United States has a disproportionately large share of hyperscale-owned infrastructure. The original Synergy commentary said self-owned hyperscale capacity is much more prevalent in the United States than in EMEA or APAC.
JLL estimates that the Americas represent approximately half of global data-center capacity and expects the region to remain the largest market. Regional shares can differ substantially because of electricity prices, cloud adoption, land, fiber, permitting, tax policy, national security, and data-sovereignty rules.
A hyperscaler may have a relatively small owned footprint in a particular country while controlling significant local capacity through leases. Global ownership, regional ownership, and regional access are therefore three different measures.
What this means for enterprise infrastructure decisions
The forecast should not be read as a command to move every workload to a hyperscaler. Enterprises should evaluate the workload, not follow the market-share headline.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
| Option | Often strongest for | Main advantage | Main drawback |
|---|---|---|---|
| Public hyperscaler | Variable workloads, rapid deployment, global applications | Elasticity and broad managed services | Potential egress costs, lock-in, and high sustained-use expense |
| GPU-focused cloud | AI training and inference requiring specialized accelerators | Access to scarce GPU capacity | Narrower platform, regional constraints, and potentially less mature enterprise coverage |
| Colocation or build-to-suit | Large, predictable workloads needing dedicated hardware | More physical control without building an entire facility | Long commitments and substantial infrastructure expertise |
| On-premises | Sensitive, regulated, latency-critical, or highly stable workloads | Control, sovereignty, and direct physical placement | Capital intensity and operational responsibility |
Decision criteria should include latency and geography, data sovereignty, regulation, GPU availability, power density, network egress, utilization, resilience, disaster recovery, vendor lock-in, specialized hardware, security controls, and the organization’s ability to operate physical infrastructure.
Regulated financial, government, defense, healthcare, and industrial workloads may remain private for security, compliance, control, or latency reasons. AI could also lead some enterprises to add private GPU infrastructure rather than outsource every workload.
How to interpret the forecast as an investor or policymaker
Do not treat a rising hyperscaler share as a simple prediction that every data-center owner will lose. The result depends on what is being measured and who supplies the physical infrastructure.
- Separate hyperscaler-operated capacity from hyperscaler-owned capacity.
- Distinguish capacity share from revenue share, cloud market share, and facility count.
- Do not substitute AI-ready capacity for total installed capacity.
- Check whether a market estimate counts live, planned, contracted, or only selected capacity.
- Separate a company’s share of market growth from its share of total capacity.
- Evaluate power, transmission, permits, water, cooling, labor, and financing before assuming a project will be delivered.
For investors, the relevant exposure may extend beyond cloud companies to data-center landlords, utilities, transmission developers, equipment manufacturers, networking suppliers, cooling providers, and construction firms. But the forecast alone is not an investment recommendation: valuation, debt, customer concentration, contract terms, power costs, and execution risk still matter.
Free tools Windows power users keep installed
One-click scans. No signup required.
Bottom line
Hyperscalers are already approaching half of global data-center capacity, according to Synergy’s Q4 2025 update. The original 2025 forecast called for about 60% by 2030, while the newer trajectory projects 67% by 2031.
The direction is convincing, but the exact milestone is conditional. “60% of capacity” does not mean hyperscalers will own 60% of all facilities. It includes leased and build-to-suit capacity, while the total global market may expand dramatically and still retain meaningful private infrastructure.
The central infrastructure question is therefore not simply whether hyperscalers will dominate. It is how much capacity they will own, lease, or control through long-term contracts—and whether power, capital, regulation, and AI economics allow the planned buildout to happen.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




