Gold can complement stocks and bonds, but it is not a guaranteed hedge, and there is no universally suitable percentage for every investor. To keep it from becoming too large a holding, first account for all your existing gold exposure, choose a target that fits your goals and risk tolerance, select a vehicle whose costs and custody terms you understand, and set a rule for rebalancing.
What gold can—and cannot—do in a portfolio
Gold is one possible diversifier: its returns may behave differently from those of stocks and bonds, and it is liquid in many forms. That does not mean its price will rise when other holdings fall, or that adding it will always reduce portfolio risk. Its role depends on what else you own, the period being considered, and how the investment is implemented.
As an Amazon Associate I earn from qualifying purchases.
The World Gold Council identifies potential roles for gold that include returns, diversification, and liquidity. It describes gold as a strategic long-term investment and a mainstay of a well-diversified portfolio. That is the Council’s view, not a neutral recommendation: it is an industry association whose members are gold mining companies. Its allocation findings are useful as examples of how gold performed in specified historical models, but they are not independent consensus or a personalized allocation recommendation.
The SEC’s Investor.gov explains diversification with the principle, “Don’t put all your eggs in one basket.” The same principle argues against letting any one holding—including gold—dominate a portfolio. Diversification is about the whole mix, not adding an asset simply because it has a reputation as a safe haven. Gold can lose value, and its price may not move in the opposite direction from the rest of your holdings when you would most want it to.
#1 Best Overall

- ✔️Each coin contains 1/10 oz of gold.
- ✔️Obverse: Lady Liberty holding a torch with an olive branch.
- ✔️Reverse: The Type 1 reverse, used from 1986-2021, shows a male bald eagle in flight carrying an olive branch to his nest, where a female awaits with her young. The Type 2 reverse, introduced in 2021, shows a bold close-up portrait of an eagle.
- ✔️Each Gold Eagle is a sovereign monetized bullion coin fully guaranteed by the U.S. Mint.
How much gold should you hold?
No allocation in the cited material is established as right for every investor. A suitable target depends on your investment horizon, tolerance for losses and price swings, goals, and existing holdings. It also depends on the job you expect gold to do: for example, whether you want a modest diversifying exposure or direct ownership of bullion. Define the target as a share of your total portfolio rather than as a stand-alone dollar amount. This makes it easier to see whether gold is becoming too large relative to everything else you own.
Two World Gold Council analyses illustrate why model results should not be mistaken for personal guidance:
- 4%–15%: The Council’s implementation page says its analysis found that allocations in this range improved risk-adjusted returns in hypothetical portfolios over the prior decade, depending on portfolio composition and region. The page is undated and was accessed on 13 October 2026. This is a modeled historical range published by a gold industry association—not a recommended range for investors generally.
- 2.5%, 5%, 7.5%, and 10%: In its 2026 edition, published 4 February 2026, the Council tested these gold weights in a hypothetical USD portfolio over a 20-year period ending 31 December 2025. The Council reports that the results varied with portfolio risk and construction; higher-volatility starting portfolios called for larger modeled allocations within the range it considered.
Neither analysis identifies an optimal allocation for a particular person. The Council’s modeled maximum risk-adjusted allocation changes with the starting portfolio’s risk level, and its 4%–15% finding varies by region and composition. Treat both as context for the question—not as a rule to copy. There is no basis here for calling one percentage suitable for everyone, or for assuming the same model result applies to a portfolio in a different country or with a different mix of assets.
What the 20-year portfolio comparison says—and what it does not
The World Gold Council’s 2026 edition reports results for a hypothetical representative portfolio initially comprising 50% stocks, 40% fixed income, and 10% alternatives. Its comparison uses monthly USD performance from 31 December 2005 through 31 December 2025. In the gold version, gold was funded by proportionally reducing all assets. For the 5% gold case, the Council reports these figures against the version without gold:
Rank #2

- ✔️Each coin contains 1/10 oz of gold.
- ✔️Obverse: Lady Liberty holding a torch with an olive branch.
- ✔️Reverse: Portrait with an American bald eagle, a design by Jennie Norris in 2021.
- ✔️Each Gold Eagle is a sovereign monetized bullion coin fully guaranteed by the U.S. Mint.
| Reported measure | With 5% gold | Without gold |
|---|---|---|
| Annualised return | 7.0% | 6.7% |
| Annualised volatility | 9.6% | 9.9% |
| Risk-adjusted return | 72.3% | 68.1% |
| Maximum drawdown | −32.7% | −34.9% |
These are the Council’s historical backtest outputs for its chosen hypothetical mix and definitions, published on 4 February 2026. They do not predict future returns, show what every portfolio would have experienced, or establish that a 5% allocation is suitable for you. A different starting mix, geography, measurement period, or implementation could produce different results. The Council’s industry perspective is relevant when weighing its interpretation of the figures. The comparison also does not mean investors can expect those results simply by buying a product that tracks gold: actual fees, tracking, custody, and the investor’s other holdings matter.
Choose a way to hold gold
Gold exposure can mean direct ownership, a claim on vaulted metal, or a financial contract. These methods differ in custody, costs, convenience, liquidity, and the rights you actually receive. Product labels and regulations vary by market, so confirm the structure and eligibility where you live. A basic question to ask is whether you own bullion, hold a security or certificate tied to bullion, or have a contract whose value is linked to gold.
| Method | What it offers | What to check |
|---|---|---|
| Physically backed ETF, ETC, or similar exchange-traded product | Exchange-traded exposure to bullion prices without personally handling or storing gold. Such vehicles usually seek to track the spot price. | Legal structure, fees, tracking, custody, local availability, and whether your account is eligible. The product is not the same as personally holding coins or bars. |
| Physical bullion bars or coins | Direct ownership of investment gold. | Purchase premium over spot, delivery, storage, insurance, and resale arrangements. The World Gold Council advises buying from a bank or reputable dealer. |
| Vaulted gold, internet investment gold, or certificates | Gold held in a professional vault, with ownership or a certificate depending on the arrangement. | Whether you own specific or pooled metal, who the custodian and counterparty are, fees, redemption terms, and whether you can take delivery. |
| Savings plan | Periodic purchases that build a gold holding over time. | Custody, fees, spreads, redemption rights, and whether the plan gives you direct ownership or a contractual claim. |
| Futures, options, or forwards | Contractual exposure that can be used for hedging or leveraged and speculative strategies. | Contract obligations and risks. Futures are standardized contracts with margin requirements; options give a right, not an obligation, to exercise; forwards are bilateral, non-standardized agreements. These are not default simple long-term holdings. |
These descriptions reflect the World Gold Council’s overview of gold investment methods. Terms, protections, and availability are product- and jurisdiction-specific; check the relevant documents rather than assuming that two products with similar names confer the same ownership rights.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallFor someone who wants physical ownership, investment-grade bullion coins are one available category, but no particular coin or seller is established here. The World Gold Council’s guidance is to use a bank or reputable dealer and account for premiums, delivery, storage, and insurance. Buying a coin is not simply a way to acquire gold at the quoted spot price: the transaction price can include a premium, and holding the metal brings ongoing practical responsibilities. A physically backed exchange-traded product, by contrast, offers exchange-traded exposure without asking you to handle or safeguard bullion yourself, but it still has a product structure, fees, custody terms, and local eligibility to examine.
Rank #3
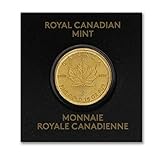
- Purity: .9999 Fine Gold (24-Karat)
- Diameter: 8 mm (0.314961 inches)
- Metal Content: 0.0322 Troy Ounces
- Stock Photo; Image is indicative of quality
- You will receive one coin per purchase in a divisible blister card with a unique serial number shown on the back of the assay card. The yer-date of the coin will be random.
Account for the full cost and exposure
Look beyond the quoted gold price
With physical coins or bars, the amount you pay can exceed the spot price because of a dealer premium. Delivery, secure storage, and insurance add practical costs and responsibilities. Selling may also involve a difference between the price you can receive and the spot price. The Council recommends a bank or reputable dealer; no particular seller or product is established here. Before buying, consider how the metal will be stored, who can access it, what insurance applies, and how you would arrange a sale or delivery if your plans change.
Exchange-traded products avoid the need to handle bullion personally, but they are not cost-free or interchangeable. Review ongoing fees, how closely the product tracks gold, its custody arrangement, and the legal structure. For vaulted holdings and savings plans, examine spreads, redemption rights, custody, and whether you have ownership of gold or a claim on a provider. A redemption right may not be the same as a practical ability to take delivery, so check the terms, any applicable costs, and minimums. Local tax treatment and account eligibility depend on jurisdiction and are not established by a general comparison.
Futures, options, and forwards require a different kind of scrutiny from buying a coin or an exchange-traded product. Futures involve standardized contracts and margin requirements; options convey a right, not an obligation, to exercise; forwards are bilateral and non-standardized. Those contractual features can create obligations and risks that are unlike simply holding bullion. The World Gold Council says futures are typically used by corporate risk managers or institutional speculators, not as a default simple long-term holding. Do not treat a contract as interchangeable with direct ownership of gold.
Recommended Free Tools
Count indirect holdings too
Before setting a target, look through funds and other investments for gold exposure that may not be obvious from the account name. Add that exposure to any bullion or gold-linked products you hold. Otherwise, a new purchase can take your total allocation above your intended level even if the purchase itself seems modest. Use the same definition of “gold exposure” consistently when you assess the portfolio; a fund holding a gold-linked product may not be the same as owning physical bullion, but it still may contribute to the exposure you are trying to manage.
Rank #4

- Our Jewelry is a Beautiful Way to Express Love; Friendship; Beauty and Art. The Right Gift Can Make Someone’s day! Whether the Occasion is a Birthday; Anniversary; Christmas; Black Friday; Cyber Monday or Mother's Day
- Our Collection Includes items for Men or Women and We Offer a Wide Range of beautiful Earrings; Bracelets; Bridal Engagement Rings; and Necklaces for Any Occasion. Our Jewelry Collections are the Perfect Gifts for Mom; Wife; Fiance; Bride; Mother; Father; Groom; Daddy; Daughter; Sister; Brother; Teacher; Employee; Coworker; Friend; Niece; Nephew; Son; Grandmother; Grandfather and More.
- Whether It is For Christmas Gifts or Stocking Stuffers; FB Jewel’s Pieces are Made With the Best Quality Materials Available as Well as Premium Quality Gold; Silver; Tungsten or Titanium for Him and Her. Why Not Treat Your Loved One for Christmas; Valentines Day; Mothers Day; Fathers Day; Graduation; Birthday; Weddings or Anniversary with FB Jewels Solid 22K Yellow Gold 1Oz American Eagle Coin (1.28 x 1.28 Inches)
- All 10K 14K or 18K Gold or 925 Silver are Made with Real Gold or Silver Not Plated
Then compare your current total with the target as a percentage of all portfolio assets. A dollar amount alone can obscure the picture: the same gold holding represents a different share in a small portfolio than in a large one. This full-portfolio view also helps prevent duplicating exposure when several accounts or products are involved.
A practical process for adding gold without letting it take over
- Inventory your whole portfolio. List your stocks, bonds, cash, alternatives, and existing gold-related holdings. Identify indirect exposure through funds as well as direct bullion or gold-linked products. Include accounts you manage separately so you are not setting a target against only one account when your real allocation spans several.
- Decide the role for gold. Write down why you want it and how it fits alongside the rest of your assets. Do not treat a recent rise in gold’s price, or a claim that it always protects portfolios, as a substitute for a plan. If you cannot describe what role you want the holding to play, it will be harder to decide what size is appropriate or when to rebalance.
- Set a target for the total portfolio. Choose a percentage in light of your goals, horizon, risk tolerance, and other exposures. Use published historical model ranges as context only; they cannot determine your personal target. Make clear whether the target includes all gold-linked products and direct holdings, and write it down before making a purchase.
- Compare implementation choices. Check ownership rights, custody, convenience, fees or premiums, liquidity, redemption terms, and local rules for the product you are considering. For physical bullion, include delivery, storage, insurance, and resale arrangements; for exchange-traded products, check structure, tracking, fees, custody, and account eligibility; for vaulted or savings arrangements, confirm ownership and redemption terms.
- Write down a rebalancing rule before buying. Decide whether you will review on a calendar schedule or act when your allocation crosses a preset band around the target. Record the target, review method, and threshold so that price moves do not turn into an improvised change of strategy. There is no single calendar interval or threshold established as right for all investors.
- Reassess when your circumstances change. Revisit the allocation if your goals, time horizon, risk tolerance, or the rest of your portfolio materially changes. Do not raise the target simply because gold recently outperformed. Check again that the vehicle still suits your account and that its terms, costs, and your need for access have not changed.
Use rebalancing to control allocation drift
When gold rises faster than the rest of a portfolio, its share can grow above the target even if you have not bought more. Rebalancing means returning holdings toward the chosen allocation. Investor.gov says investors may rebalance at a calendar interval or when holdings move beyond preset percentage bands, and that rebalancing generally works best relatively infrequently. It does not establish a single schedule or band that suits everyone.
A calendar approach might prompt a review at a chosen recurring interval. A threshold approach prompts a review when the gold weight moves outside a range you selected around your target. In either case, the rule should say what triggers a review and what action follows; the appropriate interval or band depends on the investor and is not specified by the cited guidance. A written rule can reduce the temptation to change the plan just because gold has recently risen or fallen sharply.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →As a simple illustration, if an investor has a written target of 5% of the total portfolio, a change in gold’s price can push the actual share above or below 5%. The investor’s rule could call for a review at a stated interval or after a stated deviation, then bring the allocation back toward the target. This illustration explains the arithmetic of drift; 5% is not a recommendation. Rebalancing can also involve trading costs, tax consequences, or account constraints, which depend on the investment and jurisdiction. Those practical effects are another reason to use a rule that is clear but not needlessly frequent.
Best Value

- Purity: .900 Fine Gold
- Metal Content: .1867 Troy Ounces
- Diameter: 21 mm; Thickness: 1.4 mm
- Stock Photo; Image is indicative of quality
- You will receive one coin per purchase
Common ways investors become overexposed
- Using a headline percentage as a personal prescription. Council model findings vary with portfolio mix, risk, and region; they do not settle an individual allocation.
- Forgetting embedded exposure. A fund or other holding may already include gold-related investments. Count it before adding a separate position.
- Allowing price appreciation to set the allocation. A rising gold price can increase its portfolio weight without any new purchase. A rebalancing rule helps make that drift visible.
- Confusing different forms of ownership. A coin, an exchange-traded product, a vault certificate, and a futures contract do not carry the same custody, redemption, or contractual rights.
- Ignoring costs and local rules. Premiums, storage, insurance, product fees, tax treatment, and account eligibility can change the practical result. Verify the details for your own market and account.
- Assuming gold always offsets losses elsewhere. Its potential diversifying role does not guarantee gains or protection in every market. Decide on an allocation based on the whole portfolio rather than relying on a promise of protection.
Frequently Asked Questions
How much gold should I hold in a diversified portfolio?
There is no universal percentage established for every investor. Consider your goals, investment horizon, risk tolerance, existing holdings, and the role you want gold to play. The World Gold Council has reported model-dependent historical allocation findings, including 4%–15% in hypothetical portfolios depending on region and composition, but this is not a personal recommendation.
How can I stop a gold allocation from getting too large?
Count direct and indirect gold exposure across your portfolio, set a target as a share of the whole portfolio, and write down a rebalancing rule. Investor.gov describes either calendar reviews or preset percentage bands; it does not specify one schedule or band for everyone.
Should I buy physical gold or a gold ETF or similar product?
Physical coins and bars provide direct ownership but bring premiums, delivery, storage, and insurance responsibilities. Physically backed exchange-traded products provide exposure to bullion prices without personally handling or safeguarding metal, but you should check their structure, fees, tracking, custody, availability, and account eligibility. Product rules differ by market.
Free tools Windows power users keep installed
One-click scans. No signup required.
Does gold always protect a portfolio when stocks fall?
No. Gold may diversify a portfolio, but it is not a guaranteed hedge and does not necessarily rise when stocks or bonds fall. Its effect depends on the rest of the portfolio and the period considered.
What should I check before using vaulted gold or a savings plan?
Check who holds the gold, whether you own specific or pooled metal or have a contractual claim, all fees and spreads, redemption rights, and whether you can take delivery. Terms and local rules vary.
The Bottom Line
Gold can be one component of a diversified portfolio, but neither a historical backtest nor an industry-published allocation range determines the right amount for you. Count all existing exposure, decide on a whole-portfolio target that fits your circumstances, compare the ownership and costs of available vehicles, and use a consistent rebalancing rule to keep the allocation from drifting.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




