Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsThere is no single Zelle-wide sending limit. The bank account you use to fund a payment determines your limit, and the amount may depend on your account tier, enrollment history, recipient, and the bank’s risk controls. The figures below are published consumer limits or schedules from major U.S. banks, checked October 5, 2026; your bank’s displayed limit is the one to rely on.
How Zelle sending limits work
Zelle does not set one dollar ceiling that applies to every customer. Participating banks set their own limits and may use a published schedule, a tier system, or a personalized amount shown after you sign in. A published maximum is not a promise that every customer can send that much or that every payment will be approved.
Sending and receiving are separate questions. A bank may not impose a dollar cap on what its customers receive, but the person sending the money can still be limited by their own bank. A large available balance does not override a sending limit.
“Daily” and “monthly” also need context: a bank may use a rolling window or a calendar period. Recipient status and recent account or profile changes can affect the amount available for a particular payment.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →#1 Best Overall

- All-in-One NFC & QR Code Multi-Payment Stand: Enable your customers to pay instantly with a simple tap or QR scan. This versatile stand supports Venmo, PayPal, Cash, Zelle, Cash App, and more, providing a professional contactless payment solution for counters, cafés, restaurants, retail stores, and pop-up shops
- No App or Fees – Easy Contactless Payments: Customers can complete payments directly via NFC or QR code without downloading apps, creating accounts, or paying subscription fees. This Scan to Pay sign ensures fast, seamless, and secure transactions, enhancing convenience and customer satisfaction
- No App or Fees – Easy Contactless Payments: Customers can complete payments directly via NFC or QR code without downloading apps, creating accounts, or paying subscription fees. This Scan to Pay sign ensures fast, seamless, and secure transactions, enhancing convenience and customer satisfaction
- Acrylic Desktop Stand: Crafted from high-quality acrylic, this NFC QR code payment stand is compact, self-standing, and perfect for counters, desks, or reception areas. Its sturdy tabletop design ensures visibility and professional presentation while customers tap or scan to pay effortlessly
- Acrylic Desktop Stand: Crafted from high-quality acrylic, this NFC QR code payment stand is compact, self-standing, and perfect for counters, desks, or reception areas. Its sturdy tabletop design ensures visibility and professional presentation while customers tap or scan to pay effortlessly
Published limits at major U.S. banks
The following comparison reflects official bank materials reviewed October 5, 2026. Amounts are U.S. consumer limits unless a business schedule is explicitly identified. These schedules are not directly interchangeable: eligibility, tier, recipient, and reset period differ.
| Bank | Published sending limit | Window and qualifications |
|---|---|---|
| Bank of America | Consumers: $1,000 per day during the first 30 days of enrollment; $2,000 per day on days 31–60; $3,500 per day after 60 days. The reviewed agreement also states $20,000 per month. Small businesses: $2,000 per day during the first 15 days, rising to $15,000 per day after 60 days; the agreement states $100,000 per month. | The agreement describes daily, weekly, and monthly amount and frequency limits; measurement may be rolling or calendar-based depending on the customer profile. Recently added or unenrolled recipients can have lower limits. Confirm the amount in the payment flow. Bank of America service agreement. |
| Chase | Consumer daily tiers: $500 (Tier 0), $2,000 (Tier 1), $5,000 (Tier 2), and $10,000 (Tier 3). Chase Private Client, business banking, Private Bank, and Wealth Management columns list $1,000, $5,000, $7,500, and $15,000 for those tiers. | The tier is assigned when a payment is set up, using factors that include the recipient. Amounts sent to all recipients in the same tier count toward that tier’s daily limit. Chase displays the applicable amount in the app or online during setup; its reviewed agreement states no general monthly dollar limit. Chase Zelle Service Agreement and Privacy Notice. |
| Wells Fargo | Most consumer accounts: up to $3,500 per rolling 24 hours and $20,000 per rolling 30 days. Small-business relationship: up to $15,000 per rolling 24 hours and $60,000 per rolling 30 days. | Limits may vary with account and online-banking history, recipient, and recipient payment history, and Wells Fargo may adjust them. The bank says it does not limit how much a customer can receive. Wells Fargo Zelle information. |
| Citibank | Consumers: untenured status, $500 daily and $2,500 monthly; tenured Standard, $2,500 daily and $15,000 monthly; tenured relationship-tier accounts, $5,000 daily and $20,000 monthly. Small businesses: untenured, $1,000 daily and $4,000 monthly; tenured, $5,000 daily and $40,000 monthly. | Daily limits run from 12:00 a.m. to 11:59:59 p.m. Eastern Time; monthly limits use a rolling 30-calendar-day period. New enrollment or changes to a Zelle profile or risk profile may result in untenured status. Newer or inactive recipients may have lower limits. The applicable amount appears in the app and online. Citibank Zelle terms. |
| Capital One | No universal dollar amount is published on the reviewed consumer Zelle page. | Capital One says limits may change and are flexible; view the current amount in the mobile app or online when setting up a payment. The bank says there is no limit on how much a customer can request, but the sender may have a limit set by their institution. Capital One Zelle. |
| U.S. Bank | No public dollar figure appears on the reviewed help page. | Limits include a daily send amount and a 30-day total, are set per person rather than per account, and also apply to requests and split-bill transactions. See the logged-in limit screens below. U.S. Bank help page. |
How to find your own current limit
Check the bank that will fund the transfer rather than relying on a general Zelle estimate. For banks that display a personalized limit, the amount shown after login takes precedence over a public schedule.
Rank #2

- ALL-IN-ONE DESIGN: Single high-visibility QR code accepts Venmo, Cash App, PayPal, and Zelle on a branded customer page
- PREMIUM CONSTRUCTION: Made from 3/8-inch thick high-impact plastic with precision-embossed text and logos, measuring 7.5" × 4" × 4"
- SMART FEATURES: Built-in business card dispenser, Venmo Code Assist for first-time payers, a secure dashboard for scan and payment tracking
- QUICK SETUP: One-minute activation process - simply scan QR code, add payment methods, business information, and customize settings
- CUSTOMIZED & HANDCRAFTED: Personalize your sign with your business name on top and custom text on the bottom — each piece is handcrafted for a professional, branded look
- Chase: Start a Zelle payment in the Chase app or online banking; Chase says the applicable daily amount appears while you set up the payment.
- Capital One: In the mobile app or online banking, begin setting up a Zelle payment and check the displayed limit.
- U.S. Bank online: Go to Account services → Transaction limits, then open the Zelle limits section.
- U.S. Bank app: Go to Help & services → Know your transaction limits, then open the Zelle limits section.
- Other banks: Check the Zelle payment setup screen or the bank’s current account and Zelle terms. If the amount is not clear, contact the bank that holds the account.
Check again if you recently enrolled, changed the phone number or email on your Zelle profile, are paying a new recipient, or use a business, private-client, or wealth-management account. The applicable amount can depend on those factors.
Why a transfer may be smaller than a published maximum
- Enrollment or profile tenure: Bank of America and Citi publish schedules that distinguish newer and more established enrollment or account profiles.
- Recipient-specific factors: A recently added, unenrolled, new, or inactive recipient may have a lower applicable limit. Chase also assigns a tier to a payment using factors that include the recipient.
- Risk and banking history: Wells Fargo says account and online-banking history, recipient, and recipient payment history can affect limits. Banks may adjust limits or apply additional controls.
- Different time windows: A rolling 24-hour period does not reset in the same way as a calendar day. Citi uses Eastern Time for its daily limit, while Wells Fargo specifies rolling periods.
- Account type: A small-business schedule or a private-client tier may differ from a standard consumer schedule; do not apply one category’s figures to another.
Sending, receiving, and purchase protection
Receiving is not necessarily limited in the same way as sending. Chase says it does not currently limit the dollar amount received each day, and Wells Fargo says it does not limit how much a customer can receive. Those statements do not remove limits imposed by the sender’s institution.
Rank #3

- ONE TAP, MULTIPLE WAYS TO GET PAID – Give customers one simple place to access your payment options. Add Cash App, Venmo, PayPal, Zelle, card checkout links, ACH, wire transfer, Bitcoin, cryptocurrencies and custom payment methods.
- NFC TAP + QR CODE – Customers can tap the sticker with a compatible NFC smartphone or scan the QR code to open your KeeperTag Pay page. No KeeperTag app is required for the person paying.
- UPDATE ANYTIME — NO NEW STICKER NEEDED – Change usernames, payment links, banking instructions or crypto wallet addresses from your KeeperTag account while keeping the same physical NFC & QR sticker.
- BUILT FOR SMALL BUSINESS & EVERYDAY PAYMENTS – Ideal for counters, salons, food trucks, pop-up shops, markets, service professionals, creators, drivers, events, tips and other places where customers need an easy way to access payment information.
- NO BATTERY & EASY TO ACTIVATE – Passive NFC technology requires no charging or batteries. Activate your KeeperTag, add your preferred payment methods and place the 4 x 4 inch sticker where customers can easily tap or scan. KeeperTag provides payment links and information; payments are completed through the selected third-party service.
Zelle is designed for payments to people you know and trust, not as a substitute for a protected retail checkout. Chase’s agreement says authorized Zelle payments do not have purchase protection. Confirm the recipient before sending, especially when a payment is for goods or services.
Quick Recap
Rank #4
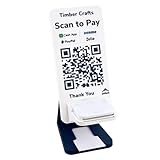
- ALL-IN-ONE DESIGN: Combines a Square card reader holder and a single QR code for Venmo, Cash App, PayPal, and Zelle in one professional point-of-sale display
- PREMIUM CONSTRUCTION: Made from 3/8-inch thick high-impact plastic with precision-embossed text and logos, measuring 10" × 6" × 4"
- SMART FEATURES: Built-in business card dispenser and USB cord pathway for reader power, plus secure dashboard for payment tracking
- QUICK SETUP: One-minute activation process - simply scan QR code, add payment methods, business information, and customize settings
- CUSTOMIZED & HANDCRAFTED: Personalize your sign with your business name on top and custom text on the bottom — each piece is handcrafted for a professional, branded look
What to do if your intended payment exceeds the limit
- Check the exact limit and reset window shown by your bank, including any recipient-specific amount.
- If the payment can wait, check when the applicable daily or rolling window resets; do not assume a rolling 24-hour limit resets at midnight.
- Ask your bank whether it can adjust the limit or whether another payment method is appropriate. Do not assume that splitting a payment will bypass the bank’s controls; limits may aggregate payments across recipients or apply across multiple transactions.
- For a high-value payment, use a method whose protections and transfer limits fit the transaction, and verify recipient details independently.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




