The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →There is no standard number of days you must wait before applying for a mortgage again after a decline. The right time depends on why the lender said no and whether you have addressed that specific issue. First get a clear explanation, then decide whether to ask the original lender to reconsider, apply with another lender, or wait until your finances or documentation have changed.
There is no universal mortgage reapplication waiting period
Federal consumer guidance reviewed by the Consumer Financial Protection Bureau (CFPB) does not establish a required cooling-off period—such as 30, 60, or 90 days—after a mortgage application is declined. A calendar delay by itself does not resolve the issue that led to the decision. A useful point to reapply is when you understand the reason and have taken a relevant step to address it, or when another lender can assess your application under its own criteria.

As an Amazon Associate I earn from qualifying purchases.
This is general guidance for U.S. mortgage applicants, not a guarantee of approval. A lender evaluates an application against its requirements and the details of the loan and borrower. The practical question is not simply “How many days have passed?” but “What has changed, and can I document it?”
Find out why the application was declined
Read the lender’s denial or adverse-action notice, and contact the lender if the reason is unclear. Ask for the specific reason for the decision and, if possible, request the explanation in writing. The CFPB advises denied applicants to ask the lender why. For decisions covered by adverse-action rules, the notice must give the specific reasons or explain how to obtain them.
#1 Best Overall

- Organize all your mortgage paperwork quickly and easily with mortgage folders an indexed divider sets.
- Includes a preprinted form for mortgage applicant's basic information and an inventory checklist to keep track of documents added to the folder.
- Eight dividers per Set
- Contains 10% recycled content, 10% post-consumer material
A general phrase such as “does not meet requirements” may not tell you what to do next. Ask the lender to identify the issue that affected this application, what information it relied on, and what change or documentation could make a future application different. Also ask whether the lender will reconsider the existing file and what its process and timing are. Reconsideration policies and timelines are lender-specific; there is no general timeline established by the CFPB guidance.
Possible areas to clarify include credit history or report information, existing debt obligations, income or supporting documents, down payment or assets, property details, loan terms, or another lender criterion. This is an illustrative set of questions, not a complete or official list of denial reasons. Use the reason in your own notice rather than assuming one of these applied.
Use the reason to decide what to do next
Before sending another application, connect the lender’s explanation to a concrete next step. If the reason is not understood or the underlying information has not changed, a new application may simply present the same unresolved issue. The lender can tell you whether it would consider updated information or whether a new application is needed.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minute- If the notice points to a credit-report issue: Obtain the report from the reporting company named in the notice and check whether the information is accurate. If you find an error, dispute it with both the credit reporting company and the company that supplied the information. Allow the reporting process to address the record before relying on a correction in another application; the CFPB guidance does not specify how long a dispute will take.
- If the concern is income or documentation: Ask which information was missing, unclear, or insufficient and what documents the lender would need to review a future application. Reapply when you can provide the requested, relevant records, rather than assuming that submitting the same file again will change the decision.
- If the concern involves debt or affordability: Ask the lender what part of the file raised the concern and what it would need to reassess. Do not assume a particular payment, balance, or score change will lead to approval; the lender must assess the updated application.
- If the concern relates to down payment, assets, property, or loan terms: Ask which part of the proposed transaction did not meet the lender’s requirements and whether a different documented amount, property, or loan structure would be considered. Do not treat a possible adjustment as approval until a lender evaluates it.
- If the reason appears lender-specific or you want another assessment: You can contact another lender. CFPB guidance says another lender may approve an applicant declined by one lender, but different lender criteria do not make approval certain.
These are decision prompts, not a substitute for the lender’s stated reason. If several issues are listed, ask which ones are decisive and whether each must be resolved before reconsideration.
Check your credit report if credit was involved
If the adverse-action notice says a credit report contributed to the decision, it should identify the credit reporting company and provide score-related information. CFPB guidance from 2024 says you can request a free report from the reporting company named in the notice within 60 days of receiving it. That 60-day period is a deadline for requesting the report described in the guidance; it is not a recommended wait before applying again.
Review the report for information you do not recognize or believe is inaccurate. Dispute inaccurate items with both the reporting company and the information provider, and keep track of what you challenged and the response. If the report is corrected, ask the lender whether it can reconsider the existing application or whether you should submit a new one once the corrected information is reflected. Neither the CFPB guidance nor the notice creates a universal dispute-processing time or a guaranteed score-recovery schedule.
Rank #3

- DESIGNED FOR MORTGAGE PROFESSIONALS: Tailored specifically for lenders and bankers, our mortgage paperwork separators streamline filing, ensuring every stage of the application is organized and accessible.
- STAY ORGANIZED: Keep your documents neatly categorized with 8 distinct, pre-printed color-coded tabs. Enhance your office’s overall organization, perfect for mortgage files and mortgage loan file folders.
- BOOST EFFICIENCY: Our mortgage index sheets feature dual-sided printing and colored tabs for enhanced visibility, allowing quick location of paperwork and boosting productivity.
- PROFESSIONAL PRESENTATION: Enhance your mortgage files with a polished, professional look. The high-quality manila stock and vibrant color-coding offer a visually appealing and functional solution.
- USA MADE: Proudly manufactured in America using high-grade materials, these divider tabs deliver unparalleled quality and longevity for your office filing solutions.
Applying with another lender is an option, not a shortcut guarantee
A decline from one lender does not automatically mean every lender will reach the same decision. CFPB consumer guidance notes that another lender may approve an applicant who was declined elsewhere. That possibility is a reason to ask another lender for an assessment when appropriate—not a promise that a different application will succeed.
Free tools Windows power users keep installed
One-click scans. No signup required.
When approaching another lender, explain the prior decision accurately and share the reason you received. Ask what eligibility criteria and documentation the new lender will use, and whether the issue that affected the earlier application would still matter under its requirements. Compare an actual offer on its terms and total costs once one is available; a rate quote alone does not establish approval. CFPB recommends comparing Loan Estimates when offers are available, but you should first determine whether a lender is prepared to evaluate your application.
If your circumstances have not changed, a new lender may still be useful for learning whether the first decision was lender-specific. But if the first lender identified an unresolved issue, ask the next lender whether it would assess the same facts differently before treating a new application as a solution.
Rank #4

- 25 pt. pressboard cover contains eight 11 pt. Manila dividers (Insurance, Tax & Assessment Receipts, Mortgage, Title Papers, Attorney's Opinion, Appraisal, Credit Reports, Application).
- Front divider has preprinted form for applicants basic information and an inventory checklist.
- Includes a manila jacket for papers that cannot be punched.
- Dividers are held by top position 2" "K" style fastener, which also binds transaction papers.
- Matching color Tyvek tape.
Understand mortgage credit checks and the 45-day shopping window
Applying again may involve a lender checking your credit. CFPB guidance says a lender inquiry typically has a small negative effect on credit scores. It also says multiple mortgage credit checks made within a 45-day window are recorded as one inquiry. CFPB’s 2026 guidance describes this as a mortgage-shopping inquiry rule—not a mandatory 45-day wait after a denial.
The window is about how mortgage inquiries are treated when shopping; it does not mean that every credit-scoring model or every other kind of application is covered in the same way. Do not apply for unrelated new credit on the assumption that it falls within the mortgage-shopping rule. CFPB advises avoiding applications for credit cards, auto loans, or other new credit right before or during the mortgage process, because additional inquiries may lower scores.
Recommended Free Tools
Ask prospective lenders how they handle credit checks while you are exploring options. Keep mortgage shopping focused, and avoid confusing an inquiry-related consideration with the separate question of whether your application is ready.
Best Value
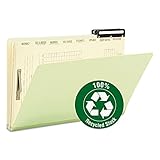
- Sold as 10/Box.
- Front divider has preprinted form for applicants basic information and an inventory checklist.
- Includes a manila jacket for papers that cannot be punched.
- Dividers are held by top position 2" "K" style fastener, which also binds transaction papers.
- Matching color Tyvek tape.
When a specific credit event affects the timing
A decline following bankruptcy, foreclosure, short sale, forbearance, or another significant credit event may raise questions about program-specific waiting rules. The general guidance here does not establish a universal waiting period for any of those events. Requirements can depend on the loan program, the event, the lender, and current underwriting rules.
Ask the lender which program and rule it is applying to your facts, and request the applicable timing and documentation requirements. Do not infer an eligibility date from the general post-decline guidance or from a rule that applies to a different loan program or event.
Consider a housing counselor if you need a readiness review
A HUD-approved housing counselor can help you assess your ability to pay and think through next steps. CFPB identifies counseling as a possible resource, not a requirement for reapplying and not a route that guarantees approval. A counselor may be useful if you want help understanding your financial picture or preparing questions for lenders.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Keep the lender’s explanation central: counseling can support your assessment, but only a lender can say whether it will consider your application under its criteria. You can also ask the lender directly which change would make it appropriate to revisit the file.
A practical sequence before you apply again
- Read the notice. Identify the lender’s stated reason and any credit reporting company or score information listed.
- Ask for clarification. Contact the lender and request the specific reason, what information it relied on, and what would need to change. Ask whether it will reconsider the current file or expects a new application.
- Check the relevant records. If credit contributed, obtain the report from the named company within the 60-day period described by CFPB guidance and dispute any inaccurate information with both the reporting company and information provider.
- Make the relevant change or gather the requested evidence. Focus on the issue actually identified, rather than waiting an arbitrary number of days or changing unrelated parts of your finances.
- Confirm readiness with a lender. Ask the original lender or another lender whether the updated facts and documents are worth submitting now, and what process it will use.
- Compare offers only when available. If a lender offers terms, review the Loan Estimate and total costs; do not treat a rate quote as a final approval.
This sequence does not prescribe a fixed timeline because the underlying issue and lender process determine when a file is worth revisiting. For an error dispute or a lender-specific reconsideration request, ask the relevant company for its own process and expected next step.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




