Free tools Windows power users keep installed
One-click scans. No signup required.
The Federal Reserve does not set your credit-card APR, mortgage quote, or savings APY directly. The Federal Open Market Committee (FOMC) sets a target range for the overnight federal funds rate, and that decision travels through different pricing channels. Variable credit cards usually react relatively quickly through the prime rate; an existing fixed-rate mortgage normally does not change; new mortgage offers follow longer-term bond and mortgage-backed-securities markets; and savings rates may change as banks adjust deposit pricing, but not necessarily immediately or by the same amount.
That distinction matters whenever you are carrying a balance, shopping for a home loan, or deciding where to keep cash. Compare the terms and current offers for your specific account or loan instead of assuming every consumer rate will move with the next Fed announcement.
As an Amazon Associate I earn from qualifying purchases.
What the Federal Reserve actually controls
The FOMC sets a target range for the federal funds rate, the overnight rate banks pay when borrowing reserve balances from one another. The Federal Reserve uses implementation tools to keep the market rate near that range. It does not announce a new APR for every credit card, mortgage, or deposit account.
Monetary policy affects consumer pricing through transmission. A higher target generally makes short-term borrowing more expensive and can restrain demand; a lower target generally reduces short-term rates and can support spending. The FOMC pursues maximum employment and price stability, so its decision reflects economy-wide conditions rather than the needs of an individual borrower or saver.
#1 Best Overall

- Compact Design: Ultra-thin credit card size calculator with a sleek silver and black color scheme.
- Solar Powered: Eco-friendly solar panel allows for portable operation without batteries.
- Touch Screen: Advanced touch screen interface for easy and precise input.
- Versatile: Suitable for business, school, and basic office calculations.
- Lightweight: Weighs only
Short-term and floating-rate products tend to reflect the policy rate quickly. Longer-term rates depend on investors’ expectations for future short-term rates, inflation, growth, and other market conditions. That is why a consumer rate can move before an FOMC meeting, after it, by less than the policy change, or in the opposite direction.
Credit cards: why a Fed move often reaches your APR
The prime-rate link
Most credit-card purchase APRs are variable. Federal Reserve Vice Chair Philip N. Jefferson described the structure on February 19, 2025: “In the credit card market, interest rates are floating and are set as a fixed markup over the prime rate.” By convention, prime equals the upper end of the FOMC’s federal-funds target range plus 3 percentage points.
For example, when the top of the target range rises by 0.25 percentage point, the prime-rate reference used in a typical variable card APR also rises by 0.25 percentage point. A card priced at “prime plus” a margin would therefore have a higher reference component. A cut can work in the other direction.
Recommended Free Tools
Why the change is not identical for every card
Your card agreement determines the margin over prime, the balance categories to which it applies, and the adjustment language. Check the agreement or the periodic statement for:
Rank #2
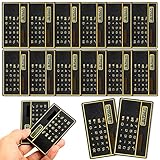
- Package contain: you will get 12 pieces of 8 digits ultra thin calculators, which are suitable for home, office use; You can share them with friends
- Power supply: slim credit card design calculator adopts solar charging design, no battery or power supply needed; It can be applied at any time as long as it gets sufficient light, and it will automatically turn off in the dark, which is very convenient
- Small size: solar power pocket calculator measures about 3.35 x 2.09 inch, compact in size and light in weight, can be easily held in hands, and fit your pockets, pencil cases, backpacks and more
- Quality material: portable mini calculator is made of plastic, light but sturdy, not easy to break; Reliable material with a slim design makes this pocket calculator can serve you for a long time
- Gift choice: the credit card size calculator can be carried easily, which is very suitable for accountants in the office, tellers in the bank and other people who need to calculate frequently
- the index (often prime) and the issuer’s margin;
- whether different margins apply to purchases, cash advances, and balance transfers;
- the date used to calculate the new APR and when the change appears on a statement; and
- any fixed-rate promotional period or other exception.
Do not assume that every card changes on the FOMC announcement date or by precisely the same number of percentage points. The prime relationship makes the direction and likely short-term effect understandable, but the contract controls the actual calculation and timing.
What a cardholder can do
- Identify whether the APR is variable or fixed for each balance.
- Read the rate-and-fee disclosure to find the index, margin, and adjustment schedule.
- Estimate the effect of a possible change in percentage points on the balance you carry. A 0.25-point APR change is 25 basis points; the dollar effect depends on your balance and how long it remains outstanding.
- Compare a lower-cost repayment option only after checking its fees, introductory period, and what happens when that period ends.
Mortgages: separate an existing loan from a new quote
Existing fixed-rate mortgages
Most U.S. mortgages are fixed rate and have longer terms than many other consumer loans. As Vice Chair Jefferson noted, “In the U.S., mortgages are generally fixed rate and have a longer duration than most other forms of consumer borrowing.” If you already have a fixed-rate mortgage, the interest rate in your contract ordinarily stays the same after an FOMC decision. Your principal-and-interest payment changes only through the terms of that loan, not because the target range moved.
Adjustable-rate mortgages
An adjustable-rate mortgage (ARM) can reset, but its contract determines the index, margin, first-reset date, subsequent-reset schedule, caps, and floor. Do not assume an ARM uses the federal funds rate directly. Review the note and disclosures for the index and the next reset date, then ask the servicer how the new rate will be calculated. A policy move may influence an ARM’s index indirectly, but the reset formula and timing govern your payment.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →New purchase and refinance rates
A new 30-year fixed mortgage is priced mainly from longer-term market conditions rather than the current federal funds rate alone. Expected future policy, inflation and growth outlooks, lender pricing, and yields on agency mortgage-backed securities all matter. The Federal Reserve identifies those mortgage-backed-securities yields as an important input to home-mortgage rates.
Rank #3

- Ultra-Thin Design: This calculator features a sleek, credit card-sized design, making it ultra-portable and convenient for on-the-go use.
- Solar Power: Powered by solar energy, eliminating the need for batteries and promoting eco-friendliness.
- Touch Screen: The intuitive touch screen interface provides a smooth and responsive user experience.
- 8-Digit Display: With an 8-digit display, this calculator can handle complex calculations with ease.
- Versatile Functionality: Suitable for business, school, or basic office calculations, this mini calculator is a versatile tool.
Consequently, mortgage rates can fall in anticipation of a future Fed cut, remain high after a cut, or rise after a cut if investors revise their expectations. A mortgage quote is also borrower-specific: credit profile, loan-to-value ratio, occupancy, loan type, points, fees, and the lender’s rate-lock policy affect the offer.
A dated rate figure, with its limits
The Federal Reserve’s July 10, 2026 Monetary Policy Report reported a 6.4 percent contract rate for 30-year fixed-rate conventional home-mortgage commitments through July 1, 2026. That is historical context for the period covered by the report, not an October 2026 quote and not a prediction of the rate you will receive.
How to compare mortgage offers
- Compare the same fixed or adjustable structure and the same term.
- Request the annual percentage rate, note rate, points, lender credits, and itemized fees.
- Ask how long the rate lock lasts, what an extension costs, and what happens if the loan does not close during the lock.
- For an ARM, compare the index, margin, caps, floor, and fully indexed payment rather than focusing only on the initial rate.
- Separate a purchase quote from a refinance quote; the loan purpose and transaction costs can change the pricing.
Savings accounts: policy transmission without a guaranteed pass-through
Deposit rates respond to monetary policy through banks’ funding and competitive decisions. Federal Reserve Governor Adriana D. Kugler explained on April 22, 2025 that changes to the federal funds rate filter through both to rates lenders charge households and businesses and to what financial institutions pay on deposits.
That statement establishes a channel, not a universal formula. The available official material does not establish a current savings-account APY, an immediate adjustment rule, or a fixed percentage of each Fed move that every bank passes through. An institution may reprice accounts at a different time, by a different amount, or not at all for a particular product.
Rank #4

- DUAL PACK: Set of 2 ultra-thin calculators in black and silver finishes, perfect for everyday calculations at work, school, or home
- SOLAR POWERED: Energy-efficient solar panel eliminates the need for battery replacement while providing reliable operation in well-lit conditions
- TOUCH SCREEN: Features responsive 8-digit display with touch-sensitive buttons for smooth, comfortable operation
- COMPACT DESIGN: Credit card sized dimensions make these calculators incredibly portable and easy to store in wallets or card holders
- VERSATILE USE: Ideal for basic calculations in business settings, classroom activities, and general office tasks
What to compare before moving cash
- APY, including whether it is variable and how the institution can change it;
- monthly fees, minimum balance requirements, and whether a promotional APY expires;
- withdrawal, transfer, and access rules; and
- any conditions such as direct deposit, linked accounts, or a required opening balance.
Check the provider’s current disclosure and APY on the day you decide. A higher federal-funds target does not guarantee that your account will pay more, and a lower target does not tell you exactly when or how far your APY will fall.
Current policy snapshot and how to read the dates
The Federal Reserve’s Open Market Operations rate history lists a 25-basis-point increase on September 17, 2026, bringing the target range to 3.75–4.00 percent. That is the latest decision shown in that 2026 history at the time of the cited snapshot; policy decisions can change, so verify the current range when acting.
| Measure | Figure | Date and qualification |
|---|---|---|
| Federal-funds target range | 3.75–4.00% | After a 25-basis-point increase on September 17, 2026; listed in the Federal Reserve’s 2026 target-rate history |
| 30-year fixed conventional mortgage contract rate | 6.4% | Commitments through July 1, 2026, reported in the July 10, 2026 Monetary Policy Report |
These figures are different measures taken on different dates. The mortgage number is not the federal-funds rate and should not be presented as a current October quotation. No savings APY is established by these figures; use a provider’s live disclosure for that comparison.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Clear out junk files and repair common Windows errors3Fix the driver behind crashes, sound loss and screen glitchesWhat a Fed decision means for three common situations
You carry a balance on a variable card
Look first for the card’s prime-based index and margin. A target-rate increase commonly raises the variable APR after the issuer’s contractual adjustment, increasing interest if the balance remains outstanding. A cut can reduce the reference rate, but the reduction may not appear until the agreement’s specified calculation and statement cycle.
Best Value

- Accept all major credit and debit cards and pay one low rate
- No hidden fees and no long-term contracts
- Mobile card reader that accepts payments anywhere & anytime
- Use the free SumUp App on your smartphone or tablet to start accepting transactions
- Simply pay 2.6% +10 per in-person transaction
You already own a fixed-rate home
The FOMC decision normally leaves the contracted rate and scheduled principal-and-interest payment unchanged. A refinance is a new loan decision: compare its complete rate, points, fees, closing costs, and break-even period rather than assuming a policy move automatically makes refinancing worthwhile.
You are shopping for a home
Track longer-term yields, mortgage-backed-securities conditions, lender quotes, and the cost of locking the rate. Waiting for a particular FOMC outcome can backfire because mortgage pricing reflects expectations and can move before the meeting. Compare offers available for your borrower profile and transaction on the same day.
You keep an emergency fund in savings
Review the account’s variable-APY terms and competing offers after policy changes, but also weigh access, fees, minimums, and withdrawal conditions. The highest advertised APY may not be the best fit if its conditions prevent reliable access to your cash.
A practical decision checklist after an FOMC announcement
- Confirm the actual target-range decision and its effective date rather than relying on a headline.
- For cards and ARMs, read the contract’s index, margin, reset or adjustment date, and caps.
- For a fixed mortgage, record that the contract rate is unchanged; evaluate a refinance separately using total costs.
- For a purchase mortgage, collect multiple same-day Loan Estimates and compare rate, APR, points, fees, lock period, and loan structure.
- For savings, check the current APY and all account conditions at several institutions before transferring money.
- Keep the time horizon in view: a short-term policy rate is not a promise about a long-term mortgage quote or a particular deposit yield.
Why rates can move in different directions
The federal-funds target is an overnight policy instrument. Credit cards and other floating-rate credit commonly reference short-term benchmarks, so their response is usually more direct. A fixed mortgage is a long-duration asset priced from expected future conditions and mortgage-backed-securities markets. Deposits are priced by each institution’s funding needs and competition. Because those mechanisms differ, “the Fed cut rates” is not enough information to predict every consumer rate.
The most reliable approach is to identify the reference rate and contractual rule for the product you own, then compare current offers for the product you are considering. Treat the FOMC decision as an important market signal, not as a universal rate-setting event.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




