Recommended Free Tools
Start with the sales invoice register, match each relevant record to GSTR-1, and then use e-invoice and e-way bill data as cross-checks. Tie the return totals to the books and GSTR-3B, investigate each variance at document level, and keep a record of any correction. E-way bills document goods movement; they do not replace the complete outward-supplies records needed for GSTR-1.
What to reconcile—and what each record represents
GSTR-1 is the statement of outward supplies. It includes several kinds of records, such as invoices, credit and debit notes, exports, amendments, and summaries, which do not all belong in the same comparison. The GST Portal supports preparing GSTR-1 online, with the Returns Offline Tool, or through third-party applications via GST Suvidha Providers (GSPs). See the GST Portal help materials for portal guidance.
An e-way bill serves a different purpose: it records information associated with goods movement and transport. Its Part A contains basic invoice-related details; Part B contains transportation details. Use it to cross-check relevant goods transactions, not as a complete sales register.
For each tax period, the practical goal is to compare the same transaction population across the invoice register, GSTR-1, applicable e-invoice data, e-way bills for relevant movements, the sales ledger, and outward-liability figures in GSTR-3B. This is an accounting control, not a single universal reconciliation template prescribed by the sources cited here.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware match#1 Best Overall

- Two-Part Carbonless Invoice Book: Each invoice book has 50 sets of invoices, each with a white/light yellow section, with the yellow section retained in the invoice book to maintain detailed records.
- Consecutively Numbered: Enlarged red 6-digit numbers in the upper right corner of each invoice receipt book help you quickly navigate through your orders.
- Wraparound Divider Flap: A thick folded cardboard divider is integrated into the back of each invoice book for use between each two-part sales order to prevent the written content from rubbing off on subsequent copies of the invoice, resulting in wasted invoices.
- 2 Packs/50 Sets (100 Sets Total): Each invoice book provides 50 sequentially numbered carbonless sets of 2 invoice books for long-term use.
- Customizable Space: Each invoice book for small business has space at the top to add a company seal or sticker.
How to reconcile GSTR-1 with sales invoices
- Freeze the period and source population. Export the period’s sales invoice register and relevant credit and debit notes. Preserve invoice number and date, recipient GSTIN, place of supply, document type, taxable value, tax rate and tax amount, and any amendment reference.
- Classify transactions before comparing totals. Separate B2B and B2C supplies, exports, notes, amendments, exempt, nil-rated and non-GST items, and other categories applicable to the business. GSTR-1 gives different records different table treatments, so compare like with like rather than comparing a mixed ledger total to a single return table.
- Match records invoice by invoice. Check whether each expected record appears in the appropriate GSTR-1 table, and look for duplicates, incorrect invoice number or date, wrong recipient GSTIN or place of supply, and differences in taxable value, rate, or tax. The GST Portal describes invoice-level GSTR-1 details and says validation rejects duplicate supply invoices.
- Check the return summary against the books. Summarize taxable value and tax by supply category and rate. Compare the prepared or filed GSTR-1 totals with the sales ledger and the relevant outward-liability figures in GSTR-3B. Investigate differences rather than adjusting unrelated entries merely to make totals agree.
Useful transaction-level matching fields
- Document type, invoice or note number, document date, and any amendment reference
- Supplier and recipient GSTIN, transaction classification, and place of supply
- HSN where applicable, taxable value, tax rate, and tax amounts
- For relevant goods movements, the associated e-way bill number and transport particulars
These are practical matching fields drawn from the return and IRP field descriptions, not a complete statutory checklist. The appropriate population and treatment depend on the taxpayer, transaction, period, and applicable GST rules.
How to use e-invoice and e-way bill data as cross-checks
Review auto-populated e-invoice details
For applicable e-invoices, the GST Portal says invoice details received from the Invoice Registration Portal (IRP) are updated to specified GSTR-1 tables, including B2B, export, and credit/debit note tables. Portal guidance describes a delay of up to two days and allows taxpayers to download the details in Excel, edit records, and regenerate the summary. Download and compare those details with the invoice register; auto-population does not remove the need to review records. Portal screens and timing can change, so follow the current instructions for the period being filed. See GST Portal help.
Rank #2

- QUALITY INVOICES: Adams Order books provide a professional invoice or customer receipt; a great way to create and maintain a professional image for small businesses and service providers
- 50 TWO-PART CARBONLESS FORMS: Customers get the perforated white top copy; retain the canary and pink copies for your records
- WRAP-AROUND COVER: Fold the back cover between sets to keep invoices neat and legible
- ROOM FOR CUSTOMIZATION: A blank space at top leaves room for your company stamp; a big savings over custom-printed forms
- CONSECUTIVELY NUMBERED: Large 6-digit numbers in the upper right hand corner help you thumb through orders quickly
Compare e-way bill fields for goods movements
For transactions with an e-way bill, compare the associated invoice identity and goods information with Part A, then check the transport particulars in Part B. IRIS IRP describes Part A fields such as invoice number, supplier and recipient GSTIN, and HSN; Part B includes mode, transporter ID, vehicle number where relevant, and distance. Its guidance also says registered e-invoice data is shared with the supplier, GST Portal, and EWB system, and describes generating an e-way bill with an IRN or later from the associated invoice, subject to applicable data and validations. See IRIS IRP guidance.
If a relevant e-way bill record is absent, treat that as an exception to investigate against the movement and the rules that apply to it. The sources cited here do not establish every e-way bill requirement, exemption, or threshold; do not assume every invoice must have an e-way bill.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsRank #3

- QUALITY INVOICES: Adams Invoice books provide a professional invoice or customer receipt; easily customize by using the extra space at the top and your company stamp
- 50-TWO PART CARBONLESS FORMS: Customers get the perforated white top copy; retain the yellow copy for your records
- WRAP-AROUND COVER: Fold the back cover between sets to keep invoices neat and legible
- CONSECUTIVELY NUMBERED: Large 6-digit numbers help you thumb through invoices quickly
- STOCK UP: Each book includes 50 white/canary sets; order several to keep your favorite forms on hand
Use portal imports as a cross-check, not a substitute for review
GST Portal guidance also describes an option to import e-way bill data into relevant GSTR-1 tables. Confirm the current screen and instructions before relying on an import, then compare the imported records with the business’s source documents. Imported or auto-populated data can help surface records, but the business still needs to check completeness and accuracy.
How to investigate mismatches and keep an audit trail
Log each exception against the underlying document and tax period. A useful variance log records the issue, source document, affected period, owner, investigation, and correction made or still needed.
Rank #4
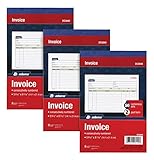
- This value 3 pack of Adams Invoice Books give you 150 two part carbonless invoices with a perforated white customer receipt and yellow duplicates for your records; 3 50-invoice books per pack
- Unique horizontal invoice sheets capture the purchased by and shipped to addresses; a compact 5-9/16 x 8-7/16 page still leaves plenty of room for details on up to 12 items sold
- Wraparound back cover prevents write-through between sets; pull out the perforated white customer receipt and the yellow carbonless duplicates stay behind for your records
- Unique 6 digit invoice numbers help you thumb through orders quickly; blank space up top gives you room for a company stamp—an affordable custom touch
- In value packs with three 50-invoice books for your small business; buy ahead to keep on site or take on the road for pop-up shop sales
- Missing record: Confirm the transaction belongs in the period and category, then check whether it was omitted from the return or is reflected elsewhere, such as an amendment.
- Duplicate: Compare document identifiers and source records; do not count the same supply twice simply because it appears in more than one downloaded view.
- Timing or period difference: Check document dates, period selection, and applicable amendments before treating a timing difference as an incorrect value.
- Wrong classification or party details: Review supply category, GSTIN, place of supply, and applicable rate against the source document and transaction facts.
- Value or tax difference: Recheck taxable value, rate, and tax calculation against the invoice and ledger; keep the reason for any legitimate difference.
- Goods-movement mismatch: Compare the invoice-linked details in Part A with the transport details in Part B and determine whether an e-way bill was required for that movement.
- Credit/debit note or amendment issue: Confirm the original record and the related adjustment are represented in the appropriate period and table.
Retain the invoice and note registers, downloaded portal files, return summaries, relevant e-way bill extracts, and the variance log together by tax period. This makes it possible to trace a reported total back to individual records and explain corrections later.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Can GSTR-1A correct an invoice before GSTR-3B?
The GST Portal describes GSTR-1A as an optional route to add missed information or amend incorrect GSTR-1 records for the same tax period. Its guidance says it is available after filing GSTR-1 or after its due date, whichever is later, and before filing GSTR-3B; changes made through GSTR-1A auto-populate to GSTR-3B. The portal describes the facility as available once for a period. Confirm current eligibility, portal status, and filing instructions before using it. See GST Portal help.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Best Value

- 2 part carbonless forms (White originals, Canary duplicates) for invoicing customers
- Wraparound cover attached to back to place between sets
- Consecutively numbered within each book
- 50 sets per book
- Space at top for company stamp
Where the correction route is available, make the change against the specific source document and preserve the original and corrected details in the audit trail. If GSTR-3B has already been filed, or the portal does not offer the described facility, check current official instructions or consult a qualified tax professional about the appropriate treatment.
Choose a preparation workflow that fits the records
GSTR-1 can be prepared online, with the Returns Offline Tool, or through third-party applications using GSPs. The cited portal materials establish these preparation routes, not comparative software quality or pricing. When evaluating a workflow, check whether it can handle the business’s transaction categories, identify exceptions, preserve downloadable records, support corrections before filing, and work with the accounting records used to produce the invoice register.
Rules and portal features can vary by taxpayer, transaction, and return period. In particular, the historical e-invoice applicability timeline reproduced by IRIS IRP cites a ₹5 crore aggregate annual turnover threshold under Notification No. 10/2023, effective 1 August 2023; that dated item should not be treated as a complete statement of current applicability. IRIS IRP also reports a 30-day reporting restriction from 1 April 2025 for specified e-invoices of taxpayers with AATO of ₹10 crore or more. Because this has compliance consequences, verify the current underlying GST advisory and applicable instructions before relying on it. See IRIS IRP.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




