The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →High-frequency trading (HFT) is a technology-intensive form of automated trading that generates and manages orders at high speed. It is not a trading strategy on its own: systems built for HFT can implement strategies such as market making or arbitrage. Speed does not guarantee a profit, and the legal meaning of HFT depends on the jurisdiction, instrument and activity involved.
What is high-frequency crypto trading?
HFT uses computer systems to process market information and determine, send or manage orders with little or no human intervention for individual orders. People often describe it as trading in milliseconds, but speed alone does not capture the full concept. Under the European Union’s MiFID II rules for financial instruments, HFT is characterized by three features: infrastructure designed to minimize latency, automated determination of orders without human intervention, and high intraday rates of order, quote or cancellation messages. The definition and its scope are set out in MiFID II Article 4; it is not a universal label for every crypto trader or bot.


MiFID II distinguishes algorithmic trading from systems that only route orders or handle post-trade processing without determining trading parameters. Its recital describes HFT systems as potentially establishing and liquidating positions quickly, generating high turnover and order-to-trade ratios, and ending the day close to flat. These are descriptive characteristics, not a separate checklist that automatically classifies every crypto system. The recital also says HFT typically uses traders’ own capital and sophisticated technology to implement established strategies. In its words, HFT “rather than being a strategy in itself is usually the use of sophisticated technology to implement more traditional trading strategies such as market making or arbitrage.” See MiFID II Recital 61.
How does an HFT system work?
At a high level, an automated trading system takes in market information, applies programmed decision rules and initiates or manages orders. A system may also respond to changes in prices, available liquidity or its own open orders. In an HFT context, the system and its connections are designed to handle these tasks quickly, but the exact setup varies by venue and strategy.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsProfessional infrastructure can include low-latency network connections, proximity hosting or co-location—placing systems near a venue’s matching infrastructure—and direct electronic access. Those are examples of latency-focused infrastructure in the MiFID II definition, not a shopping list or a requirement for an ordinary investor. The sources cited here do not establish a current exchange API specification, a reliable latency benchmark, or a particular provider’s suitability.
HFT is a way to implement a strategy, not a strategy itself
Market making
A market maker supplies bids and offers, seeking to facilitate trading between buyers and sellers. Automated systems can update or manage those quotes as conditions change. HFT technology can be used for this purpose, but that does not establish that a particular market maker earns a profit or that the approach is suitable for an individual trader.
Rank #2
Arbitrage
Arbitrage seeks to exploit price differences—for example, between markets or related assets. Automated systems can detect and act on a difference quickly, though execution, fees, liquidity and the possibility that prices move before orders complete all matter. The cited sources identify arbitrage as a traditional strategy that HFT technology can implement; they do not establish that any opportunity is available or profitable now.
Centralized platforms and on-chain DEXs have different trading mechanics
A centralized trading platform has an operator and a platform order system. On an on-chain decentralized exchange (DEX), transactions are submitted to a blockchain and processed in blocks. Depending on the system, pending transactions may be visible before execution. That difference changes how latency and transaction ordering can affect a trade; the two settings should not be treated as interchangeable.
Rank #3
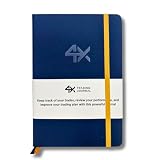
- BUILT FOR YOUR MARKET, FUTURES, STOCKS, FOREX, OPTIONS & CRYPTO: 4X is a mindset and process journal, not a strategy tool tied to one instrument. The plan, the trade log, the deep dive and the weekly review work the same whether you trade ES, EURUSD, SPY or BTC. Traders use it across all five markets every day.
- THE 2026 EDITION, REBUILT FROM TRADER FEEDBACK: Same trusted system, better in every way. An extra daily page for more room to log the session. Weekly reviews now grouped with each week's trades, so no more flipping back and forth. Crisp, darker print that's easy on the eyes after hours on a screen. A Quick-Start QR that scans straight to step-by-step instructions.
- NOT A NOTEBOOK, A COMPLETE 12-WEEK SYSTEM: Start with a one-time 9-part Trading Plan (your market, setups, risk rules and discipline checklist). Then twelve identical weeks: five Daily Logs, five Deep Dive trade pages, and a two-page Weekly Review. 189 guided pages, roughly 80 trades. Guided prompts walk you through every step. You never stare at a blank page.
- RATE YOUR EXECUTION, NOT YOUR RESULT: Your platform tracks the P&L. Nothing tracks the why. Log energy, sleep and mindset before the open; grade every trade A to F on whether you followed your plan, not on whether it won; then face the pattern every weekend with START / STOP / IMPROVE / CONTINUE. That review habit is the edge. You're 42% more likely to hit a goal you've written down.
- BUILT TO LAST, ARRIVES GIFT-READY: Vegan-leather hardcover, 100gsm bleed-resistant paper, two ribbon markers and an elastic closure band. Bound to lay flat so you're not fighting the spine while you write. 189 pages, 5.75" x 8.5", carries in a bag. Ships in a premium gift box: the gift every trader in your life actually wants.
| Comparison point | Centralized trading platform | On-chain DEX |
|---|---|---|
| Trading and order path | An operator runs the platform’s order system. | Transactions are submitted to a blockchain and processed in blocks. |
| Visibility and ordering | The cited sources do not establish a universal order-visibility or latency model across platforms. | Pending transactions can be visible before execution; transaction ordering and processing latency can create opportunities for front-running. |
| Rules discussed here | MiCA Article 76 sets requirements for covered crypto-asset trading platforms operated by crypto-asset service providers within its scope. | The cited MiCA platform requirements should not be assumed to apply to every protocol or participant. |
| Fees, liquidity and custody | These depend on the specific platform and are not established as general comparisons by the cited sources. | These depend on the specific protocol and transaction; the cited sources do not establish a general comparison. |
A 2020 paper by Zhou, Qin, Torres, Le and Gervais studied front-running and sandwich attacks in a particular historical Uniswap setting. A sandwich attack places one transaction before a target trade and another after it, seeking to benefit from the resulting price movement. The paper’s modeled result was “Over several thousand USD in daily revenue in the paper’s modeled setting — Zhou, Qin, Torres, Le, and Gervais, 2020.” This is a historical model result, not a current market statistic, a forecast or an endorsement. Read the paper’s scope and date at High-Frequency Trading on Decentralized On-Chain Exchanges, posted September 29, 2020.
Potential benefits and failure modes
MiFID II’s recitals describe potential benefits of trading technology, including broader participation, increased liquidity, narrower spreads, lower short-term volatility and better execution. They also describe risks. These are the Directive’s account of possible effects, not guaranteed outcomes for a particular crypto market or trading system. See MiFID II Recitals 60–65.
- Venue overload: large volumes of messages or orders can put pressure on trading systems.
- Erroneous or duplicate orders: a software fault or configuration error can send unintended orders repeatedly or at the wrong parameters.
- Malfunctions and rapid reactions: automated systems can fail or respond to events in ways that amplify volatility, particularly when a market is already under stress.
- Misuse: automated techniques can be used for prohibited conduct, which is one reason regulators focus on controls and surveillance.
What safeguards do EU crypto-asset platform rules require?
MiCA Article 76 applies to crypto-asset trading platforms operated by crypto-asset service providers within the Regulation’s scope. It requires covered operators to maintain systems that are resilient and have capacity for peak order and message volumes, support orderly trading during severe market stress, and reject orders that exceed predetermined price or volume thresholds or are clearly erroneous. The Article also addresses testing, business continuity, market-abuse detection or prevention, order records for competent-authority access, and publication of specified order-book and transaction information subject to its terms. See MiCA Article 76.
These are duties for covered platform operators, not direct requirements for every trader and not a blanket rule for every decentralized protocol. Whether a particular asset, venue or activity falls within a rule depends on its legal and factual circumstances.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
What should an individual investor take from this?
Do not equate an ordinary trading bot with HFT, or assume a fast connection makes a strategy profitable. HFT combines automated order decisions with particular infrastructure and message-rate characteristics; relevant legal classifications are narrower and jurisdiction-specific. Before assessing a venue or activity, consider the market-data and order-entry path, transaction-ordering mechanics, fees and liquidity, custody model, and the rules that apply to the instrument, venue and jurisdiction. These are comparison factors, not a ranking or recommendation.
The cited materials do not establish a current market-wide HFT statistic, average crypto trading latency, profitability rate or performance comparison among venues. MiFID II is an EU rule for financial instruments, and MiCA Article 76 has a defined scope. Check current law and authorization requirements for the particular activity and location rather than treating either provision as a global classification.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




