Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11If your card issuer said no to a lower APR, ask what would qualify for a future review—but first find out whether you were denied a discretionary request or whether the issuer raised your rate. Those are different situations: you generally cannot force an issuer to lower your rate just by asking, but certain rate increases have federal review or reinstatement protections. If you cannot afford the minimum payment, ask for hardship help right away.
First, identify what the issuer denied
A request for a lower APR is not the same as challenging a rate increase. The right next step depends on why the rate is high, which balance it applies to, and whether you can keep up with payments.
- Discretionary rate reduction: You asked the issuer to lower your existing APR, and it declined. There is no general guarantee that an issuer must approve this request.
- Rate increase: The issuer raised your APR. Ask when it changed, which balances or transactions it affects, and what notice the issuer sent. Federal protections depend on the circumstances; they do not prohibit every rate increase.
- Payment hardship: You cannot afford the minimum or expect to miss a payment. Ask about hardship assistance rather than treating this only as a rate-negotiation issue.
What to do after a discretionary request is denied
Call the issuer and ask what would qualify
Call the customer-service number on your card. Ask why the request was declined, what criteria could support a future review, and whether a temporary or permanent reduction is available. The issuer may explain its process, but it is not required to approve a reduction simply because you ask.
If you plan to ask again, clarify whether the issuer will consider a new request after a specific change in your circumstances or account. Do not assume there is a standard waiting period; ask the issuer what applies to your account.
Free tools Windows power users keep installed
One-click scans. No signup required.
#1 Best Overall

- DUAL PACK: Set of 2 ultra-thin calculators in black and silver finishes, perfect for everyday calculations at work, school, or home
- SOLAR POWERED: Energy-efficient solar panel eliminates the need for battery replacement while providing reliable operation in well-lit conditions
- TOUCH SCREEN: Features responsive 8-digit display with touch-sensitive buttons for smooth, comfortable operation
- COMPACT DESIGN: Credit card sized dimensions make these calculators incredibly portable and easy to store in wallets or card holders
- VERSATILE USE: Ideal for basic calculations in business settings, classroom activities, and general office tasks
Get the details in writing
Record the date of your call, the representative’s explanation, and any next steps or review date. If the issuer offers a different arrangement, ask for its APR, duration, fees, payment requirements, and any effect on the account before agreeing.
If your APR was raised, check the notice and protections
Ask the issuer when the increase took effect, whether it applies to new purchases or an existing balance, and what notice it provided. The CFPB’s rate-increase guidance, last reviewed in September 2022, describes protections for certain increases, with results depending on the reason for the change and the affected balance or transactions.
Rank #2
- Simple to use
- Calculates the true cost of owning a Credit Card
- Multiple APR lines for Cash, Goods, Balance Transfers etc
- 2 Modes simple and Advanced
- designed with the end user in mind
- In circumstances described by the CFPB, an issuer must give 45 days’ advance notice before an increased rate applies to new purchases after the account’s first year.
- Certain rate increases must be reviewed at least every six months. If the review meets the stated conditions, the issuer may have to reduce the rate.
- For certain increases triggered by a payment more than 60 days late, the old rate may need to be reinstated after six consecutive on-time minimum payments, subject to the applicable conditions.
These are not blanket rules for every rate change. Check the notice and your card agreement, and ask the issuer which rule it believes applies. The CFPB also explains that significant account-term changes generally require 45 days’ advance notice, subject to exceptions; opting out of some changes can close the account while leaving the balance payable. See its change-in-terms guidance, last reviewed in January 2024.
If you cannot afford the minimum, ask for hardship help
The CFPB advises: “Contact your credit card company immediately.” Explain why the payment is unaffordable, how much you can pay, when you expect regular payments might resume, and what change you are requesting and for how long. You can ask about a lower interest rate, reduced payment, or postponed payments, but the issuer may not offer a particular plan or approve your request.
Recommended Free Tools
Rank #3
- Simple to use
- Calculates the true cost of owning a Credit Card
- Multiple APR lines for Cash, Goods, Balance Transfers etc
- 2 Modes simple and Advanced
- designed with the end user in mind
Before accepting an arrangement, confirm the payment amount, duration, interest rate, fees, and whether the account will be restricted or closed. The CFPB’s guidance on trouble paying credit-card bills, last reviewed September 2, 2026, recommends contacting the issuer and explaining your situation.
When a CFPB complaint may make sense
If you believe the issuer mishandled a rate-change notice or did not follow an applicable protection, or it will not work with you during a hardship, you can submit a complaint through the CFPB complaint process. The CFPB’s complaint categories include credit-card companies that will not work with consumers during hardship, including on lower interest, lower payments, or postponed payments. A complaint is a route to raise the issue, not a promise that the issuer will grant the requested terms.
Rank #4

- Ultra-Thin Design: This calculator features a sleek, credit card-sized design, making it ultra-portable and convenient for on-the-go use.
- Solar Power: Powered by solar energy, eliminating the need for batteries and promoting eco-friendliness.
- Touch Screen: The intuitive touch screen interface provides a smooth and responsive user experience.
- 8-Digit Display: With an 8-digit display, this calculator can handle complex calculations with ease.
- Versatile Functionality: Suitable for business, school, or basic office calculations, this mini calculator is a versatile tool.
Avoid paid rate-reduction promises
Contact the issuer yourself before paying anyone to negotiate. The FTC says there are no special tricks or connections that let a company guarantee a lower rate. Its April 2026 alert warns against unexpected calls offering to lower card interest and says to decline them. The FTC’s debt-relief scam guidance also says debt-relief providers may not charge upfront fees before providing help.
If you need help beyond the issuer, credit counseling is another option to consider. Ask about fees and services before enrolling; do not assume a counselor can secure a particular APR or payment arrangement.
Quick Recap
Best Value
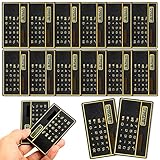
- Package contain: you will get 12 pieces of 8 digits ultra thin calculators, which are suitable for home, office use; You can share them with friends
- Power supply: slim credit card design calculator adopts solar charging design, no battery or power supply needed; It can be applied at any time as long as it gets sufficient light, and it will automatically turn off in the dark, which is very convenient
- Small size: solar power pocket calculator measures about 3.35 x 2.09 inch, compact in size and light in weight, can be easily held in hands, and fit your pockets, pencil cases, backpacks and more
- Quality material: portable mini calculator is made of plastic, light but sturdy, not easy to break; Reliable material with a slim design makes this pocket calculator can serve you for a long time
- Gift choice: the credit card size calculator can be carried easily, which is very suitable for accountants in the office, tellers in the bank and other people who need to calculate frequently
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




