Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →An unauthorized credit-card charge in India does not automatically make you responsible for the full amount. Under the Reserve Bank of India’s customer-liability framework, the result depends on whether the bank, the cardholder, or neither was at fault—and, in third-party breach cases, how quickly the cardholder reported the transaction after the bank communicated it. Report it immediately and keep proof of when you did.
When are you liable for a credit card transaction you did not authorize?
The RBI framework separates unauthorized electronic transactions into three broad cases: a bank’s fault, the customer’s negligence, or a breach elsewhere in the system when neither the bank nor customer is at fault. For the third-party case, the reporting window determines whether liability is zero or capped. If customer negligence caused the loss, the rules treat losses before and after notification differently.
As an Amazon Associate I earn from qualifying purchases.
The central source is the RBI’s circular RBI/2017-18/15, dated 6 July 2017. It covers scheduled commercial banks, small finance banks, and payments banks. A separate RBI circular dated 14 December 2017 addresses co-operative banks. Do not assume one circular by itself settles the rules for every card issuer or every dispute: issuer type, the applicable RBI direction, and the issuer’s Board-approved policy can matter.
| What caused the unauthorized transaction? | When you report it | Customer liability under the stated framework |
|---|---|---|
| Contributory fraud, negligence, or deficiency by the bank | Reporting time does not change the stated outcome | Zero |
| Deficiency lies neither with the bank nor the customer, but elsewhere in the system | Within three working days of the bank communicating the transaction | Zero |
| Same third-party/system case | More than three and up to seven working days after communication | Limited to the transaction value or the applicable cap, whichever is lower |
| Same third-party/system case | After seven working days | Determined under the bank’s Board-approved customer-liability policy |
| Loss results from the customer’s negligence, such as sharing payment credentials | Before the customer notifies the bank | Customer bears losses up to notification |
| Loss results from the customer’s negligence | After the customer notifies the bank | Bank bears losses occurring after notification |
The bank has the burden of proving customer liability. The circular states: “The burden of proving customer liability in case of unauthorised electronic banking transactions shall lie on the bank.” That does not mean every disputed charge is automatically reversed; it means the bank must establish the basis for treating the customer as liable under the applicable rules.
#1 Best Overall

- SLIM BODY WITH LARGE CAPACITY:This mens wallet measures 4.3 x 3.2 x 0.6 inches and can hold 14 cards and 10+ bills. The slim design makes it perfect for fitting into all kinds of pockets, offering great portability.
- QUICK CARD SLOTS & CASH SLOT:On the front of this minimalist wallet for men, there are 2 quick-access card slots for easy retrieval while traveling or shopping. The cash slot allows you to quickly access and store cash without having to fold bills multiple times.
- DOUBLE ID WINDOWS:This card wallet for men specifically features 2 clear ID windows for holding ID cards and driver's licenses, enabling fast and convenient access to your information.
- FID BLOCKING:This rfid wallet is lined with a special RFID-blocking material that shields against 13.56 MHz and higher frequency signals. This prevents unauthorized scanning and data theft from your chips, offering comprehensive protection for your identity and financial information.
- PERFECT GIFT IDEA FOR MEN:Crafted with high-quality materials, this leather wallet for men combines practicality for mens everyday needs, making it an ideal gift for birthdays, anniversaries, Christmas, Valentine’s Day, Father’s Day, or other special occasions.
How the reporting deadline and liability caps work
The clock begins with the bank’s communication
For the third-party/system-breach rules, count from the date the bank communicates the transaction to you—not simply from the transaction date. Exclude the day you received that communication. Working days are counted according to the schedule of the bank’s home branch. A weekend or holiday may therefore affect the count; use the relevant branch schedule rather than assuming that every calendar day counts as a working day.
For example, if a bank communicates a transaction on a Monday, Monday is excluded. The next applicable working day is counted as day one. The exact deadline depends on the home branch’s working-day schedule. The example illustrates the counting method, not a promise that every branch follows the same holiday calendar.
Three working days, four to seven, and after seven
If the deficiency is outside both the bank and customer, notifying the bank within three working days of its communication results in zero customer liability under the 2017 framework. Reporting on the fourth through seventh working day changes the outcome: the liability is limited to the transaction amount or a card-limit-based cap, whichever is lower. A report later than seven working days is handled under the bank’s Board-approved policy, which the bank must make public and communicate to customers.
Rank #2
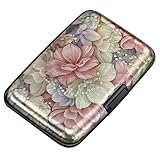
- This Credit Card Holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The Size is 4.33 x 2.95 x 0.73 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches Safely and Securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 9 credit cards or more than 21 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
| Credit-card limit | Maximum cap for a report made four to seven working days after communication |
|---|---|
| Up to ₹5 lakh | ₹10,000 |
| Above ₹5 lakh | ₹25,000 |
The cap is not a flat charge or an automatic amount owed. The framework limits liability to whichever is lower: the disputed transaction value or the applicable cap. These figures apply to the specified third-party/system case and four-to-seven-working-day reporting window; they are not a general cap for every kind of fraud or every delay.
Bank fault and customer negligence do not follow the same timing rule
When the unauthorized transaction involves contributory fraud, negligence, or deficiency by the bank, the stated customer liability is zero regardless of when the customer reports it. Conversely, where the loss resulted from customer negligence—sharing payment credentials is the RBI’s example—the customer bears losses until notifying the bank. Losses after notification are borne by the bank. That is why immediate notification matters even when you are unsure how your information was obtained.
What to do as soon as you spot an unauthorized charge
- Contact the issuer through its official 24-hour reporting channel. Use the number or reporting method published by the issuer, and ask it to block the card or otherwise stop further unauthorized use. RBI directions require issuers to provide round-the-clock reporting means and take immediate steps after receiving a report.
- Submit a formal unauthorized-transaction dispute. Identify the transaction date, amount, and merchant descriptor, and state plainly that you did not recognize or authorize it. Ask for a complaint number and written acknowledgement. The RBI directions call for complaint acknowledgement and reporting arrangements that record message and response times.
- Record the key times and preserve the evidence. Keep the complaint number, alert messages, the relevant statement, and correspondence with the issuer. Note when the bank first communicated the transaction and when you reported it. These records can help establish the reporting window, but they do not guarantee a particular decision.
- Follow the issuer’s published grievance escalation process if its response is unsatisfactory. The RBI directions establish a grievance structure and escalation matrix. The sources cited here do not establish current RBI Ombudsman eligibility, waiting periods, or filing instructions, so check the applicable official process before relying on a particular deadline or escalation route.
When reporting by phone or app, save whatever confirmation is available and follow up in writing if the issuer provides a formal dispute channel. The practical objective is to make the issuer aware promptly, stop further use, and retain a dated record of the complaint—not to delay reporting while assembling a perfect explanation.
Rank #3
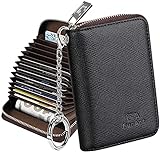
- Special Design: Multi-color optional and wear-proof classic business card holder looking.
- Plenty of Space: 16 card slots only measuring 4.1" x 3.0" x 1.1", including 13 credit card slots, 2 cash slots
- Protect Information Leakage: Prevents your vital information/cards from unnoticed scan with 2 outer layers RFID blocking materials.
- Extra Key Chain & Portable: Extra corns with key chain for your keys or lanyard. Portable use for shopping, traveling, etc.
- Great Gift: Practical compact wallet is the perfect gift. Give a thoughtful surprise to Men/Women on birthdays, holidays, celebrations, or any special occasion (e.g. Valentine's Day, Christmas, etc.).
What happens after you report the charge?
Provisional credit and investigation are separate steps
For a case of zero or limited customer liability, the bank must provide a shadow reversal within 10 working days of notification. The RBI describes this as a credit of the amount involved to the customer’s account without waiting for an insurance claim to be settled. A shadow reversal is provisional; it is not the same thing as the bank completing its investigation or making its final liability determination.
The bank must resolve the complaint within its approved timeline
The bank must resolve the complaint and determine liability within the timeline approved by its Board, subject to a maximum of 90 days. If it cannot resolve the complaint or determine liability within 90 days, the prescribed compensation is payable. For credit cards, the customer must not bear an additional interest burden under the stated directions. Ask the issuer to explain how it is handling disputed amounts while the case is open, and keep its explanation with your records.
These deadlines concern different stages: the 10-working-day period applies to the shadow reversal in zero- or limited-liability cases, while the 90-day maximum applies to resolution and liability determination. A provisional entry should not be mistaken for a final decision, and a pending investigation does not remove the need to retain your complaint records.
Rank #4
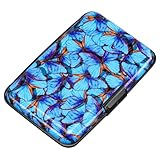
- This credit card holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The size is 4.33 x 2.95 x 0.75 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches safely and securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 10 credit cards or more than 20 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
What if you shared an OTP, PIN, or card details?
Sharing payment credentials can be relevant because the RBI framework places losses resulting from customer negligence on the customer until the bank is notified. Once the bank is notified, subsequent losses are borne by the bank under the stated rule. The facts of a particular transaction still matter: do not assume that merely receiving an OTP, or being targeted by a scam, proves that you shared credentials or makes you liable. Report the transaction and describe accurately what happened.
If you did share information, tell the issuer what you shared, when, and through what channel. If you did not, say so. Preserve relevant messages or other records rather than deleting them. The bank bears the burden of proving customer liability, but a clear, timely account can help the issuer assess the sequence of events.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Which RBI rules apply to your issuer?
The 6 July 2017 circular is the central source for the liability thresholds described here and addresses scheduled commercial banks, small finance banks, and payments banks. It also says it supersedes specified portions of the earlier 2015 card-operations Master Circular for scheduled commercial banks. Co-operative banks are addressed in a separate RBI circular dated 14 December 2017, so their applicable direction should be checked separately.
Best Value

- RFID Blocking Technology: This credit card holder is made of aluminum shells and ABS plastic, designed with RFID-blocking technology to help protect your credit, ID, debit, and driver's license cards from unauthorized scanning
- Slim Compact: Slim and compact design measures 4.3 x 3 x 0.86 inches, ideal for front pockets or purses
- Card Organizer: With 7 accordion-style slots, this wallet can hold up to 10 standard credit cards or over 20 business cards
- Artistic Expression: Features a variety of artistic designs on the aluminum shell, inspired by famous paintings, flowers, and animals, to complement your personal style
- Thoughtful Gift Idea: Makes a thoughtful gift for any occasion, combining functionality and style
RBI’s Credit Card and Debit Card Issuance and Conduct Directions apply to issuing banks and NBFCs. An official amendment dated 7 March 2024 updated the 2022 directions and took effect that day; the amendment information available here does not indicate a change to the 2017 customer-liability framework. Because issuer type and the bank’s policy can affect the process—especially after seven working days—check the issuer’s current customer-liability policy and your card terms rather than assuming every card follows an identical dispute procedure.
How to assess a disputed charge without guessing the outcome
- Identify the likely fault category. Ask whether the case concerns bank fault, customer negligence, or a third-party/system breach. The category changes which reporting rule applies.
- Establish the communication and report dates. Find the bank’s first communication of the transaction and your earliest report to the issuer. For the third-party case, exclude the communication-receipt day and use the home branch’s working-day schedule.
- Apply the correct timing band. A third-party case reported within three working days carries zero liability under the stated rule; four to seven working days invokes the lower-of-transaction-value-or-cap calculation; later reporting goes to the bank’s Board-approved policy.
- Check issuer type and policy. Confirm which RBI direction applies and review the bank’s published customer-liability policy, particularly if the report was after seven working days.
- Track the bank’s handling separately from the final liability. Record the notification date for the 10-working-day shadow-reversal period where zero or limited liability applies, and track the complaint against the issuer’s approved resolution timeline, capped at 90 days.
This framework explains how liability is allocated; it cannot decide a particular dispute without the transaction facts and applicable issuer policy. If a charge is unfamiliar, report it immediately rather than waiting to establish which category the issuer will ultimately find applies.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




