Recommended Free Tools
Banks and card issuers can change some account terms, but the rules depend on the country, product and type of change. A UK arranged overdraft, a US debit-card overdraft service and a credit-card account do not follow one shared notice or consent rule. To understand what a change means for you, compare the provider’s dated notice with your existing terms and check what changed, when it takes effect and whether you need to act.
Start with the country and product
“Overdraft” can mean borrowing arranged with a current-account provider, borrowing without an agreed limit, or a bank’s decision to pay an ATM withdrawal or one-time debit-card transaction when an account lacks funds. A credit card is a separate type of credit account. Their legal protections differ, so identify the country, account and transaction before interpreting a notice.
As an Amazon Associate I earn from qualifying purchases.
- UK arranged or unarranged overdraft: FCA rules and guidance address overdraft pricing and charges.
- US debit-account overdraft service: Regulation E’s opt-in provision concerns fees for paying ATM and one-time debit-card transactions; it is not a universal opt-in rule for every overdraft or credit line.
- US credit card: Regulation Z sets disclosure requirements for specified changes and generally restricts certain increases, subject to exceptions.
What a UK overdraft terms change may involve
UK FCA rules provide for overdraft charges to be treated as interest rates and allow specified fee-free amounts or buffer zones when the rule’s conditions are met. FCA policy moved overdraft pricing toward a simple annual rate. The FCA’s account of the reforms says firms had to stop charging fixed fees for overdraft borrowing, charge no more for unarranged than arranged overdrafts, use one annual interest rate and advertise overdrafts using a representative APR. These are established rule and policy context, not a newly announced 2026 change. Check the current FCA Handbook wording before relying on it for a particular account.
When you receive a UK overdraft notice, compare the annual interest rate, how interest is calculated, any fee-free amount or buffer, and how the terms apply to arranged and unarranged borrowing. Check whether the provider describes the rate as variable and whether the notice explains when the new terms begin.
#1 Best Overall

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
The FCA reported that 15 million people used overdrafts in 2021, including 11 million arranged-overdraft users and 6 million unarranged-overdraft users; these user counts may overlap. In a 2023 publication, the regulator said rule changes had produced “nearly £1 billion” in aggregate customer savings. That is the FCA’s rounded headline claim, not a prediction of what any individual account holder will save.
What the 2026 UK reform announcement does—and does not—establish
On 18 May 2026, HM Treasury announced plans to modernize the Consumer Credit Act. The government said consumers using credit cards, loans and overdrafts are expected to benefit from clearer information about costs and key terms. This describes a reform direction; the announcement alone does not establish the final obligations, commencement date or what a particular provider has already changed. Do not treat it as evidence that every bank has issued new terms.
Rank #2

- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
US overdraft opt-in: the transactions covered
For covered overdraft services, Regulation E requires a written or agreed electronic notice, a reasonable opportunity to opt in, affirmative consent and confirmation of consent before a fee is assessed for paying an ATM or one-time debit-card transaction. The provision is specific to those transactions and has scope and exceptions. It should not be read as requiring opt-in for every overdraft, check, recurring debit or credit-line arrangement.
If a US bank charges an overdraft fee on an ATM withdrawal or one-time debit-card purchase, check the account records and the bank’s notice for evidence of consent. If the charge concerns another transaction type, do not assume the same opt-in provision decides whether the fee is permitted.
Rank #3

- 💳 QUICK ACCESS & LARGE CAPACITY HOLD UP 1-12 CARDS: This mens wallet designed with enhanced enjection mechanism button to pop up cards quickly. The aluminum card holder holds 4-6, depends on the number of embossed cards, and the expandable metal backplate holds 5-6 additional cards. The actual capacity depends on the card thickness.
- 💳 ULTRA THIN PROFILE (SLIM WALLET FOR MEN): The minimalist tactical wallet is very thin and can be carried comfortably in a pocket. The aluminum cardholder size is 3.9*2.5*0.5in,weight only 2.6oz. And expandable backplate designed for additional storage. Ditch the bulk, less is more.
- 🔒 RFID & NFC BLOCKING: This smart wallet use advanced aluminium technology to protect your cards from unauthorized and contactless scanning. Stop thieves from cloning your bank cards and prevent data theft.
- 💳 KEEP CARD TIGHTLY: Our pop up wallet with inside silicone strip that keeps your cards to be held tightly compared with normal felt. No worry cards will fall out.
- 🎁 PERFECT PRESENT IDEA: Our minimalist wallets packed with a pretty box. Aluminum wallet for men is a great present for boyfriend, brother, son, husband, dad, or your male friends on christmas, birthdays, anniversaries, and father's Day.
US credit-card changes: notices and limits
Regulation Z, section 1026.9, sets subsequent-disclosure requirements for specified changes to credit-card terms. Section 1026.55 generally limits increases in APRs, fees or charges unless an exception applies. The applicable notice period and protection depend on the change and account facts; not every change has the same notice rule, and an issuer cannot freely change every disclosed term.
Read the notice to identify the exact term affected, such as an APR or fee, and the date it takes effect. Also check whether the change applies to an existing balance, future transactions, or both, and whether the notice describes an exception or a customer option. The notice and governing rule—not the phrase “terms and conditions changed” by itself—determine what happens next.
Rank #4
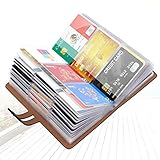
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
How to compare a provider’s old and new terms
- Confirm the jurisdiction and product. Note the country, provider, account type and whether the notice concerns an arranged overdraft, an unarranged overdraft, a debit-account overdraft service or a credit card.
- Record the dates. Separate the notice date from the effective date. Look for any response deadline.
- Mark the precise change. Compare the old and new interest rate or APR, fees, fee-free amount or buffer, and the transactions or balances to which each applies. Include variable-rate wording if present.
- Check who and what are affected. Establish whether the change covers your account, existing balances, future transactions, or only a particular use of the facility.
- Look for required action and options. Check whether the provider asks for consent or offers an opt-out, closure or repayment option. Do not assume an option exists unless the notice or account terms state it.
- Keep the evidence. Save the dated notice and the previous terms so you can identify the change and refer to the provider’s exact wording if you contact it.
What to do if the notice is unclear
Ask the provider to identify the old term, the replacement term, the effective date, the affected transactions or balances, and any action or deadline that applies to your account. For a US debit-card overdraft fee, ask whether it concerns an ATM or one-time debit-card transaction and what consent record the provider relies on. For a credit-card APR or fee change, ask which Regulation Z disclosure or exception the provider says applies if the notice does not explain the basis.
The title of a notice cannot establish which customers are affected or what a specific bank has changed. Those details require the provider’s dated notice and the applicable account terms.
Quick Recap
Best Value

- QUICK CARDS ACCESS: This minimalist wallet for men features a smooth pop-up mechanism. Just press the side button, and the cards slide out in a stepped layout for easy access.
- SLIM BODY WITH LARGE CAPACITY: Despite being slim at only 0.6 inches thick, this card wallet for men can hold 10-12 cards. The aluminum chamber holds 6-8 and the leather flap holds 4 (2 ID windows included). The money clip on the back holds 10+ bills.
- DOUBLE ID WINDOWS: KAFELLON designed the first pop up wallet on the market with 2 ID windows, based on real user needs. It's perfect for holding your ID and driver's license for quick access and quick view.
- RFID BLOCKING: This rfid blocking wallet features a built-in RFID-blocking layer that blocks unauthorized scans, protecting your finances and personal information.
- PERFECT GIFT IDEA: This money clip wallet combines a modern design with great practicality and comes with an elegant gift box. It's the perfect gift for men on Christmas, Valentine’s Day, Father’s Day, and other special occasions.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




