Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsFirst identify what kind of discount you expected. An instant discount should reduce the checkout price; a card-linked offer may instead issue a statement credit after the purchase. The right fix depends on the offer’s terms, whether you activated it, which card you used, and whether the issuer’s posting window has passed. The issuer examples below cover U.S. Chase Offers and American Express Offers; your own offer terms and issuer guidance control.
A missing benefit does not always mean the same thing. If the checkout total was unchanged, the offer may have been designed to pay later as a statement credit. If a statement credit has not appeared, the purchase may still be within the program’s stated timeline—or one of the offer conditions may not have been met. Work out which situation applies before contacting customer service.
As an Amazon Associate I earn from qualifying purchases.
Identify how the offer is supposed to work
Check the offer itself before treating a missing discount as an error. Look for language explaining where the benefit appears: as a reduced price at checkout or as a credit on your card account after a qualifying transaction. A statement credit does not necessarily change the merchant’s checkout total.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Open the original offer in your card account, email, or other place where you received it. Read its terms for the eligible dates, merchant and location, spend threshold, number of purchases required, exclusions, required payment route, and any activation or promo-code instructions. Do not assume that an offer applies to every purchase from a merchant just because the merchant name matches.
#1 Best Overall

- SLIM BODY WITH LARGE CAPACITY:This mens wallet measures 4.3 x 3.2 x 0.6 inches and can hold 14 cards and 10+ bills. The slim design makes it perfect for fitting into all kinds of pockets, offering great portability.
- QUICK CARD SLOTS & CASH SLOT:On the front of this minimalist wallet for men, there are 2 quick-access card slots for easy retrieval while traveling or shopping. The cash slot allows you to quickly access and store cash without having to fold bills multiple times.
- DOUBLE ID WINDOWS:This card wallet for men specifically features 2 clear ID windows for holding ID cards and driver's licenses, enabling fast and convenient access to your information.
- FID BLOCKING:This rfid wallet is lined with a special RFID-blocking material that shields against 13.56 MHz and higher frequency signals. This prevents unauthorized scanning and data theft from your chips, offering comprehensive protection for your identity and financial information.
- PERFECT GIFT IDEA FOR MEN:Crafted with high-quality materials, this leather wallet for men combines practicality for mens everyday needs, making it an ideal gift for birthdays, anniversaries, Christmas, Valentine’s Day, Father’s Day, or other special occasions.
It helps to identify the exact offer rather than relying on a general description such as “10% back” or “card discount.” Locate the offer’s name, benefit, expiration date, eligible card, and full terms. If you have more than one offer from the same merchant, compare them individually: the conditions and credit timing may differ. The offer-specific terms, not the merchant name or a similar promotion you saw elsewhere, determine what should happen.
There are two separate points to check: whether the purchase qualifies and when the benefit should arrive. A transaction can be eligible but not yet credited because the applicable timeline has not run. Conversely, a credit can be absent because the offer was not activated, a different card was charged, or a transaction condition was not satisfied. Do not use the date you first noticed the offer or the date you contacted the merchant as a substitute for the dates the terms specify.
If you expected the price to drop at checkout
Check the merchant’s offer terms and checkout instructions. Confirm that you met any stated requirements, such as entering a promo code, buying an eligible item, reaching a minimum spend, or using a specified payment method. If the offer describes a later statement credit rather than an immediate price reduction, the checkout total may be correct.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Before placing another order or assuming the first one failed, compare the checkout instructions with the final order details. Did the offer require a code? Was it limited to an eligible item or location? Was there a minimum purchase amount or a required payment method? The terms may also specify a date range. If the benefit is a statement credit, the important record will be the card account transaction and the offer’s credit timeline, not a lower merchant receipt total.
If the merchant’s terms say the discount should appear at checkout and you met those terms, save the offer and order details and contact the merchant through its customer-service channel. Explain what the offer promised and what appeared in the order total. If the benefit is a card-linked offer, follow the issuer checks below instead.
Keep the two support questions distinct. For an instant promotion, ask the merchant to review the order against its checkout offer. For a card-linked offer, ask the issuer whether the transaction was recognized as qualifying under the offer attached to your account. A merchant may be able to explain its own checkout terms, while issuer guidance covers the card-linked offer and statement credit.
If you expected a statement credit
Confirm that you activated the offer in time
Some card-linked offers must be added before you make the purchase. American Express says its offer must be added before the purchase and that you must use the same enrolled card. Chase says an offer may not have been added and that each offer is linked to one Chase account. Check the Chase Offers FAQ or American Express Offers FAQ for current program guidance.
Rank #2
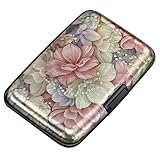
- This Credit Card Holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The Size is 4.33 x 2.95 x 0.73 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches Safely and Securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 9 credit cards or more than 21 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
For a Chase offer, look in the Added, Redeemed, and Expired areas of your account. Verify the selected account and the last four digits shown for the offer. For an American Express offer, confirm it was added to the card you intended to use.
Use the offer’s own status and account details as your first check. If you cannot find it under Added, see whether it appears under another status area, or whether the offer was associated with a different account or card. Do not assume that seeing an offer in an issuer’s offer list proves it was added to the card used for the purchase. For American Express, the issuer specifically says the offer must be added before the purchase; checking after the purchase may help explain what happened but does not change the stated requirement.
Chase says each offer is linked to one Chase account. If you have multiple accounts, verify that you are looking at the account where the offer was added and that the last four digits shown match the account involved in the transaction. If an offer’s status or account association is unclear, note what you see so you can describe it accurately when you contact Chase.
Match the purchase to the enrolled card and offer terms
Compare the card shown as enrolled for the offer with the card that was actually charged. Then check that the transaction met the offer’s requirements: eligible merchant and location, purchase dates, minimum spend, required number of purchases, and any restrictions on how you paid or placed the order. For American Express, the issuer says you must use the same card to which the offer was added.
Check the offer’s exclusions and the transaction route. A third party or intermediary may have processed the payment, and the specific offer terms determine whether that transaction qualifies. American Express also lists returned or cancelled purchases as a possible reason a credit may not be received. Review the American Express Offers page and the terms attached to your particular offer rather than assuming all offers share the same rules.
Look closely at the merchant and location language. A purchase from a business with a familiar name is not automatically the same as a transaction processed by the merchant specified in the offer. Likewise, an offer may identify a location, channel, or payment route. The terms determine whether the transaction that appeared on your account meets those conditions; do not rely only on the brand printed in a promotion or on a checkout page.
Check the amount and purchase-count requirements separately. If the offer specifies a spend threshold, compare it with the amount shown in the transaction rather than an estimate of what you intended to spend. If it requires more than one purchase, verify whether the conditions refer to a number of qualifying purchases rather than one larger purchase. The available offer wording controls; do not assume purchases can be combined or that a partial match is enough unless the terms say so.
Rank #3
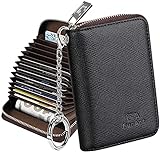
- Special Design: Multi-color optional and wear-proof classic business card holder looking.
- Plenty of Space: 16 card slots only measuring 4.1" x 3.0" x 1.1", including 13 credit card slots, 2 cash slots
- Protect Information Leakage: Prevents your vital information/cards from unnoticed scan with 2 outer layers RFID blocking materials.
- Extra Key Chain & Portable: Extra corns with key chain for your keys or lanyard. Portable use for shopping, traveling, etc.
- Great Gift: Practical compact wallet is the perfect gift. Give a thoughtful surprise to Men/Women on birthdays, holidays, celebrations, or any special occasion (e.g. Valentine's Day, Christmas, etc.).
Also consider whether the purchase was returned or cancelled, and whether a third party processed it. American Express lists returned or cancelled purchases among possible reasons for no credit. For third-party processing, the terms for the particular offer decide whether the transaction qualifies. These are checks to make against the actual offer, not universal exclusions that apply to every card-linked promotion.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Check the correct posting window
Use the program’s stated trigger date, not just the date you placed the order. Chase’s stated window begins after a qualifying transaction posts to your account. American Express’s guidance refers to the end of the offer period. These are different triggers, so the windows are not directly comparable.
| Program | Issuer-stated timing | Trigger |
|---|---|---|
| Chase Offers | Within 30 days, unless the offer terms state otherwise | After the qualifying transaction posts to the account |
| American Express Offers | Usually within 5 business days, but it can take up to 90 days | After the end of the offer period |
These are issuer guidelines, not a guarantee that every purchase will qualify. Check the terms for your specific offer. For Chase, do not start the 30-day count from an authorization or checkout date if the transaction has not posted. For American Express, the stated period can extend beyond the purchase date because it is measured from the end of the offer period. See the current Chase Offers FAQ and American Express Offers FAQ.
Chase states that statement credits generally appear within 30 days after qualifying transactions post to the account, unless the offer terms say otherwise. That means you first need to establish whether the card transaction has posted; a checkout receipt or an authorization alone is not the stated starting point. If the transaction is still not posted, the Chase 30-day period described by the FAQ has not begun on that basis.
American Express says a qualifying credit should automatically appear within five business days, but can take up to 90 days after the offer period ends. The end of the offer period is a different reference point from the purchase date. Check when that offer period ended and do not treat five business days after the purchase as a universal deadline. The FAQ’s wording also does not mean every purchase will receive a credit: the purchase still has to satisfy the specific offer conditions.
The timelines are useful for deciding when to follow up, not for deciding eligibility by themselves. Chase’s 30 days and American Express’s up-to-90-days refer to different triggering events. Do not compare them as if both clocks begin when you buy something, and do not use one issuer’s timeline to judge another issuer’s offer.
Work through the checks in order
- Open the exact offer. Locate its terms and note eligible dates, merchant and location, spend threshold, purchase count, exclusions, payment route, and any activation or promo-code requirement. Save the terms or make a note of the relevant conditions while you investigate.
- Identify the promised benefit. Confirm whether the offer describes a checkout price reduction or a later statement credit. If you expected the wrong type of benefit, the absence of a checkout discount may not indicate a problem.
- Verify activation. Confirm the offer was added before the purchase if required. In Chase, check Added, Redeemed, and Expired, and verify the account and last four digits associated with the offer.
- Match the card. Compare the enrolled card with the card charged. For American Express, the same card the offer was added to must be used.
- Check the transaction. Review the posted transaction’s merchant, amount, date, and payment route against the offer terms. Consider whether a return, cancellation, or third-party processor affected eligibility.
- Apply the right deadline. For Chase, count from when the qualifying transaction posts. For American Express, use the offer-period end date and allow the stated time.
- Contact the issuer if the offer still appears to qualify. If the applicable window has passed, ask the issuer to review whether the transaction was recognized as qualifying.
Following the steps in this order helps avoid mixing up separate issues. First determine the form of the benefit, then verify activation and the card used, then compare the purchase with the conditions, and only after that calculate the applicable wait. If any one of those facts is uncertain, write it down rather than filling in a guess. That gives you a clearer question for the issuer.
Rank #4
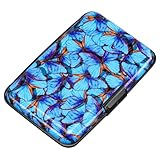
- This credit card holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The size is 4.33 x 2.95 x 0.75 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches safely and securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 10 credit cards or more than 20 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
What to provide when you contact the issuer
Call the number on your card or use the support option in your issuer account. Chase also lists its Secure Message Center as a contact route. Have the offer details, purchase or transaction date, amount, merchant, and receipt or statement information ready. Explain which terms you believe the purchase met and ask the issuer to review whether it was recognized as a qualifying transaction.
A concise record can include the offer name or a copy of its terms, when it was added, the card’s last four digits, the merchant and location shown in the offer, the purchase date and amount, and whether the transaction has posted. Include the receipt or statement details that identify the purchase. If there was a return, cancellation, or third-party processor, mention it rather than leaving out a fact that may affect how the offer is evaluated.
Free tools Windows power users keep installed
One-click scans. No signup required.
Keep the explanation specific. For example, say that you added a particular offer to a particular card, made a purchase on a stated date, and believe it met the merchant, spend, and payment conditions. Then ask whether the transaction was recognized as qualifying and whether any offer condition or timing rule explains the missing credit. The goal is to have the issuer review the exact offer and transaction, not merely to report that a discount is missing.
If the offer still appears to qualify but the stated timeline has passed, use the card or account support route and retain the information you used. Chase lists its Secure Message Center as an option in addition to contacting support. American Express directs cardmembers to its offer FAQ and card account guidance. Use the current route available through your issuer account if contact options change.
If you are comparing multiple offers, check each one separately. Enrollment rules, eligible cards and merchants, spending conditions, purchase-channel exclusions, end dates, credit timing, and dispute routes can differ even when the offers look similar. Do not assume that a credit from one offer establishes how another offer should work.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Common mistakes that can delay a clear answer
- Looking only at the checkout receipt. A statement credit may arrive later and therefore will not necessarily reduce the merchant’s total at purchase.
- Counting from the wrong date. Chase’s FAQ describes a period after the qualifying transaction posts. American Express’s FAQ measures the possible delay from the end of the offer period.
- Checking the wrong card or account. The offer may have been attached to a different eligible card or, for Chase, a different Chase account. Match the offer details with the card that was charged.
- Assuming the merchant name is enough. Merchant, location, channel, payment route, spend, and purchase-count terms may matter. Read the offer rather than relying on the brand name alone.
- Treating every issuer’s rule as identical. The Chase and American Express examples have different terms and timing references. Your particular offer and issuer’s current guidance control.
- Contacting support without transaction details. The offer, date, amount, merchant, card, and receipt or statement information help the issuer review the specific purchase.
There is no single failure rate or universal cause that explains missing card discounts. The practical way to diagnose one is to identify the offer mechanism and test the specific conditions one by one. If the details fit and the relevant waiting period has elapsed, escalate with the transaction record rather than repeating the same general question.
Recommended Free Tools
Frequently Asked Questions
Why didn’t my credit card discount apply at checkout?
First check whether the offer promised an immediate price reduction or a later statement credit. For an instant discount, review the merchant’s checkout terms for eligible items, dates, minimum spend, promo-code instructions, and required payment method. If the offer is a card-linked statement credit, the checkout total may not change.
Best Value

- RFID Blocking Technology: This credit card holder is made of aluminum shells and ABS plastic, designed with RFID-blocking technology to help protect your credit, ID, debit, and driver's license cards from unauthorized scanning
- Slim Compact: Slim and compact design measures 4.3 x 3 x 0.86 inches, ideal for front pockets or purses
- Card Organizer: With 7 accordion-style slots, this wallet can hold up to 10 standard credit cards or over 20 business cards
- Artistic Expression: Features a variety of artistic designs on the aluminum shell, inspired by famous paintings, flowers, and animals, to complement your personal style
- Thoughtful Gift Idea: Makes a thoughtful gift for any occasion, combining functionality and style
What if I used one of my Chase Offers but didn’t receive a statement credit?
Check that the offer was added to the relevant Chase account and confirm the account and last four digits shown in Added, Redeemed, or Expired. Then compare the charged card and posted transaction with the offer terms. Chase says statement credits generally appear within 30 days after a qualifying transaction posts, unless the offer terms state otherwise. If that period has passed and the purchase appears to qualify, contact Chase or use its Secure Message Center with the offer and transaction details.
What should I do if the statement credit does not appear in my card account?
Identify the exact offer, verify it was activated before purchase if required, confirm you used the enrolled card, and check the merchant, date, amount, purchase count, exclusions, and payment route. Apply the issuer’s stated timeline from the correct trigger date. If the deadline has passed and the transaction appears to qualify, contact the issuer with the offer details and receipt or statement information.
How long should I wait for a card-linked offer credit?
It depends on the offer and issuer. Chase says credits generally appear within 30 days after a qualifying transaction posts, unless the terms say otherwise. American Express says a qualifying credit should appear within five business days but can take up to 90 days after the offer period ends. Those clocks start from different events, and the offer-specific terms control.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Does a statement credit reduce the amount I pay at checkout?
Not necessarily. A statement credit is applied to the card account after a qualifying purchase rather than necessarily changing the merchant’s checkout total. Check the offer wording to see whether it promises an immediate checkout discount or a later account credit.
Can a returned or cancelled purchase qualify for an American Express Offer?
American Express lists returned or cancelled purchases as a possible reason a credit may not be received. Check the terms of the specific offer and contact American Express if the transaction otherwise appears to qualify.
What information should I have ready when I contact my card issuer?
Have the offer details, purchase or transaction date, amount, merchant, and receipt or statement information available. It also helps to identify the card used, whether the transaction has posted, and which offer conditions you believe were met. Ask the issuer to review whether the transaction was recognized as qualifying.
The Bottom Line
A missing credit is easiest to troubleshoot once you know whether the offer was meant to lower the checkout price or post later to your card account. Check the exact terms, activation, enrolled card, transaction conditions, and the issuer’s correct timing trigger. If the offer still appears to qualify after its stated window, contact the issuer with the offer and purchase records; for an immediate checkout promotion, contact the merchant.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




