What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
U.S. renewable-energy projects can attract capital through tax equity, a structure that gives an investor an ownership interest and associated tax benefits, or through a sale of eligible tax credits under Internal Revenue Code section 6418. A credit transfer is a cash transaction between eligible, unrelated taxpayers; it does not give the buyer ownership of the project or its depreciation. The routes can coexist within a project, but eligibility, tax treatment and deadlines depend on the project’s facts.
What is tax equity?
Tax equity is project financing in which an investor with the capacity to use tax benefits participates in a renewable-energy project and receives an ownership interest along with tax benefits available under the applicable structure. It links financing to project ownership and the tax treatment associated with that ownership. The precise arrangement and benefits depend on the project and applicable tax rules.


Tax equity is distinct from a section 6418 credit transfer. In a transfer, an eligible taxpayer sells some or all of certain eligible credits to an unrelated taxpayer for cash. The buyer acquires the credit under the transfer rules, not an ownership share in the generating facility. A project may use different financing or credit-monetization approaches, but the rules for each transaction must be analyzed on their own terms.
How do tax equity, credit transfers and elective pay differ?
| Route | Who uses it | What changes hands | Key distinction |
|---|---|---|---|
| Tax equity | A project investor participating under an ownership structure | An ownership interest and the tax benefits associated with the applicable structure | Ownership matters; this is not simply a purchase of a credit. |
| Section 6418 transferability | An eligible taxpayer that is not an applicable entity, and an unrelated buyer | All or part of certain eligible credits, transferred for cash | The buyer does not acquire project ownership or depreciation through the credit transfer. IRS transferability FAQ |
| Elective pay under section 6417 | Applicable entities, including certain tax-exempt and governmental entities, if eligible | A payment claim for certain eligible credits | Applicable entities generally cannot use section 6418 to transfer credits; elective pay may be available subject to requirements. IRS overview FAQ |
These are federal tax mechanisms, not interchangeable labels for the same deal. The relevant entity’s status, project ownership, credit eligibility and intended tax treatment determine which route may be available.
#1 Best Overall
Who can sell renewable-energy tax credits?
Under the IRS explanation of section 6418, an eligible taxpayer that is not an applicable entity under section 6417 may transfer eligible credits. The IRS lists tax-exempt organizations, states and political subdivisions, local and tribal governments, Alaska Native Corporations, the Tennessee Valley Authority, rural electric cooperatives, U.S. territories, and certain government agencies or instrumentalities among entities generally treated as applicable entities and therefore not eligible taxpayers for transferability.
That list is not a substitute for checking a particular seller’s legal status and circumstances. Applicable entities may qualify for elective pay for certain credits if they meet the relevant requirements. The IRS cautions: “In general, Treasury and the IRS do not provide personalized tax advice regarding whether a specific organization’s project or activity is eligible for a tax credit.” IRS transferability FAQ
Rank #2
Which clean-energy credits may be transferred?
The IRS transferability FAQ lists several credits relevant to energy projects, among other eligible credits. Eligibility and any bonus amounts depend on the credit and project requirements.
| Credit | Internal Revenue Code section |
|---|---|
| Energy Credit | 48 |
| Clean Electricity Investment Credit | 48E |
| Renewable Electricity Production Credit | 45 |
| Clean Electricity Production Credit | 45Y |
| Other credits listed by the IRS, including advanced manufacturing, clean hydrogen, clean fuel production, carbon capture, alternative fuel vehicle refueling property, and qualifying advanced energy project credits | 45X, 45V, 45Z, 45Q, 30C and 48C |
A bonus amount cannot be transferred separately from its base credit, according to the IRS. The project and taxpayer must satisfy the applicable requirements to earn and transfer the credit; the existence of a credit category alone does not establish that a particular facility qualifies. IRS transferability FAQ
Recommended Free Tools
Rank #3

- Durable hardcover with concealed wire-o binding
- Archival, acid-free paper helps preserve your information.
How does a tax-credit transfer work?
The seller and buyer negotiate the transaction terms and cash price. The IRS does not set the commercial price in the guidance summarized here. A transfer involves more than signing a purchase agreement: the credit and project must qualify, required registration information must be obtained, the election must be documented, and the parties must meet their applicable reporting duties.
- Establish credit eligibility. The project and taxpayer must satisfy the requirements for the applicable credit and tax year.
- Complete pre-filing registration. The eligible taxpayer provides required information and obtains the registration number for the credit property.
- Arrange a transfer to an unrelated buyer. The parties agree to transfer all or part of an eligible credit in exchange for cash and settle the transaction terms.
- Prepare the required transaction information. The parties provide required property and credit information and complete the transfer election statement.
- Report the election on the required returns. The transferor and transferee file their returns with the election statement and other required information under the applicable rules.
This is a high-level outline, not a tax-year-specific filing checklist. The IRS notes that not every step necessarily has to occur in the displayed order. Consult current IRS instructions and qualified tax advisers for the relevant credit, year and transaction. IRS transferability FAQ
Rank #4
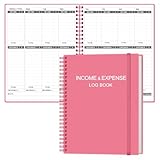
- EASY TO MANAGE - Use this income & expense log book to record your income and expenses each day.Keep your budget in balance, and develop good bookkeeping habits to meet your financial goals
- ACCOUNTING FOR THE WHOLE YEAR - This account ledger notebook is undated and is used to lasts a whole year.The keeping log has 1 page Year Overview, 53 weekly spreads, 2 pages annual summary, 10 notes pages, to track weekly and yearly income & expenses
- HIGH QUALITY - The accounting bookkeeping tracking ledger log book is used to high quality 100gsm pure white paper, teal elastic band and a back pocket for extra space. Make sure you have enough space for all financial activities
- UNIQUE DESIGN & A4 SIZE - Income and expense log book cover is lovely, golden spiral bound design, size of 8" x 10.5". Just the perfectly size to fit in your backpack, purse or laptop case. Without taking up your space and always helping you keep track of your small business
- THE PERFECT GIFT - Income & expense notebook as gift for woman & man. Use it to track your week-to-week progress, make efficient adjustments whenever needed
What does a credit buyer receive—and what risks remain?
No project depreciation through the transfer
A purchaser of a transferred credit does not receive the project’s depreciation deductions through that transfer. The IRS says only a taxpayer with an ownership interest in the project may claim depreciation. That is a fundamental difference from an ownership-based tax-equity arrangement.
Credit use can be limited for some buyers
Individuals, estates and trusts, closely held C corporations, and personal service corporations may be subject to passive-activity rules that limit their ability to use purchased credits. Buyers should assess their own tax position rather than assume a purchased credit will offset any tax liability.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsBest Value
Documentation, recapture and excessive transfers matter
The IRS’s final guidance addresses excessive credit transfers and recapture events. Buyers and sellers should account for the applicable rules and preserve the documentation supporting eligibility, registration, the election and reported amounts. A transfer should not be treated as a risk-free or automatically refundable tax asset. IRS final-guidance release
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Why do the 2025 changes matter to wind and solar project timing?
The 2025 law added termination provisions for the section 45Y Clean Electricity Production Credit and section 48E Clean Electricity Investment Credit for applicable wind and solar facilities placed in service after December 31, 2027. The statutory treatment also makes beginning-of-construction determinations relevant. The IRS described the changes in Internal Revenue Bulletin 2025-36 and issued Notice 2025-42 on determining when construction begins for relevant wind and solar facilities.
The placed-in-service date and construction-start rules answer different questions. A project cannot establish its treatment merely by pointing to one date: the applicable facility, construction-start determination and current statutory and IRS guidance must be considered together. The deadlines are especially material to financing and credit-transfer planning because the expected credit depends on the project meeting the rules for the applicable credit. Notice 2025-42 supplies guidance, but whether a facility meets the rules is project-specific.
What should a project team verify before structuring a transaction?
- Entity status: Is the proposed transferor an eligible taxpayer, or is it an applicable entity that may need to evaluate elective pay instead?
- Credit and facility: Which code-section credit is at issue, and does the project satisfy that credit’s requirements for the relevant tax year?
- Timing: For applicable wind and solar projects relying on sections 45Y or 48E, what do the placed-in-service records and construction-start facts establish under current law and IRS guidance?
- Transaction parties: Is the buyer unrelated to the seller as required, and have the parties agreed on the cash transfer terms?
- Buyer tax position: Can the buyer use the credit under the applicable rules, including any passive-activity limits that may apply?
- Filing and evidence: Are registration, the election statement, property and credit information, and each party’s tax-return reporting responsibilities addressed?
- Ownership and tax benefits: Does the financing plan distinguish credit ownership from project ownership and depreciation?
These checks identify issues for diligence; they do not determine eligibility for any specific project. Tax consequences depend on the parties’ facts and the law applicable to the relevant year, so project teams should obtain advice from qualified tax professionals.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




