Free tools Windows power users keep installed
One-click scans. No signup required.
SK Hynix has beaten Samsung in two distinct measures: it led quarterly DRAM revenue in the first quarter of 2025, and it briefly surpassed Samsung Electronics in South Korean market capitalization on June 22, 2026. Neither milestone means it has overtaken Samsung across all memory products or manufacturing capacity. The supply outlook is also narrower than the phrase “memory shortage” suggests: forecasters see continued pressure on HBM and DRAM, while NAND Flash could begin easing in the second half of 2027.
What SK Hynix has overtaken Samsung in
| Measure | What happened | What it does—and does not—show |
|---|---|---|
| Quarterly DRAM revenue | TrendForce reported first-quarter 2025 revenue of $9.72 billion for SK Hynix and $9.1 billion for Samsung; Micron reported $6.58 billion. | SK Hynix ranked first for that quarter, not necessarily in every period or memory category. TrendForce’s 1Q25 DRAM results |
| South Korean market capitalization | Reuters reported that on June 22, 2026, SK Hynix briefly edged past Samsung Electronics in common-share market value: about 2,082.5 trillion won versus 2,081.3 trillion won. Samsung preferred shares were excluded. | This was a stock-market valuation at a point in time, not a comparison of production, memory revenue or total corporate assets. Market values can change with share prices. Reuters’ report on the June 22 milestone |
| HBM position | SK Hynix built an early, strong position in high-bandwidth memory (HBM), supplying memory used with AI accelerators. | “Leading” depends on the period and whether a ranking measures revenue, bits, shipments, generation or qualified capacity. It does not establish an across-the-board lead in memory. |
| Total memory manufacturing | No like-for-like current comparison across DRAM, NAND and other memory categories is established here. | Samsung remains a major supplier with broad manufacturing scale and a wide memory portfolio. |
Why HBM has lifted SK Hynix’s position
The key advantage has been product mix and execution, not simply the number of wafers produced. HBM is a form of DRAM built as a stack of memory dies and used alongside processors in AI systems. Making it at scale involves advanced dies, stacking, interconnects, testing, packaging and customer qualification. A supplier with substantial conventional DRAM capacity can still lose HBM business if a product is delayed, needs redesign or does not qualify in time.
| # | Preview | Product | Price | |
|---|---|---|---|---|
| 1 |

|
Corsair Vengeance RGB RS DDR5 16GB (2 x 8GB) Up to 6000MHz AMD Intel RAM | $285.99 | Buy on Amazon |
| 2 |
|
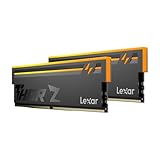
Lexar Thor Z RGB DDR5 RAM 32GB Kit (2x16GB) 6000MHz CL38 DRAM 288-Pin UDIMM | $479.99 | Buy on Amazon |
AI accelerators need large amounts of fast memory to keep their processors supplied with data. That demand made HBM unusually valuable to chipmakers and cloud operators. SK Hynix’s early position in HBM3 and HBM3E helped it capture demand; TrendForce linked its first-quarter 2025 DRAM revenue lead partly to growing HBM3E shipments, while attributing Samsung’s decline in part to reduced HBM3E shipments during a redesign. TrendForce’s account of the quarter
Because HBM can command high value and has strategic importance to AI customers, a supplier can gain revenue and influence without being the largest producer by total wafer volume. The ranking therefore reflects what manufacturers could sell into a high-demand product segment, as well as their overall output.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall
- Disclaimer: Maximum Speed requires overclocking/PC BIOS adjustments. Maximum speed and performance depend on system components, including motherboard and CPU
- AMD EXPO & Intel XMP 3.0 Compatible Only: Dual memory profiles allow you to easily select optimized settings for your platform, whether you’re running an AMD or Intel processor
- Dynamic RGB Lighting: Individually addressable RGB lighting delivers vibrant effects through a sleek, understated panoramic diffuser
- Onboard Voltage Regulation: Onboard voltage regulation for reliable power at high frequencies
- Maximum Bandwidth and Tight Response Times: Optimized for peak performance on the latest AMD and Intel DDR5 motherboards
How HBM demand tightens conventional DRAM
HBM does not have to represent most of the industry’s memory bits to put pressure on the rest of the DRAM market. Its production uses advanced DRAM capacity and adds demanding packaging and testing steps. When suppliers direct more resources to HBM and server products, fewer are available for conventional DRAM used in PCs, smartphones and other devices. Packaging, yield and qualification constraints can further limit how quickly output grows.
TrendForce estimates that HBM wafer input at the three leading suppliers will equal about 18% of their total DRAM wafer input by the end of 2025, 22% by the end of 2026 and 30% by the end of 2027. These are forecasts of wafer input, not shares of memory bits produced. HBM’s more complex production means the proportion of bits can be smaller than its share of wafer capacity. TrendForce’s HBM capacity outlook
Why DRAM tightness may continue into 2027
TrendForce’s July 2026 outlook points to AI-server and cloud demand growing faster than available supply, while new capacity and process changes take time to deliver usable output. Building facilities, obtaining equipment, migrating production and qualifying products are not instant fixes. HBM allocation also competes with conventional DRAM, and future AI platforms may use more memory per accelerator.
TrendForce says the 2027 supply gap could widen as HBM and SOCAMM—a memory module format for AI systems—consume more wafer capacity and squeeze supply of server RDIMMs, the registered memory modules used in servers. It also identifies higher-volume NVIDIA Rubin deployments, Rubin Ultra’s higher HBM capacity per GPU, and expanding custom AI-chip deployments, including Google TPU-related demand, as potential demand drivers. These are forecasts, not a guarantee that every memory buyer will face a shortage or that prices will rise continuously. TrendForce’s July 2026 DRAM outlook and July 22 DRAM bulletin
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problemsThe outlook could change if AI investment slows, high prices lead customers to defer purchases or reduce configurations, suppliers add capacity faster than expected, or process migration increases output. Samsung and Micron gaining share, improvements in HBM production efficiency, and the timing of new facilities also matter. The forecast describes a risk of persistent tightness, not a fixed endpoint that manufacturers can promise away.
Samsung remains a serious HBM competitor
Samsung has the scale and portfolio to compete, and its HBM4 roadmap makes a lasting handover far from certain. Samsung says it has shipped commercial HBM4, expects HBM sales in 2026 to more than triple compared with 2025, plans to sample HBM4E in the second half of 2026, and expects to provide custom HBM samples in 2027. Those are company-stated shipments and targets, not independent proof of future market share. Samsung’s HBM4 announcement
There is also a different account of the competitive timing. In a June 23, 2026 bulletin, TrendForce said Samsung completed HBM4 validation first and began shipments in the second quarter, while SK Hynix faced qualification delays that pushed mass production toward the third quarter. TrendForce also reported that Samsung was targeting a significant increase in 2027 HBM shipments. Qualification, shipment and mass production are separate stages, so early shipments alone do not settle which supplier will lead in volume or revenue. TrendForce’s HBM4 competition bulletin
SK Hynix enters that contest with a strong established HBM position; Samsung is seeking to turn its manufacturing resources and HBM4 progress into more supply. Micron is another major competitor, and its first-quarter 2025 DRAM revenue ranked third behind the two Korean suppliers. The relative positions can shift as qualification, yields, customer orders and deliveries change.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Rank #2
- Unleash Next-Gen Dominance: Experience Lexar DDR5 RAM performance with the Lexar THOR Z Series RGB DDR5 RAM 32GB Kit (2x16GB). Clocking at a blistering 6000MHz with low CL38 latency, this DDR5 desktop memory delivers up to 6000 MT/s for a full-throttle advantage. Whether you're building a high-end gaming rig or a professional workstation, this Lexar 32GB RAM kit ensures your system keeps pace with next-gen titles
- Sleek & Robust Thermal Design: Engineered for both aesthetics and endurance, this Lexar DDR5 RAM 6000MHz features an all-new streamlined design. The solid, sandblasted aluminum heatsink fuses a minimalist, razor-sharp aesthetic with uncompromising thermal control. This Lexar THOR Z Series armor ensures your DDR5 memory stays cool under pressure, delivering sustained peak performance during intense gaming sessions
- Game in Style with Brighter RGB Lighting: Elevate your build's aesthetics with the enhanced customizable RGB lighting on this Lexar RGB DDR5 RAM. Brighter and more vibrant than previous generations, the Lexar THOR Z Series RGB DDR5 RAM allows you to synchronize lighting effects with your components, creating a truly immersive gaming atmosphere that stands out from the crowd
- On-die ECC & PMIC for Rock-Solid Stability: Go beyond speed with reliability. This Lexar DDR5 RAM kit integrates On-die Error Correction Code (ECC) to automatically correct data errors, vastly improving stability and reliability for your critical tasks. The onboard Power Management Integrated Circuit (PMIC) ensures efficient power delivery, boosting the overall power efficiency of your DDR5 desktop memory for a longer-lasting, more stable system
- Seamless Compatibility with Intel & AMD: Worry-free upgrade guaranteed. The Lexar THOR Z Series DDR5 RAM is built for broad compatibility with the latest platforms. It fully supports Intel XMP 3.0 and AMD EXPO one-click overclocking, making it effortless to achieve the rated speeds. Trust Lexar DDR5 RAM to deliver seamless performance with mainstream DDR5 motherboards
“Memory shortage” does not mean every memory product is scarce
DRAM and NAND Flash serve different markets and can have different supply cycles. The strongest 2027 tightness case concerns HBM, server DRAM and selected conventional DRAM products. TrendForce, by contrast, expects NAND supply growth to outpace demand in 2027 and constraints to ease in the second half of that year, after an undersupplied 2026. That is a forecast, not a guarantee of lower prices for every SSD or storage product. TrendForce’s July 2026 NAND outlook
It also matters where a constraint occurs. A shortage of memory dies, packaged HBM stacks, server modules and finished computers are not interchangeable claims. Tight chip supply can raise costs without making every finished device unavailable.
What the outlook could mean for buyers
AI chipmakers and cloud operators
HBM allocation and qualification can become planning constraints well before a system launch. Customers may need to secure supply early and consider more than one qualified source where product requirements allow. Memory availability can affect accelerator delivery schedules and total system costs.
Server makers and enterprise buyers
Server DRAM availability may constrain configurations even when processors or accelerators are available. Buyers may face higher system costs or need to plan around different memory capacities and module availability. A forecast of tight RDIMM supply is particularly relevant to server procurement, not a claim that all types of computer memory are equally scarce.
PC and smartphone companies
When suppliers prioritize higher-demand HBM and server products, consumer-device makers can face tighter access to some DRAM products. Higher component costs may reach device prices, but the pass-through depends on contracts, product mix and competition. Weak demand for a particular phone or PC category does not automatically free the exact capacity its manufacturers need.
Consumers
Potential effects include higher costs for RAM upgrades, laptops or smartphones, but timing and scale will vary by product. NAND and DRAM pricing may move in different directions, so a tight DRAM market does not by itself establish that SSDs or every storage product will get more expensive.
What this means for personal investors
The market-cap milestone is not an investment verdict. SK Hynix’s stronger exposure to the HBM cycle may appeal to investors seeking that business, while Samsung’s broader operations mean its results reflect more than memory. Micron offers another major DRAM, NAND and HBM competitor. All remain exposed to semiconductor cyclicality: demand, supply additions, pricing and investor expectations can change, and a shortage forecast alone does not establish that any share price will rise.
Investors comparing the companies should distinguish quarterly revenue from long-term profitability, market capitalization from manufacturing leadership, and company guidance from independently confirmed outcomes. The June 2026 valuation comparison excluded Samsung preferred shares and captures one market moment; it does not measure the value of the companies on a like-for-like operating basis.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




