Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteThere is no one-size-fits-all answer for Charlotte households. Compare the rent for a home that meets your needs with a current written mortgage offer for a comparable home, then add the full costs of owning and consider how long you expect to stay. Recent local figures show a meaningful rent-versus-buy gap, but they cover different places and months, so they are context—not a personalized verdict.
Should I rent or buy in Charlotte?
Start with your own budget, target home and plans—not a citywide median. Buying may fit if the all-in cost is manageable, you expect to stay long enough to make the upfront and eventual selling costs worthwhile, and you are comfortable taking responsibility for repairs and home-value risk. Renting may fit better if you need flexibility, expect to move, or prefer a landlord to handle larger maintenance issues under the lease.


Charlotte city figures offer a snapshot, not a direct comparison for every household. Realtor.com Economic Research reported a median listing price of $429,000, a median sold price of $429,500, median rent of $1,720 per month, 6,074 active listings and a 60-day median time on market for September 2026. Those are city-level listing-market indicators: a listing median is not necessarily the price a buyer pays, and the median rent may not describe a home comparable to the one you would purchase. See Realtor.com Economic Research data.
Is it cheaper to rent or buy in Charlotte?
A Realtor.com metro rent-versus-buy model for March 2026 estimated median rent at $1,494 per month and the monthly cost of buying a starter home at $2,137—a $643, or 43.0%, difference. The comparison covers the Charlotte-Concord-Gastonia, NC-SC metro area, not the Charlotte city market, and it is from March rather than September. It is a useful indication of a cost gap in that model, not a quote for your rent or mortgage. Read Realtor.com’s rent-versus-buy report.
#1 Best Overall
For your decision, compare homes that actually meet the same household needs. A rent figure for one kind of home and a purchase cost for a different size, location or condition can mislead. Use a consistent purchase price, down payment and loan term, and get a current lender quote.
How do rising mortgage rates affect the decision?
Freddie Mac reported national average rates of 7.28% for a 30-year fixed mortgage and 6.60% for a 15-year fixed mortgage on October 1, 2026. Its weekly Primary Mortgage Market Survey is based on loan applications submitted by lenders nationwide; those averages are not Charlotte-specific and are not an offer to an individual borrower. Your rate depends on personal and loan factors. Check Freddie Mac’s weekly rate survey.
Rank #2

- Effective Budget Plan Book – Take control of your finances with the SUNEE budget account book. This all-in-one budget planner allows you to plan and track your income, expenses, savings, and financial goals. Its intuitive layout and easy-to-use sections help you stay organized and make smart decisions to reach financial success. Our financial planner also included a comprehensive guidebook with valuable tips and instructions to help you get the most out of your budgeting planner.
- Full-Page Calendars – Each month’s full-page calendar provides plenty of space to track paydays, bills due dates, appointments, and important events. No more cramped boxes or tight writing areas, you can easily plan and organize your schedule at a glance.
- Colorful Pages Layout and Tabs – This vibrant budget planner features a user-friendly design for easy navigation and organization. Each month includes dedicated budget pages to set financial goals, track income, and plan expenses. Additional sections like debt trackers, savings goals, and bill payment trackers make managing your finances a breeze. The colorful backgrounds on each page offer clear, instant visibility.
- Bonus 4 Stickers and Convenient Design – This monthly budget planner is built for convenience and durability. Water-resistant cover protects against spills, while the elastic band keeps everything secure, and the dual-sided pocket offers extra storage. Plus, we’ve included 4 adorable sticker sheets to personalize your planner and make budgeting more enjoyable. Experience a budget planner that combines practicality with lasting quality.
- UNDATED DESIGN & 1 YEAR USE - Undated finance books start with 1 page-financial goals, 1 page-Mind Map, 1 page-Financial Strategy, 1 page-Tactics, 2 pages-Important Dates, 4 pages-Bill Tracker, 4 pages-Saving Tracker, 8 pages-Debt Tracker, followed by 12 Months(10 pages per month, 1 unique color for each month). 2 pages-Christmas Budgeting, 2 pages-Yearly Summary, 2 pages-Check Register and 12 pages-Notes(dotted). It is UNDATED, so you could start at any time, suitable for 1 year use.
A higher rate can raise the principal-and-interest payment for a given loan amount, so run the numbers using a written quote rather than a national average. Freddie Mac notes, “A lower mortgage rate makes homes more affordable because it costs you less to borrow money, which in turn increases your purchasing power (the financial ability to buy a home).” Freddie Mac’s explanation of mortgage rates and affordability.
What costs belong in a rent-versus-buy comparison?
Mortgage principal and interest are only part of the ownership budget. Compare monthly costs and the cash you need up front; include items that apply to the specific home and loan.
Rank #3

- Concise fill-in lists and charts enable you to compile the essential information you need to stay organized as you get ready for your home.
- Gather all the details here -- from your real estate agent to your attorney, from utilities and community info to plumbers, electricians, remodeling plans, and beyond.
- Includes graph paper and forms for planning room details, as well as checklists for routine maintenance.
- Convenient inside back cover pocket for business cards, receipts, etc.
- Elastic band closure attached to the back cover keeps your place or keeps your planner closed.
- Monthly ownership costs: property taxes, homeowners insurance, any mortgage insurance, HOA dues, utilities that differ from renting, and a realistic allowance for repairs and maintenance.
- Upfront and eventual transaction costs: North Carolina Housing Finance Agency guidance says buyers generally pay closing fees around 2–5% of the purchase price. Possible charges include attorney, inspection, appraisal, origination and title fees; actual costs vary by transaction. Buying and later selling also involve one-time costs.
- Actual loan figures: Ask the lender for a Loan Estimate and review the Closing Disclosure for the transaction’s stated costs. NCHFA homebuyer and loan-program guidance.
Do not treat a projected repair allowance or a general closing-cost range as a bill. Use the property, lender and transaction documents to replace estimates with actual figures as you get them.
How long do you expect to stay?
Freddie Mac says buying may make sense for someone who expects to stay at least five to seven years. Treat that as consumer guidance, not a guaranteed break-even threshold: the result depends on the purchase, financing, ownership costs, rent alternatives and future sale. Renting can be more suitable when a move is likely or flexibility is especially valuable. Freddie Mac’s rent-or-buy guidance.
What risks and trade-offs should Charlotte buyers weigh?
- Predictability: A fixed-rate mortgage keeps the interest rate constant for the life of the loan, which can make principal-and-interest budgeting more predictable. Total housing costs can still change.
- Maintenance and repairs: Owners bear repair costs and responsibility. Renters may have larger maintenance obligations handled by a landlord, depending on the lease.
- Home value and equity: Ownership can build equity, but a home’s value can decline. Renting does not build home equity, but can preserve mobility and avoid some ownership risks.
- Flexibility: Moving from a rental is generally less tied to selling a property; owning can make a short stay more costly or complicated.
Freddie Mac sums up the broader choice this way: “Deciding whether to rent or buy a home depends on your financial situation, future plans and lifestyle.” Freddie Mac’s consumer guidance.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Could North Carolina down-payment assistance help?
NCHFA’s NC Home Advantage Mortgage program offers eligible first-time and move-up buyers down-payment assistance of up to 3% of the loan amount. Eligible first-time buyers and military veterans may qualify for a separate $15,000 assistance option, subject to additional rules. The state program page lists conditions including a North Carolina principal residence, qualifying loan and lender, and credit and income requirements. Check current availability and eligibility with NCHFA or a participating lender; assistance does not make a home affordable if its ongoing costs do not fit your budget. Review NC Home Advantage Mortgage details.
Recommended Free Tools
Quick Recap
Best Value
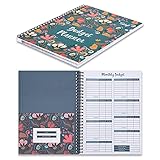
- Customize & Get Budgeted - With blank free of pre-filled categories and months budgeting pages, Soligt undated budget planner gives you complete control of your finances on a daily monthly and annual basis and enable you to manage your personal finance, cash money payment, and budgeting effective without any restrictions.
- Keep you on Track & Organized - The budget book journal provides 12 cute pockets for effortless bill, receipt, envelopes storage, along with a spacious layout perfect for recording and tracking incomes, expenses, savings, debt payoff, bills calendar and paying with ease.
- Achieve Financial Goals - This bill organizer provides a simple yet comprehensive budgeting system that is perfect for home household or small business beginners and encourages celebrating successes while identifying opportunities for improvement, both visually appealing and user-friendly.
- Your perfect companion - The Spiral bound budgeting notebook is the perfect small size, measuring at 9.25 x 6.81" and featuring a durable hardcover and 100 gsm paper. Lightweight and portable, It is easy to take with you wherever you go and built to last throughout the year.
- Bonus Month Tabs - The paycheck Budget Planner Financial Organizer boasts colored sticker labels to aid in simple navigation through your budget pages, ensuring added convenience and ease of use to help locate important information quickly and efficiently.
A practical way to make the comparison
- Choose comparable housing: Identify a rental and a home to buy that meet the same needs for location, size and condition.
- Get a current loan quote: Ask a lender for the rate and payment based on the purchase price, down payment and loan term you are considering; note the quote date and assumptions.
- Build the ownership total: Add taxes, insurance, mortgage insurance if applicable, HOA dues, differing utilities, repairs and maintenance, plus actual closing costs and eventual selling costs.
- Compare available cash and monthly budgets: Account for cash needed at purchase as well as recurring costs, and compare the result with rent for the comparable home.
- Test your plans: Consider how long you expect to stay, whether you may need to move, and whether you can absorb repairs or a decline in home value.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




