Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOnly 1.05 million active adjustable-rate mortgages (ARMs) have passed their initial fixed-rate period and are currently adjusting, according to ICE’s October 2026 Mortgage Monitor. ICE says that is the lowest number in more than 25 years of its tracking. It does not mean only 1.05 million ARMs exist: ICE counts 3.1 million active first-lien ARMs overall, and most have not yet reached their first reset.
What the 1.05 million figure counts
The figure is a count of active ARM loans that have reached their first rate reset and are operating as adjustable-rate loans. It is not the total number of active ARMs, nor does it count every borrower who may face a future reset. ICE reported the figure in its October 2026 Mortgage Monitor, published October 5, 2026.
ICE reported 3.1 million active first-lien ARMs, equal to 5.6% of active mortgages. Roughly one-third of those loans had begun adjusting. More than 90% of ARMs originated since 2022 were still in their introductory fixed-rate periods, so the low current count reflects when loans were originated and how long their initial terms last—not an absence of ARM borrowers.
Why so few ARMs are adjusting now
Many loans currently beyond their first fixed period were originated more than a decade ago and have already gone through rate adjustments, including during the Federal Reserve’s 2022–2023 tightening cycle, ICE says. Meanwhile, most ARMs originated since 2022 have not yet reached their first reset. The count of loans adjusting today is therefore a snapshot of loans that have exited their initial fixed periods, not a measure of all future exposure.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →#1 Best Overall

- DEDICATED FUNCTION KEYS for Quick Financial Solutions: Clearly labeled function keys enable you to quickly and confidently provide financial answers and options for your clients, whether in the office, in the car or at an open house. Compare loan options and provide payment solutions to give your client choices
- INSTANT FINANCIAL PROBLEM SOLVING: Solve the financial questions your clients have whether they are buyers, investors or renters; increase your perceived professionalism and close more home sales by quickly answering real estate finance problems including remaining balances
- RESIDENTIAL REAL ESTATE FINANCE TERMS: Keys labeled in residential real estate finance terms like Loan AMT, Int, Term, PMT; Calculator is super easy to use to determine a mortgage loan that works for your client
- VERSATILE LOAN CALCULATION OPTIONS: Calculate 80:10:10 or 80:15:5 combo loans at the press of a button; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices
- COMES COMPLETE: Comes with a protective slide cover, quick reference guide, pocket user's guide, two long-life batteries, and 1-year warranty
ICE also reported that ARMs made up more than 11% of rate locks, the largest share in nearly four years. Its conforming 30-year fixed-rate index reached 7.2% on September 24, 2026. Those are dated market observations, not current quotes or forecasts, and can change as mortgage rates and borrower demand shift. ICE head of Mortgage and Housing Market Research Andy Walden said, “ARMs are becoming more attractive to borrowers looking for relief from today’s higher fixed rates, but the overall market exposure to adjustable payments remains relatively limited.”
What an ARM reset could mean for a monthly payment
ICE estimated that if underlying ARM indexes passed through a full 25-basis-point increase, the median affected borrower’s payment would rise by about $14 a month. For loans originated since 2022, ICE estimated an increase of about $53 a month under the same assumption. These are aggregate estimates, not calculations for a particular loan or borrower.
Rank #2

- PROFESSIONAL FINANCIAL CALCULATOR : Built-in TVM, IRR, NPV. Engineered for business analysts, real estate investors, accountants, and finance students.
- ADVANCED CASH FLOW & AMORTIZATION : Execute time value of money, break-even analysis, depreciation schedules, and bond pricing. Trusted for professional exam prep", MBA coursework, and banking certifications.
- CATIGA CF-300 : Flip-open hard case with a snap-close design for a secure fit. Compact and portable: designed for daily professional use in office, classroom, or on-site.
- ALL-IN-ONE FOR PROFESSIONALS : From NPV/IRR for real estate analysis to statistical calculations for business analysts. Handles probability, linear regression, and complex financial formulas.
- MORTGAGE, LOAN & INVESTMENT CALCULATOR : Covers bond pricing, loan amortization, investment analysis, and exam-level computations. Your go-to accounting calculator, business calculator, and real estate calculator in one device.
ICE also projected that about 74,000 seven-year ARMs originated in 2020 could face the largest median increase among resets expected next year: about $1,066 a month, or 36%. This is a projection, not a guaranteed payment change. The actual result depends on each loan’s terms and reset conditions.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to estimate your own reset
The ICE figures cannot tell an individual borrower what their next payment will be. The loan note and reset notice determine the calculation. Check these details in your documents or ask your servicer:
Rank #3

- SPEAKS YOUR LANGUAGE: Keys clearly labeled in residential mortgage finance terms like Loan AMT, Int, Term, PMT. This industry-standard calculator is super easy to use on all realty financing matters from finding a loan that works for your client to considering trust deeds investments, or finding remaining balances or balloon payments and much more
- CONFIDENTLY AND EASILY SOLVES: All your clients' financial questions whether they are buyers, sellers, investors or renters. Increase your perceived professionalism as a new agent, experienced broker or seasoned loan officer. Close more home sales and impress your clients with fast, accurate answers to all their real estate finance questions
- DEDICATED BUYER QUALIFYING KEYS: Enter client's income, debt and expenses to pre-qualify them to only show properties they can afford. Include tax, insurance and mortgage insurance then compare loan options and payment solutions to give your client choices before they make an offer to buy
- FIGURE OUT THE RIGHT LOAN: At the press of a button for jumbo, conventional, FHA/VA, or even 80:10:10 or 80:15:5 combo loans; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices; easily perform what if loan or tvm calculations Find loan amount, term, interest or PITI or PI payments
- BECOME AN INVALUABLE RESOURCE: Reduce your clients' confusion and uncertainty; ensuring they are able to make a purchase offer; knowing they can afford the down payment; and determining which is the right loan for them. Date-math for listings and contracts too. Comes with a protective slide cover, quick reference guide, pocket User's Guide, and long-life batteries
- Reset date and frequency: When the introductory period ends and how often the rate can change afterward.
- Index and margin: The benchmark used to set the new rate and the contractual amount added to it.
- Rate caps: Limits on the size of a change at each adjustment and over the life of the loan.
- Balance and remaining term: The principal still owed and the time left to repay it, both of which affect the payment calculation.
For a broader borrowing decision, compare the ARM’s initial rate and payment, introductory-period length, adjustment schedule, index, margin, and caps with the fixed-rate alternative. Also consider how long you expect to keep the home and whether your budget could absorb a higher payment. ICE’s report does not compare specific loan offers or recommend a loan for any household.
Quick Recap
Best Value
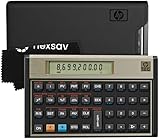
- HP 12C: INDUSTRY STANDARD SINCE 1981 – Trusted by professionals in real estate, banking, and finance for over 40 years. The HP 12C finance calculator remains the go-to tool for fast and accurate calculations in high-stakes business environments.
- 120+ FUNCTIONS FOR FINANCIAL ANALYSIS – Calculate loan amortization, bond pricing, mortgage payments, NPV, IRR, depreciation, and more with this large calculator. Built-in business and statistical functions allow you to perform complex calculations in just a few keystrokes.
- RPN ENTRY FOR FASTER WORKFLOWS – Reverse Polish Notation (RPN) allows for efficient data entry with fewer keystrokes and no formulas. This RPN calculator is perfect for a mortgage payment calculator, accounting calculator, business calculator, or real estate calculator for desktop.
- PROGRAMMABLE FOR REPEAT TASKS – The HP12C desk calculator stores custom keystroke sequences for repeated use. This large calculator supports up to 20 cash flows for IRR/NPV analysis, modeling investment scenarios, projecting returns, and automating routine calculations.
- INCLUDES CLEANING CLOTH, CASE & BATTERIES – Compact design fits easily on a desk or crowded table area. Includes a protective carrying case, cleaning cloth, and comes with pre-installed batteries so it's ready to use out of the box. A great choice for home finances, business professionals, and accountants.
Rank #4

- SPEAKS YOUR LANGUAGE: Keys clearly labeled in residential mortgage finance terms like Loan Amt, Int, Term, Pmt; this industry-standard calculator is super easy to use on all realty financing matters from finding a loan that works for your client to considering trust deeds investments, or finding remaining balances or balloon payments and more
- CONFIDENTLY AND EASILY SOLVE: Clients' financial questions whether they're buyers, sellers, investors or renters. Increase your perceived professionalism as a new agent, experienced broker or seasoned loan officer. Close more home sales and impress your clients with fast, accurate answers to all their real estate finance questions from PITI Payments to IRR, NPV and Cashflows
- DEDICATED BUYER QUALIFYING KEYS: Enter client's income, debt and expenses to pre-qualify them to only show properties they can afford. Include tax, insurance and mortgage insurance then compare loan options and payment solutions to give your client choices before they make an offer to buy
- FIGURE OUT THE RIGHT LOAN: For your client at the press of a button for jumbo, conventional, FHA/VA, or even 80:10:10 or 80:15:5 combo loans; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices; easily perform what if loan or TVM calculations find loan amount, term, interest or PITI or PI payments
- BECOME AN INVALUABLE RESOURCE: To your clients by reducing their confusion and uncertainty; ensuring they are able to make a purchase offer; knowing they can afford the down payment; and determining which is the right loan for them. Date-math for listings and contracts too. Comes with a protective slide cover, quick reference guide, pocket user's guide, long-life battery, 1-year warranty
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




