Usually, you cannot transfer money just by entering a virtual card number. A virtual card is a digital payment credential; the money may be held in a linked wallet, a prepaid-card account, or an underlying deposit account. Find out where the funds are held, then use a withdrawal method that both the issuer and your bank support.
First, find out where the money is held
Check the card details in the provider’s app and the cardholder agreement. Determine whether the amount appears as a wallet balance or as a separate balance on a prepaid or other card account. The distinction matters: a wallet’s bank-transfer feature moves money from that wallet balance, while a card number does not automatically provide a way to withdraw funds to a bank.
For example, Cash App’s U.S. terms describe transferring a Cash App Balance to a linked account, while its separate prepaid-card agreement describes the virtual card as a way to make purchases using Cash App funds. Those are different features, not a general promise that a virtual card can send its funds to any bank. See the Cash App terms and Cash App Card Agreement.
Choose a transfer route the provider supports
If the money is in a wallet balance
Open the provider’s official app and look for a feature labeled “Transfer,” “Withdraw,” or “Cash out.” Link a bank account in your own name, complete any required identity verification, and review the destination, timing, limits, and fee shown before confirming. Wallet cash-out is not the same as adding an outside virtual card as a funding method.
#1 Best Overall

- Get your money as soon as the next business day.
- Get set up quickly with no long-term commitments. Download the Square Point of Sale app for free, create an account, and start taking payments anywhere.
- Run your business all in one place with the free Square Point of Sale app. Track your sales, manage inventory, accept tips, send receipts digitally, and more.
- Works with Apple devices with a Lightning connector.
In the United States, Venmo says users can withdraw Venmo funds through a free standard transfer to a linked bank account or eligible debit card, or choose an instant transfer for a fee. Its instant-transfer help page says eligible U.S. transfers typically take 30 minutes and lists a fee of 1.75% of the transfer, with a $0.25 minimum and $25 maximum. Eligibility depends on the destination; these terms apply to Venmo balances and do not mean arbitrary virtual-card funds can be moved into Venmo. Check Venmo’s Instant Bank Transfer FAQ and its U.S. User Agreement for current terms.
Cash App’s U.S. terms allow Cash App Balance transfers to a linked account. They list instant-transfer fees of 0.5%–2.5%, with a $0.25–$1 minimum and a $75 maximum; check the fee presented for your transaction. These figures describe Cash App’s balance-transfer feature, not a universal virtual-card fee. See the Cash App terms.
Rank #2
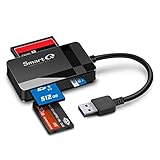
- SmartQ C368 USB 3.0 Card Reader: Four-in-one design, supports Micro SD/SD/MS/CF cards, and reads data independently; ideal for plug and play mobile use during travel.
- High data transfer speed: Supports data transfer speed up to 5GB per second (at USB 3.0 speed), compatible with USB 3.0 and USB 2.0 multi-card readers for CF and MicroSD cards.
- Multi-system compatibility: Compatible with Windows/Mac OS/Linux and other systems, no driver needed, enjoy a plug and play experience.
- Working status: Blue LED light indicator, the indicator LED lights up when powered on, the device status is clearly visible.
- In the Box: SmartQ C368 USB 3.0 Card Reader (memory card not included), Cable organizer, User manual.
If the money is on a card account
Ask the issuer whether it supports withdrawing the card balance to a bank or transferring it to an eligible external card. The receiving bank or card provider must also accept the transaction. Some issuers offer a permitted cash-access option, such as an eligible ATM or point-of-sale withdrawal, but access can depend on the card agreement and may require a physical card, PIN, or other access method.
Options differ by provider. Revolut’s U.S. personal terms describe transfers to non-Revolut accounts and instant card transfers to eligible external debit, credit, or prepaid cards; fees, limits, and requirements apply. Confirm the current conditions in Revolut’s U.S. personal terms.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Rank #3

- Use the, easy-to-use, and customizable POS to get started.
- Accept contactless payments, chip cards, Apple Pay, and Google Pay from anywhere, with improved connectivity, extended battery life, and enhanced security. Pay one low rate for every tap or dip.
- No long-term commitments or contracts, no monthly fees- and with offline payments, keep taking payments for up to 24 hours.
- Safely and securely accepts payments anywhere. Plus, get data security, 24/7 fraud prevention, and payment-dispute management at no extra cost.
- Use the, easy-to-use, and customizable POS to get started.
If the issuer does not offer a direct route
A specialist money-transfer service may accept some prepaid cards as a way to fund a transfer to a bank account, but acceptance depends on the specific card and destination. Wise advises checking whether the exact card is supported before relying on this option; its guidance is general and dates to 2023. Start with Wise’s prepaid-card transfer guide, then confirm eligibility and the total cost with the service.
Compare the route before you confirm
- Eligibility: Confirm that your issuer permits the transaction and that the destination bank or card participates. A payment card accepted for purchases is not necessarily eligible to receive a transfer.
- Total cost: Check the provider’s fee, any card-issuer charge, ATM or network surcharge, and currency-conversion cost if applicable.
- Timing: Compare standard and instant options. Settlement delays, reviews, weekends, or service disruptions can affect arrival time.
- Limits and verification: Check per-transfer and account limits, identity checks, account ownership requirements, and whether names must match.
- Support and reversibility: Find out whether a pending or rejected transfer can be recalled and which provider to contact if it goes wrong.
What to do if a transfer fails
A transfer may be declined or delayed because the card or bank is ineligible, account details or names do not match, the account is not verified, the issuer blocks cash-like transactions, or the provider is reviewing the payment. Venmo notes that instant transfers can be reviewed, declined, or delayed, and that participating institutions and matching names matter; see its Instant Bank Transfer FAQ.
Rank #4

- Fully Compliant - Complies With All Major Industry Standards, Including Iso/Iec 7816, Usb Ccid, Pc/Sc, And Microsoft Whql. As Well As, Emv 2011 Ver 4.3 Level 1 And Gsa Fips 201.
- Seamless Integration - With Identiv-Specific Smartos You’Ll Get Easy, Complete Support Of All Major Contact Smart Card Ics And Technologies In One Simple Reader.
- Universal Compatibility - Works With Virtually All Contact Chip Cards And Pc Operating Systems, Including Windows, Macos, Linux And Android.
- Fast And Convenient- Shorten Your Transaction Time With A Reader That’S Optimized For Speed. It’S Ultra-Compact And Robust Design Is Streamlined For Mobile Operation, Making This Reader The Best Choice For Convenience, Security And Reliability.
- Ergonomic and cost efficient design
- Check the transaction status and error message in the provider’s app.
- Confirm the destination details, account ownership, eligibility, and any verification requirements.
- Contact the issuer or transfer provider through its official app or support channel to ask which route is permitted.
- Do not repeatedly retry a declined transfer or disguise it as a merchant payment or peer-to-peer transaction.
Transfer only to an account you own unless the service explicitly permits sending funds to someone else. Rules and options vary by country, card type, issuer, balance source, and destination, so rely on the current agreement and the fee and eligibility information shown for your specific transaction.
Quick Recap
Best Value

- INTEGRATED DESIGN - The integrated-designed BENFEI USB-C/USB 3.0 card reader provide high data speed access to four different card types, the SD(Secure Digital), Micro SD(TF), MS(Memory Stick) and CF(Compact Flash). And with 2in1 USB-C/USB 3.0 design, BENFEI card reader could works with computer or laptop by USB 3.0/2.0 slot or the latest USB Type-C(Thunderbolt 3) slot. A universal card reader solution.
- INCREDIBLE PERFORMANCE - With latest USB Type-C or the USB 3.0 port, fully enjoy the transfer rates in UHS-I mode up to 160MB/sec, backward Compatible with USB 2.0/1.1. Browse and view photos instantly on your USB-C/USB3.0 smartphones/laptops. (NOTE: The final data speed is decided by the card and USB slot Type )
- SUPERIOR STABILITY - Built-in advanced IC chip handle the USB-C/USB high speed data transfer signal, allow HD movies trasfer in just seconds. ✅ It is a simultaneously card reader and can read 4 card at the same moment
- BROAD COMPATIBILITY - Compatible with MacBook Pro 2019/2018/2017/2016, MacBook 2017/2016/2015, iPad Pro 2018, Surface Book 2, Samsung Galaxy S10/S9/S8/Note 8/Note 9, HTC U11/U12, Pixelbook, Dell XPS 15 / XPS 13, Galaxy Book, and many other USB-C Devices. NOTE: SDXC cards (capacity at 64GB or larger) use a special file format "exFAT", which is not supported in Windows XP, Windows Vista before SP1, and Mac OS X before 10.6.6). ❗ Incompatible with Memory Stick (Standard),Memory Stick Micro (M2) and CF Type I
- 18 MONTH WARRANTY - Exclusive BENFEI Unconditional 18-month Warranty ensures long-time satisfaction of your purchase; Friendly and easy-to-reach customer service to solve your problems timely.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




