When lenders tighten mortgage standards, improve your odds by presenting a complete, accurate application that clearly documents your ability to repay—and by asking more than one lender how its current criteria apply to your situation. There is no single federally prescribed credit-score floor or debt-to-income cutoff for every U.S. mortgage. This guide is U.S.-focused; mortgage rules and terminology vary by jurisdiction.
What lenders assess—and what tightening standards mean
U.S. federal ability-to-repay rules require a creditor to make a “reasonable and good faith determination” that a borrower can repay a covered mortgage. The assessment considers a repayment picture, not just a credit score or down payment. The CFPB regulation identifies factors including income or assets, employment status, current obligations, monthly debt-to-income ratio or residual income, and credit history.

As an Amazon Associate I earn from qualifying purchases.
The rule does not set one minimum credit score or a specific debt-to-income ratio or residual-income threshold for every loan. Creditors develop their own underwriting standards, which may vary by lender and loan product and can change over time. A denial from one lender therefore does not establish that every lender will reach the same decision; another lender may assess the application differently, but approval is never assured. See the CFPB’s interpretation of the rule for further explanation.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
When standards become more restrictive, a lender may be less willing to accept uncertainty in an application. The practical response is to make the information it relies on easy to verify, reduce avoidable concerns where feasible, and ask directly about criteria for the specific loan and borrower profile. Federal rules require creditors to verify income or assets they rely on using reasonably reliable third-party records; Fannie Mae’s comprehensive risk-assessment guidance also describes supporting documentation for employment, income, assets, credit history, and other qualifying information.
#1 Best Overall

- Organize all your mortgage paperwork quickly and easily with mortgage folders an indexed divider sets.
- Includes a preprinted form for mortgage applicant's basic information and an inventory checklist to keep track of documents added to the folder.
- Eight dividers per Set
- Contains 10% recycled content, 10% post-consumer material
That is why a single number rarely tells the whole story. A lender may consider how dependable the income appears, what obligations are already due each month, what the credit history shows, and how much equity and liquid savings the borrower has. Fannie Mae describes a comprehensive risk assessment rather than a decision based on one factor alone. A stronger showing in one area does not automatically cancel a concern in another, and the importance assigned to particular facts can depend on the lender and loan product.
“Tighter standards” also does not necessarily mean that every borrower faces the same new rule. It can mean that a lender changes its own criteria or becomes more cautious about a particular loan type or applicant profile. Since federal ability-to-repay requirements allow creditors to develop underwriting standards, ask what applies to the loan you are considering now instead of relying on a friend’s older experience or a generic online cutoff.
Prepare before you apply
The FTC puts the timing plainly: “The best time to improve your chances of getting approved is before you even apply.” Use the lead time to check what a lender may see, organize documentation, and understand the full monthly cost you are asking to take on. The steps below are preparation, not a formula that guarantees approval.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →A useful first move is to make a simple preparation list: credit-report issues to check, income and asset records to gather, monthly obligations to total, and questions to ask lenders. This helps surface missing information before it becomes a last-minute request. There is no universal checklist or number of weeks that fits every application, so ask the lender how early it needs particular records and how it wants them submitted.
1. Review your credit reports and address inaccuracies
Obtain and read your credit reports early enough to dispute information that is inaccurate. If a report shows a past-due balance you believe is correct, contact the creditor to understand what is owed and resolve it if possible. The FTC’s mortgage guidance recommends checking report accuracy and addressing debts before applying.
Do not assume that paying a particular account will raise a score by a fixed number of points, or that every reported item can be changed simply by disputing it. Focus on correcting errors and making your financial picture accurate. If you are unsure how a debt or disputed item will affect an application, ask the lender what information it uses and how to document a correction.
Work through the report systematically. Check that the accounts and balances shown are familiar, look for information you believe is inaccurate, and note any account that needs follow-up with a creditor or reporting process. Keep a record of what you disputed or resolved and any response you receive. If an item is accurate, do not describe it as an error; instead, ask the creditor what remains owed and ask the lender how it will treat that obligation.
Recommended Free Tools
Credit history is one element of the repayment assessment, not a substitute for documenting income, assets, and obligations. Reviewing reports early gives you time to investigate discrepancies and to avoid being surprised by information a lender may see. It does not guarantee a particular score or loan result.
2. Map your income, employment, assets, and obligations
Before completing an application, make a clear inventory of the income and assets you expect to document, your employment situation, and your recurring financial obligations. Use accurate figures and be ready to explain changes that could otherwise be unclear. Lenders must verify the qualifying income or assets on which they rely, and the supporting records needed will depend on your circumstances and the lender’s process.
For self-employment, variable earnings, a recent job change, or another non-standard income pattern, ask how that income will be evaluated and which records the lender needs. Do not assume that one lender’s treatment automatically applies at another. The goal is to learn early whether the income you expect to use can be documented and considered under that lender’s rules.
Make the inventory specific enough to compare with the lender’s questions: identify the sources of income or assets you expect to rely on, list regular monthly debt payments, and note employment or income changes that may need explanation. Do not inflate or round figures to make them look stronger. If you are uncertain which figure belongs on an application or how a particular income source is treated, ask the lender before submitting it.
For a borrower with variable or self-employment income, the important question is not simply whether income varies; it is what the lender can verify and how its criteria evaluate that information. Ask for the requested records and how the lender will use them. If a recent change affects your income or employment, explain it accurately rather than assuming the lender will infer the reason from a document.
3. Organize records as the lender requests them
Keep requested information together and submit complete, legible records through the lender’s stated process. Depending on the application, the lender may ask for documentation relating to income, assets, employment, debts, credit history, and funds for the down payment. There is no universal document list in the cited guidance, so ask for the exact requirements for your application rather than relying on a generic checklist.
Be consistent across the application and its supporting records. If a deposit, transfer, employment change, or other item needs explanation, ask the loan officer what documentation would make it clear. Do not guess at figures or omit information because it seems inconvenient: the lender is assessing what it can verify.
A practical way to reduce avoidable back-and-forth is to keep a copy of what you send and track which items the lender has requested, submitted, or still needs. Use the lender’s preferred process and ask if a document is incomplete or difficult to obtain. A folder or application organizer can help keep records together, but it is optional and has no direct effect on underwriting. The quality and relevance of the information—not the container it is stored in—matter.
Fannie Mae’s guidance calls for supporting information in the loan file for employment, income, assets, credit history, and other qualifying information. That does not mean every borrower will be asked for the same papers. The lender determines what it needs for the specific case, and it may request additional information when something in the application needs clarification.
4. Avoid unexplained financial changes during the process
While preparing and during underwriting, avoid taking on new debt or making significant financial changes without first asking your loan officer how they could affect the application. This is prudent caution, not a universal rule that every change will cause a denial. If a change is necessary, explain it promptly and ask what records the lender needs to reassess the application.
Do not treat this as a reason to hide a change or postpone telling the lender about it. A new obligation, a change in employment, or a movement of funds may affect information the lender is reviewing, but the consequences depend on the facts and the lender’s criteria. Ask before acting when possible; if the event has already happened, provide accurate information and ask what documentation is needed.
Rank #3

- DESIGNED FOR MORTGAGE PROFESSIONALS: Tailored specifically for lenders and bankers, our mortgage paperwork separators streamline filing, ensuring every stage of the application is organized and accessible.
- STAY ORGANIZED: Keep your documents neatly categorized with 8 distinct, pre-printed color-coded tabs. Enhance your office’s overall organization, perfect for mortgage files and mortgage loan file folders.
- BOOST EFFICIENCY: Our mortgage index sheets feature dual-sided printing and colored tabs for enhanced visibility, allowing quick location of paperwork and boosting productivity.
- PROFESSIONAL PRESENTATION: Enhance your mortgage files with a polished, professional look. The high-quality manila stock and vibrant color-coding offer a visually appealing and functional solution.
- USA MADE: Proudly manufactured in America using high-grade materials, these divider tabs deliver unparalleled quality and longevity for your office filing solutions.
Understand the whole monthly housing cost
Compare the expected housing obligation with your existing monthly debts, not just the advertised or quoted mortgage payment. The federal repayment framework includes applicable taxes and insurance as well as mortgage-related obligations. Depending on the loan, the payment picture may also include mortgage insurance and other charges. Ask the lender to identify the items included in its calculation and clarify any payment that may change over time.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsWrite down the estimated components separately so you can see what is included and what may be missing from a headline payment figure. Ask whether the estimate includes taxes, insurance, and applicable mortgage insurance, and whether it represents an initial payment or one that could change. If a lender uses different assumptions from another, ask it to explain the difference before comparing offers.
Also put existing monthly obligations beside the proposed housing cost. The ability-to-repay framework includes current obligations, so a mortgage payment cannot be considered in isolation. Do not assume that an expense is excluded simply because it is not a mortgage; ask the lender which obligations it counts and how it treats them.
Debt-to-income ratio is one way a lender may assess monthly obligations relative to income; residual income is another way of looking at what remains after obligations. The federal rule does not impose one universal cutoff for either measure. Rather than treating an online ratio as a pass/fail guarantee, ask the lender which obligations it counts, how it calculates the relevant measure, and whether it has concerns about your complete repayment picture.
These measures are not interchangeable promises of approval. The CFPB interpretation explains that the rule does not establish a specific DTI or residual-income threshold. A calculator may help you organize your own estimates, but it cannot tell you how a particular lender will apply its standards or whether the lender can verify the information you enter.
Free tools Windows power users keep installed
One-click scans. No signup required.
Choose a down payment with cash reserves in mind
A down payment can affect loan options, but it is not a guarantee of approval and the cited sources do not establish one universal required amount. The FTC notes that down-payment amount can affect loan type. Fannie Mae’s risk assessment includes equity investment and liquid reserves among the factors considered. That makes it worth discussing both how much cash you plan to put down and what savings you would retain afterward.
Do not assume that using every available dollar for the down payment is automatically the strongest application. Ask how the lender will treat your proposed down payment, any applicable mortgage insurance, cash needed to close, and remaining liquid savings. Requirements and consequences depend on the specific loan and lender; no general reserve amount can be inferred from the cited guidance.
When comparing possible down-payment amounts, consider the trade-offs rather than focusing on one figure. Ask what each amount would mean for the available loan options, estimated cash to close, any mortgage insurance, and the liquid funds remaining. A higher down payment may affect the options available, but the appropriate choice depends on the loan and the borrower’s finances. Do not assume that paying more upfront guarantees a better decision or that retaining savings will satisfy a lender’s requirements.
Ask lenders questions that reveal their actual criteria
Because lenders retain discretion in developing underwriting standards, ask several lenders how their current requirements apply to your circumstances. Shopping does not guarantee that another lender will approve you, but it can help distinguish a lender-specific concern from a broader issue and show whether another loan option is worth discussing.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Rank #4

- 25 pt. pressboard cover contains eight 11 pt. Manila dividers (Insurance, Tax & Assessment Receipts, Mortgage, Title Papers, Attorney's Opinion, Appraisal, Credit Reports, Application).
- Front divider has preprinted form for applicants basic information and an inventory checklist.
- Includes a manila jacket for papers that cannot be punched.
- Dividers are held by top position 2" "K" style fastener, which also binds transaction papers.
- Matching color Tyvek tape.
When you contact a lender, describe your situation consistently. Ask about the exact loan type you are considering and the evidence you can provide, especially if your income varies or has recently changed. A useful answer should clarify what the lender needs to evaluate—not just offer a general assurance that you should apply.
- What documents do you need to verify my income, assets, employment, debts, and down-payment funds?
- Which monthly obligations do you include, and how do you assess debt-to-income ratio or residual income?
- How do you evaluate variable, self-employed, or recently changed income, and what records support that income?
- Are there other loan options that may fit my circumstances, and how would their payment, cash-to-close, or documentation requirements differ?
- What is included in the estimated monthly payment, including taxes, insurance, and any applicable mortgage insurance? Could the payment change later?
- What fees, timing expectations, and additional documentation should I plan for?
- If you cannot approve this application as presented, can you explain the factors behind the decision and what information or circumstances would need to change?
Compare the answers on the terms that affect your finances, not solely on the quoted interest rate. A useful comparison includes total monthly payment and possible changes to it, down payment and cash to close, any mortgage insurance, treatment of income and obligations, documentation, fees, and timing. If considering a fixed-rate and adjustable-rate option, compare the payment after any introductory period as well as the initial payment. Current rates, eligibility, and product terms vary and are not established by the federal and consumer guidance cited here.
It can help to put each lender’s answers side by side. Record the payment estimate and what it includes; the down payment and cash to close; any mortgage insurance; how the lender says it will assess your income and obligations; and the documents, fees, and timing it describes. If one answer is unclear, ask a follow-up rather than assuming the lenders use the same assumptions. Comparisons are most useful when they are based on the same loan type and the same financial facts.
Ask lenders to distinguish a general eligibility discussion from a decision on a complete application. A preliminary conversation can help you understand criteria and prepare, but it is not a guarantee that the lender will approve the loan after reviewing and verifying the full file. Likewise, a different product may change the payment or documentation requirements, so compare the full terms that matter to your budget rather than treating any option as automatically superior.
If a lender says no
Ask the lender to explain the decision and clarify which factors it considered. Review the application for incorrect or incomplete information, confirm whether any reported credit issue is accurate, and find out whether the lender needs additional documentation. If the issue is tied to that lender’s criteria or a particular product, you can ask other lenders whether their standards or available options differ. Do not treat a new application as a way to conceal or contradict information; provide accurate details to every lender.
If you identify an error in a credit report, pursue correction with the appropriate reporting or creditor process and ask the lender how it handles an item under review. If the obstacle is a recurring obligation or unclear income documentation, ask what evidence or change would address that specific concern. The answer may be that a lender cannot proceed under its current criteria; another lender’s review may differ, but no change guarantees approval.
Separate issues that can be clarified from issues that require a change in your circumstances. For example, a missing record may be addressed by providing documentation, while an accurate debt or income concern may require a different discussion with the lender. Ask what specifically would need to change before making a decision about applying elsewhere or considering another loan option. Do not assume that paying a debt, increasing a down payment, or correcting a report will produce a particular result; ask how the lender would assess the change.
If another lender is willing to discuss the application, share accurate information and ask how its criteria differ. A second review is a chance to learn whether standards or options differ, not a reason to omit an obligation or present a conflicting account of your finances. Keep records of the explanations and documents you receive so you can follow up consistently.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Keep the guidance in its proper jurisdiction
This article addresses U.S. mortgage applications. Rules, lender practices, and terminology differ by country, so U.S. federal requirements should not be applied to borrowers elsewhere. For example, the UK Financial Conduct Authority published a proposal on June 9, 2026, concerning mortgage access in the UK. That announcement is specific to the UK and is not a U.S. lending rule.
Best Value
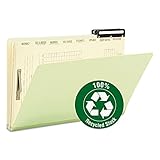
- Sold as 10/Box.
- Front divider has preprinted form for applicants basic information and an inventory checklist.
- Includes a manila jacket for papers that cannot be punched.
- Dividers are held by top position 2" "K" style fastener, which also binds transaction papers.
- Matching color Tyvek tape.
The FCA announcement described proposed changes intended to give UK lenders more flexibility for some applicants, including people with variable income and older borrowers, while maintaining protections. It was a proposal, not a rule to apply to U.S. borrowers. Applicants outside the United States should check the requirements and consumer guidance that apply in their own jurisdiction.
Frequently Asked Questions
Is there a minimum credit score or debt-to-income ratio required for every U.S. mortgage?
No single federal credit-score floor or DTI cutoff applies to every U.S. mortgage under the CFPB ability-to-repay rule. The rule also does not set a specific residual-income threshold. Lenders develop standards for their products, so ask the lender about the criteria for the loan you are considering.
What should I do before applying for a mortgage?
Review your credit reports for inaccurate information, address verified past-due debts where feasible, inventory income, assets, employment, and obligations, and ask lenders what records they need. Also estimate the full housing payment, including applicable taxes, insurance, and mortgage insurance, alongside your existing monthly obligations.
Does a larger down payment guarantee mortgage approval?
No. The FTC notes that down-payment amount can affect loan type, and Fannie Mae includes equity investment and liquid reserves among risk factors. The cited guidance does not establish a universal required down payment or reserve amount. Ask how a proposed amount affects loan options, cash to close, mortgage insurance, and remaining savings.
Should I apply with more than one lender if I am denied?
It can be useful to ask other lenders whether their current standards or available loan options differ. Federal rules leave creditors room to develop underwriting standards, so one lender’s decision does not prove another will decide the same way. A second review is not a guarantee of approval; provide accurate information to every lender.
What documents will a mortgage lender ask me to provide?
The exact list varies by lender and application. Lenders verify income or assets they rely on, and supporting records may relate to employment, income, assets, debts, credit history, and down-payment funds. Ask for the lender’s specific list and preferred submission process.
Can I take on new debt or change jobs while my mortgage is being reviewed?
The guidance here does not establish a universal ban on financial changes. As a prudent step, ask your loan officer before taking on new debt or making a significant change while preparing or in underwriting. If a change occurs, explain it accurately and ask what records are needed.
What should I compare besides the mortgage interest rate?
Compare the total monthly payment and possible future changes, down payment and cash to close, applicable mortgage insurance, how income and obligations are assessed, required documents, fees, and timing. For an adjustable-rate option, ask about the payment after any introductory period as well as the initial payment.
The Bottom Line
To improve your chances, make your application accurate, complete, and easy to verify; review credit early, document income and assets, understand the full housing payment and existing obligations, and ask multiple lenders how their current criteria apply to your circumstances. No score, down payment, or preparation step guarantees approval, and different lenders may reach different decisions.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




