Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →If you believe a U.S. credit-card bill contains an error, contact the card issuer promptly and follow its billing-dispute instructions. To preserve the billing-error rights described by the Consumer Financial Protection Bureau (CFPB), send written notice within 60 days after the statement containing the error was sent. “Non-negotiable chargeback request” is not an established official procedure; a charge reversal is not guaranteed, and the right route depends on what happened and how you paid.
What does “non-negotiable chargeback request” mean?
The phrase is not a recognized name for an official consumer chargeback process. An exact-title search result points to a user-uploaded document on Scribd, not to guidance from a card issuer, regulator, or card network. That upload does not establish that its purported method works or that it can force a credit to an account. Do not treat it as a guaranteed remedy or rely on its claims as legal or financial advice. View the user-uploaded document.
For a U.S. credit card, the practical starting point is to identify whether the problem is a billing error covered by the rules, then contact the issuer using its dispute process. People sometimes use “chargeback” to mean reversing a credit-card charge, but the term does not make every merchant disagreement a billing error or guarantee that the issuer will reverse a payment.
How do I dispute a credit-card charge?
- Check the statement. Identify the transaction, amount, and statement on which it first appeared. Note why you believe it is wrong.
- Contact the issuer promptly. Call the number on the back of your card or on your statement and ask how to dispute the charge. The CFPB notes: “The customer service phone number appears on your monthly bill or on the back of your card.” Calling can help you understand the next step, but follow the issuer’s instructions for formal written notice.
- Send written notice to the billing-dispute address. For a billing error, CFPB guidance says to send notice no later than 60 days after the issuer sent the statement where the error first appeared. Use the address designated for billing disputes; it may differ from the address for payments. Keep a copy and records of when and how you sent it.
- Pay the undisputed part of the bill. While a qualifying billing error is being investigated, you may withhold the disputed amount, but you must continue paying charges that are not in dispute.
- Ask which process fits a merchant dispute. If the issue is defective goods, unsatisfactory service, or another disagreement about a purchase, ask the issuer whether a chargeback or a separate claims-and-defenses process applies. Do not assume the billing-error procedure covers every complaint.
These timeframes and protections concern U.S. credit-card billing errors. They should not be applied automatically to debit cards, payment apps, or other countries’ systems.
#1 Best Overall
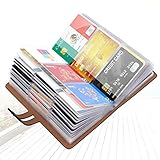
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
What should I include in a billing-error letter?
Make the notice clear enough for the issuer to identify the account and understand what you are disputing. Include:
- Your name and enough account information to identify the credit-card account.
- The transaction date, merchant, and amount, as shown on the statement.
- A plain-language explanation of what you believe is wrong and why.
- Copies of relevant records, if useful; keep the originals and a complete copy of what you send.
Send the notice to the issuer’s billing-dispute address, not automatically to the payment address. Check your statement or contact the issuer to confirm the correct address and accepted submission method.
Rank #2

- 【96 Card Pokets】: Our leather credit card holder is a good way to store your pocket-money, bank card, VIP card, name card, train ticket and more. It's the best choice to keep the cards neat and prevent loss.
- 【Blocking Design】: The business card book has a blocking designed lining, can block thieves through scanning technology to steal your identity card information, credit card, bank card and other information, this keeps your vital information in driver license, debit cards and credit cards from being stolen.
- 【Portable and Convenient】: The dimensions of the business id card case: 7.5" x 4.3" x 0.8". The slim profile and light-weighted design make this business card holder easy to carry. Keep your business cards nice, neat and at hand all the time.
- 【Durable Material】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【Unique Appearance】: With the elegant and sleek look, book-style card holder can get you more admire and opportunity. It's an ideal gift for your family, friends, clients, associates, or as a company souvenir.
What happens after the issuer receives a written notice?
Under CFPB consumer guidance, the issuer generally has 30 days to acknowledge receipt of a written billing-error notice and another two billing cycles to complete its investigation. These are procedural timeframes for the credit-card billing-error process, not a promise that the issuer will decide in your favor. Keep paying undisputed charges while the matter is pending.
Regulation Z’s billing-error definition includes certain unauthorized transactions and charges for goods or services that were not accepted or delivered as agreed. It also provides separate procedures for asserting claims or defenses for some purchases. Whether a particular merchant dispute qualifies depends on the facts and the applicable process. See the CFPB’s Regulation Z billing-error resolution rule.
Rank #3
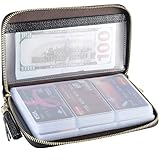
- Material: Genuine Cowhide Leather and PVC card slots.
- Size: 7.48"*3.54"*0.98" (19*9*2.5 CM)
- Large Capacity: The card holder has 60 cards slots and 2 ID Windows. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking Design: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift: Great gift for mother, daughter, grandmother and so on.
Billing error or purchase dispute: which route should I ask about?
| Issue | Billing-error notice | Purchase dissatisfaction or chargeback inquiry |
|---|---|---|
| Starting point | Identify a billing error covered by credit-card rules, such as certain unauthorized or incorrectly handled transactions. | Ask the issuer whether the specific merchant or goods-and-services dispute may qualify for a chargeback or another claims-and-defenses process. |
| Procedure | Follow the issuer’s billing-dispute instructions and send written notice within the applicable deadline. | Contact the card company; the available route depends on the dispute and card terms. |
| Key caution | Keep a copy of your notice and pay undisputed charges. | Not every merchant disagreement is a billing error, and a reversal is not automatic. |
The CFPB says that “In some cases, the credit card company can reverse the charge.” That possibility is not a guarantee. Its guidance on getting a refund for a credit-card purchase explains why contacting the card company is a sensible next step when you are unsure which route applies.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Sources and scope
This is general information for U.S. consumer credit cards, not individualized legal advice. The CFPB’s billing-error guidance was modified June 4, 2025: How to fix mistakes in your credit card bill. Its purchase-refund guidance was reviewed May 15, 2024. Different rules or procedures may apply to debit cards, payment apps, business accounts, and transactions outside the United States.
Quick Recap
Best Value

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
Rank #4
- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




