Set your phone budget from the cash you can safely spare after essentials, existing debt payments and a sensible emergency buffer—not from the smallest advertised monthly payment. If your current phone still works, saving that amount until you can pay the full price is usually the simplest way to avoid a new obligation. If you need a replacement sooner, choose the least expensive phone that meets your actual needs, then compare the full repayment and conditions of every financing option.
The key calculation is: maximum phone budget = cash available after essentials, obligations and buffer. Include taxes and required fees, and treat accessories as optional unless you genuinely need them. A financing plan is affordable only when every payment fits that cash flow without forcing you to miss other bills or draw down your safety buffer.
As an Amazon Associate I earn from qualifying purchases.
1. Find an affordable target before looking at payment plans
Check whether the purchase is urgent
Write down what is wrong with your current phone and whether it prevents essential tasks such as calls, authentication, work or safety communications. If it still performs those functions, estimate how many months you could continue using it while saving. The Federal Trade Commission (FTC) specifically asks consumers: “If you wait a few months, could you save up enough to pay the full cost instead of using a payment plan (and paying more over time)?” That question appears in its December 2022 consumer advice, Want to buy now and pay later? Read this first.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallIf the phone has failed and you need one immediately, separate essential requirements from preferences. For example, reliable calls, operating-system support, storage for your normal apps and compatibility with your network may matter; a premium camera or the newest processor may not. Define those requirements before viewing models so a promotional payment does not push you into a more expensive device.
#1 Best Overall

- YOUR CONTENT, SUPER SMOOTH: The ultra-clear 6.7" FHD+ Super AMOLED display of Galaxy A17 5G helps bring your content to life, whether you're scrolling through recipes or video chatting with loved ones.¹
- LIVE FAST. CHARGE FASTER: Focus more on the moment and less on your battery percentage with Galaxy A17 5G. Super Fast Charging powers up your battery so you can get back to life sooner.²
- MEMORIES MADE PICTURE PERFECT: Capture every angle in stunning clarity, from wide family photos to close-ups of friends, with the triple-lens camera on Galaxy A17 5G.
- NEED MORE STORAGE? WE HAVE YOU COVERED: With an improved 2TB of expandable storage, Galaxy A17 5G makes it easy to keep cherished photos, videos and important files readily accessible whenever you need them.³
- BUILT TO LAST: With an improved IP54 rating, Galaxy A17 5G is even more durable than before.⁴ It’s built to resist splashes and dust and comes with a stronger yet slimmer Gorilla Glass Victus front and Glass Fiber Reinforced Polymer back.
Calculate your monthly room
Use take-home income, not gross salary. Subtract recurring essentials, minimum and required debt payments, and an emergency contribution that you are genuinely able to maintain. Do not apply a universal percentage: the safe amount depends on your income stability, household costs and other commitments.
monthly phone contribution = take-home income − essential expenses − required debt payments − chosen buffer contribution
Use a conservative figure if income varies. A contribution that works only in your best month is not sustainable. Also account for annual or irregular bills by setting aside money for them before declaring cash available for a phone.
Free tools Windows power users keep installed
One-click scans. No signup required.
Set an all-in ceiling
Your ceiling should include the device price, sales tax or VAT, delivery, activation and other required charges. Add a case, charger or screen protector only if you need one and do not already have a compatible item. Do not set the ceiling from a “per month” advertisement; that figure may exclude a deposit, taxes, fees, a final payment or a required service plan.
Turn the ceiling into a saving date
If the all-in cash price is C and your sustainable monthly contribution is S, the minimum saving period is ceil(C ÷ S) months. For an illustration, a $600 all-in target and a $100 monthly contribution require six months. The numbers are examples, not a recommended budget or a prediction of any particular phone’s price.
Rank #2

- Blazing-fast Qualcomm performance. Get the speed you need for great entertainment with a Snapdragon 680 processor and 4GB**** of RAM.
- Fluid display + immersive stereo sound. Bring your entertainment to life with an ultrawide 6.5" 90Hz* HD+ display plus stereo speakers, Dolby Atmos, and Hi-Res Audio**.
- 50MP*** Quad Pixel camera. Capture sharper, more vibrant photos day or night with 4x the light sensitivity.
- 64GB**** built-in storage. Get plenty of room for photos, movies, songs, and apps—and add up to 1TB more with a microSD card*****.
- Unbelievable battery life. Work and play nonstop with a long-lasting 5000mAh battery.*****
| Illustrative item | Amount |
|---|---|
| Take-home income | $3,200 per month |
| Essentials | $2,200 per month |
| Required debt payments | $300 per month |
| Emergency and irregular-bill buffer contribution | $200 per month |
| Available phone contribution | $500 per month |
| Illustrative all-in phone target | $600 |
| Saving time at that contribution | Two months (if the full $500 can be used each month) |
In practice, you might choose to save less than the mathematical maximum so that a surprise expense does not force you to borrow. Keep your phone target below the ceiling when your income or expenses are uncertain.
2. Compare paying cash, financing and bundles by total cost
List each offer in the same format. Record the upfront amount, every scheduled payment and date, total repayment, interest, one-time and recurring fees, and any service commitment. A low monthly figure is not evidence of a low price.
| Payment path | What it can do | Costs and obligations to verify |
|---|---|---|
| Save and pay in full | Avoids a new credit account and generally avoids financing charges. | Time spent saving; an interim phone may be needed if the current one fails. Cash price, tax and required fees still apply. |
| Retailer installment or BNPL plan | Lets you receive the phone before saving the full amount; BNPL commonly uses little or no initial payment and four or fewer payments, according to the CFPB. | Total repayment, interest or fees, application or purchase-by-purchase credit evaluation, reporting, late consequences, automatic-debit risk and return handling vary by lender and contract. |
| Carrier financing or bundle | May combine a phone with data or airtime over a required term in some markets. | Total service charges, device price, lock status, eligibility, contract length, switching cost and early-payoff terms. GSMA’s examples are market-specific and do not establish availability where you live. |
| Credit-card installment conversion or split payment | May be available under a particular issuer or merchant program. | Not established generally. Confirm whether partial payment, post-purchase conversion, interest, fees and credit limits are allowed under your exact card and merchant terms. |
Use a side-by-side worksheet
Copy the following headings into a note or spreadsheet for every offer:
- Cash price, tax and required fees.
- Amount due today.
- Each installment amount and exact due date.
- Total of all payments.
- Interest rate and setup, account, delivery or other fees.
- Whether the application or each purchase involves a credit review.
- Whether payment history is reported to credit bureaus.
- Late fees, collection activity and any loss of promotional terms after a missed payment.
- How automatic debits work and whether your bank balance can cover them on the due dates.
- Return, cancellation, refund and dispute procedures.
- For a carrier offer: required plan, term, lock, eligibility, switching rules and early payoff.
- Whether the phone is compatible with your network and meets your actual requirements.
Compare total repayment with the cash price before considering the monthly amount. If the total is not clearly stated, ask the provider for a written schedule or do not accept the offer.
3. Understand retailer installments and BNPL
BNPL is credit, not a budgeting method
The Consumer Financial Protection Bureau (CFPB) describes a common BNPL structure as buying immediately with little or no initial payment and repaying in four or fewer payments. That is a description of a common arrangement, not a promise that every plan has four payments or no interest. Terms differ by lender and transaction, and the borrower may be evaluated each time they start a purchase.
Rank #3

- Please note, this device does not support E-SIM; This 4G model is compatible with all GSM networks worldwide outside of the U.S. In the US, ONLY compatible with T-Mobile and their MVNO's (Metro and Standup). It will NOT work with other CDMA carriers, and it is also not compatible with their MVNO (Visible, Xfinity Mobile, US Mobile, Cricket Wireless, etc).
- Compatibility with certain third-party devices and accessibility accessories, including some hearing aids, may vary depending on manufacturer support, Bluetooth protocols, software compatibility, and regional firmware limitations. For additional hearing aid compatibility information, please refer to Samsung’s official support documentation.
- Camera: 50 MP, f/1.8, (wide), 1/2.76", 0.64µm, AF | 50 MP, f/1.8, (wide), 1/2.76", 0.64µm, AF | 2 MP, f/2.4, (macro). Battery: 5000 mAh, non-removable | A power adapter is NOT included.
Read the loan or account agreement before clicking accept. Check whether the advertised “interest-free” period depends on on-time payments, whether a longer-term option carries interest, and whether any account or late fees apply. Do not describe a plan as consequence-free merely because the first payment is small.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Protect your bank account from automatic-debit problems
Many plans collect scheduled payments automatically. The CFPB warns that a missed payment can produce a lender fee and may also trigger your bank’s overdraft or insufficient-funds fee. Before authorizing a debit:
- Put every due date and amount on your calendar.
- Identify the account that will be charged and keep enough cleared funds in it.
- Ask how to change the payment date or payment method if your income arrives later.
- Find out how to stop or revoke an authorization and what alternative payment method is available.
- Check the account after each debit and act quickly if an amount is wrong.
Check credit effects and missed-payment rules
A provider may perform a credit check when you apply or whenever you initiate a new purchase. Payment information may or may not be reported to credit bureaus, depending on the lender and jurisdiction. A late payment can lead to fees, collection activity or credit-history consequences if the account reports it. The CFPB’s consumer guidance on BNPL fees identifies these risks; it does not establish one universal rule for every provider.
Plan the return before buying
Returning a phone does not necessarily cancel the financing automatically. Read the retailer’s return window, the lender’s cancellation process and the timing of refunds. Ask whether installments continue until the lender receives confirmation, whether shipping or restocking costs are deducted, and how an outstanding authorization is released. Keep receipts, tracking information and written confirmation of cancellation.
4. Evaluate a carrier phone-and-service bundle
In some markets, carriers sell a smartphone together with data or airtime and spread device payments across a service term. A 2025 GSMA report describes such acquisition models in particular markets; it is not evidence that a comparable offer is available or economical in your country.
Rank #4

- Please note, this device does not support E-SIM; This 4G model is compatible with all GSM networks worldwide outside of the U.S. In the US, ONLY compatible with T-Mobile and their MVNO's (Metro and Standup). It will NOT work with Verizon, Spectrum, AT&T, Total Wireless, other CDMA carriers, it is also not compatible with their MVNO (Visible, Xfinity Mobile, US Mobile, Cricket Wireless, etc).
- Compatibility with certain third-party devices and accessibility accessories, including some hearing aids, may vary depending on manufacturer support, Bluetooth protocols, software compatibility, and regional firmware limitations. For additional hearing aid compatibility information, please refer to Samsung’s official support documentation.
- 4G LTE Bands: B1/B3/B5/B7/B8/B20/B28/B38/B40/B41
- Display: Super AMOLED, 90Hz, 800 nits (HBM) | 6.7 inches, 110.2 cm2 (~86.0% screen-to-body ratio) | 1080 x 2340 pixels, 19.5:9 ratio (~385 ppi density)
- Camera: 50 MP, f/1.8, (wide), 1/2.76", 0.64µm, AF | 50 MP, f/1.8, (wide), 1/2.76", 0.64µm, AF | 2 MP, f/2.4, (macro)
Price the entire commitment, not just the device line. Add every required monthly service charge for the full term, activation and taxes, then compare that total with buying a compatible phone separately and choosing service independently. Confirm:
- Whether the device is locked to the carrier and the conditions for unlocking.
- Eligibility requirements, including credit, residency or existing-customer rules.
- Contract length and what happens if you cancel, switch service or miss a payment.
- Whether the remaining device balance becomes due when service ends.
- Early-payoff rules and whether promotional credits stop after a change.
- Coverage and network compatibility in the places you use the phone.
A bundle can be reasonable when you already need the service and the combined total is lower or more flexible than separate purchases. It is a poor fit when the service commitment costs more than the value of the phone or prevents a necessary switch.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.5. What to do when your credit-card installment limit is too low
Ask the issuer and retailer precise questions
Because installment features differ by issuer, country and merchant, do not assume you can split a purchase, pay down the card first or convert a transaction after checkout. Ask whether the program permits a partial amount, what credit limit must be available at purchase, when interest begins, whether a hard or soft credit inquiry occurs, and what happens if the purchase is returned. Obtain the answer in the card agreement or written offer.
Use a lower target rather than stretching the payment
If the desired phone exceeds your safe all-in ceiling, remove optional storage or accessories, consider a compatible lower-cost device, or wait until the target is saved. A smaller phone purchase that leaves room for rent, food, utilities and debt payments is safer than a flagship financed to the limit.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Consider a temporary solution when replacement is urgent
If your phone has failed but saving for your preferred model will take months, compare the least expensive device that meets your essential requirements. Check software-support expectations, network compatibility, condition and warranty before buying. A temporary, compatible phone can prevent a rushed high-cost loan, but include its price in your plan and avoid paying for features you will not use.
Best Value
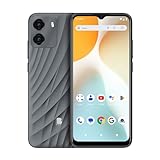
- GSM Unlocked: Enjoy seamless connectivity with your preferred GSM carrier. Compatible with T-Mobile, Metro PCS, AT&T, Cricket, Mint Mobile and other GSM networks. SIM card not included. For network compatibility, please check with your carrier. Note: Not compatible with CDMA networks like Verizon (Visible, Spectrum Mobile, US Mobile, Total Wireless, Straight Talk Wireless)
- Boundless Views: Enjoy immersive viewing on the spacious 6.5” HD+ display. Whether you're watching videos, browsing, or gaming, every detail comes through with stunning clarity.
- Smooth Performance, All Day: Powered by an efficient octa-core processor, the G35 ensures smooth performance for your everyday tasks. Enjoy faster app launches, seamless multitasking, and reliable speed.
- Snap, Share, Repeat: The G35 features a dual rear camera setup for sharp, detailed shots, and a front-facing camera that’s perfect for selfies and video calls. Capture every moment with ease and clarity.
- Effortless Access: Keep your phone secure with A.I. Face ID technology. Instantly unlock your G35 with just a glance. It's fast, easy, and secure.
6. Choose the path that matches your situation
When waiting is practical
Save the planned contribution in a separate, accessible account and set a target date. Recheck the cash price, taxes and availability near that date. If the price changes, adjust the target rather than automatically adding financing.
When you need a phone now
First identify the lowest-cost device that performs your essential tasks. Then compare the cash price with the full repayment of a retailer, BNPL or carrier offer. Accept a plan only if the payment dates fit your income cycle, the total cost is understood, and the contract does not create a service or lock-in problem you cannot afford.
When no offer fits
Do not treat an approval as proof of affordability. Lower the device target, delay the purchase, repair the current phone if that is economical, or seek a compatible alternative. If you would need to miss essentials, skip the buffer or rely on overdraft to make a scheduled debit, the plan does not fit.
7. Common budgeting mistakes and fixes
- Budgeting from the advertised monthly payment. Add the deposit, every installment, taxes, fees and any required service charges to find the true total.
- Calling BNPL free because no interest is displayed. Check late, account, collection and bank fees and the consequences of automatic-debit failure.
- Assuming a return erases the loan. Follow both retailer and lender cancellation procedures and retain written proof.
- Ignoring credit evaluation. Find out whether an application or each purchase is reviewed and whether payments are reported.
- Using the entire monthly surplus. Keep a buffer for irregular bills and income changes; no universal payment-to-income percentage is established here.
- Overlooking carrier lock and service obligations. Price the required term and switching or early-payoff costs before signing.
- Assuming credit-card rules are universal. Verify partial-payment and conversion features with the exact issuer and merchant.
- Buying more phone than your use requires. Set requirements first, then compare compatible devices within the ceiling.
8. Jurisdiction and regulatory cautions
The CFPB and FTC materials cited above are United States consumer guidance. They explain risks and questions to ask, but they do not determine the terms of a lender in another country. Check your local regulator and the contract that governs your purchase.
In the United Kingdom, the Financial Conduct Authority (FCA) states that regulation of Deferred Payment Credit, commonly called BNPL, began on 15 July 2026. That date applies to the UK regulatory setting and should not be generalized to other countries. Regulation does not remove the need to compare total repayment, fees, reporting and missed-payment consequences.
9. A final pre-purchase checklist
- Confirm whether the current phone can safely last through the saving period.
- Write your essential feature and compatibility requirements.
- Calculate an all-in cash ceiling, including tax and required fees.
- Calculate a sustainable monthly contribution after essentials, debt payments and a buffer.
- Get the cash price and written terms for each payment option.
- Compare total repayment, dates, fees, credit effects, automatic debits and return handling.
- For a carrier bundle, total the entire service commitment and check lock and switching terms.
- Ask the card issuer whether any partial or post-purchase installment feature actually applies.
- Reject any plan that requires overdraft, missed essentials or an exhausted emergency buffer.
- Save the agreement, receipts and cancellation instructions.
The safest phone budget is the amount you can pay without compromising necessities or your buffer. Financing can solve a timing problem, but it cannot make an unaffordable phone affordable; only a lower target, more time or more available cash changes that calculation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Scan for outdated or missing drivers - takes under a minute3Repair Windows errors before they cause bigger problems



