Free tools Windows power users keep installed
One-click scans. No signup required.
Yes, you can pay by UPI at some merchants abroad—but acceptance is selective. If your bank and UPI app support international payments, you can activate the feature, scan a participating merchant’s QR code, check the local-currency amount and the rupee amount shown in the app, then authorize with your UPI PIN. The app’s confirmation screen is the clearest place to see the amount you are agreeing to pay; it does not tell you the full settlement path or guarantee that every merchant in a supported country will accept UPI.
Can you use UPI internationally?
Indian UPI users can pay participating merchants abroad through international merchant acceptance, sometimes described as UPI Global Acceptance. It is not a universal way to pay anywhere UPI is available domestically: your bank account and app must be eligible, the international feature must be enabled, and the merchant must be connected through a supported local acceptance arrangement. A QR code that works with a local wallet or another payment network is not automatically a UPI QR.
NPCI directs users to check its current UPI Global Acceptance information for enabled locations, banks and apps. Network arrangements and participating locations can change, so confirm availability with your app or bank and look for the relevant acceptance sign at the merchant. NIPL describes the cross-border connection as operating through international network partners; it does not make every merchant in a listed market universally reachable through UPI.
How an international UPI merchant payment works
- Enable international payments. In a supported UPI app, activate the international or UPI Global feature for the eligible bank account you intend to use. The precise label and activation flow depend on the app.
- Check that the merchant accepts it. Look for a BHIM UPI or relevant network-partner acceptance sign, and confirm with the merchant if it is unclear. A supported country does not mean every QR there will work.
- Scan the merchant’s QR code. The app retrieves the payment request for that merchant and amount.
- Review the confirmation screen. Check the amount in the merchant’s currency and the corresponding amount in Indian rupees, along with any exchange rate or fee the app displays.
- Authorize with your UPI PIN. After a successful payment, NPCI says both customer and merchant should receive a payment notification.
The user-facing authorization and the behind-the-scenes movement of funds are different parts of the transaction. Your app presents the payment and records your authorization; international acceptance partners, participating banks and the relevant payment-system arrangements support processing across markets. Seeing a successful debit or confirmation in your app does not, by itself, establish when or in what currency the merchant’s acquirer pays the merchant.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstall#1 Best Overall

- Organize currency, passport and cards with 2 RFID shielded pouches.
- Multiple pockets with colorful zippers help organize more than one currency and made with water-resistant, diamond pattern ripstop
- Slim style, but roomy enough to manage money, cards, train tickets, receipts and more
- Size: Small: 7"x4.5" Large: 7.75"x5", Material: polyester, Weight: 0.13 lbs.
- Actual product colors and design details may vary slightly from images due to monitor settings and continuous rolling improvements.
Will UPI charge you in rupees or local currency?
The merchant’s price is generally presented in the local currency. Before authorizing, NPCI instructs users to review both the foreign-currency amount and the INR amount shown in the UPI app. Treat the rupee amount on that final screen as the key figure for deciding whether to proceed, and inspect any rate or fee disclosed there.
NIPL promotes transparent foreign-exchange rates and characterizes margins and fees for cross-border UPI person-to-merchant payments as “notably low.” That is a general statement by the network operator, not a published universal markup, a guarantee for every transaction, or a quantified comparison with cards, cash or travel-money services. The official material does not specify one conversion formula or timing rule that applies across all corridors, banks and apps. The applicable conversion and charges may depend on the particular bank, app and international payment arrangement. See NIPL’s interoperability overview and rely on the transaction display and your provider’s applicable terms.
Rank #2
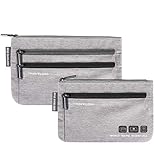
- Organize currency, passport and cards with 2 RFID shielded pouches.
- Multiple pockets with colorful zippers help organize more than one currency and made with water-resistant, diamond pattern ripstop
- Slim style, but roomy enough to manage money, cards, train tickets, receipts and more
- Size: Small: 7"x4.5" Large: 7.75"x5", Material: polyester, Weight: 0.13 lbs.
- Actual product colors and design details may vary slightly from images due to monitor settings and continuous rolling improvements.
If you are comparing payment methods for the same purchase, compare the final rupee cost shown or quoted, the rate and when it is applied, separately stated fees, whether the method works at that merchant, and the support available for disputes or refunds. The available UPI information does not establish that UPI is always cheaper or more widely accepted.
How does settlement work—and what is not publicly specified?
Settlement is the movement of funds among payment participants and the merchant’s acquiring arrangement after the customer authorizes a payment. NPCI’s general merchant FAQ says a merchant receives funds into its pool or bank account under its agreement with its acquirer. That guidance is not a service-level promise for international QR transactions.
Rank #3

- RFID Blocking: Organize currency, passport and cards with RFID shielded pouches. Anti-RFID (radio frequency identification), protect personal privacy, and prevent bank card theft.
- Material: This passport wallet is made with water-resistant, ripstop, durable, breathable, quick dry polyester.
- Pockets: The travel wallet is designed with multiple pockets with smooth zippers help organize more than one currency, features with 1 main compartment, 1 middle compartment with 4 card pockets, 1 front pocket and 1 back mesh zip pocket.
- Large Capacity: Slim style with roomy space, enough to manage and hold money, cash or coin, all currency from any countries, passports, cards, tickets of train and flight, receipt...
- Size: 7.87x5.71 inches with 0.18 pounds, lightweight, easy to carry with sided handle and and detachable handle. The sided handle can be hung keys.
NIPL’s financial statements for 2023–24 state that NPCI handled settlement of international scheme funds at the time covered by that report. The statement does not provide a complete, current, corridor-by-corridor description of how an individual international merchant QR payment is converted, cleared, settled in local currency or paid out, or how long each step takes. The public material also does not establish a universal settlement currency or intermediary sequence.
For that reason, a successful authorization should not be read as proof that the merchant receives funds instantly, in INR, or at a particular exchange rate. Those backend details depend on the relevant partners and acquiring arrangements and are not established as universal rules in the cited public sources. NPCI’s UPI FAQ provides general merchant guidance, while NIPL’s 2023–24 financial statements describe the historical settlement arrangement.
Rank #4

- Organize currency, passport and cards with 2 RFID shielded pouches.
- Multiple pockets with colorful zippers help organize more than one currency and made with water-resistant, diamond pattern ripstop
- Slim style, but roomy enough to manage money, cards, train tickets, receipts and more
- Size: Small: 7"x4.5" Large: 7.75"x5", Material: polyester, Weight: 0.13 lbs.
- Actual product colors and design details may vary slightly from images due to monitor settings and continuous rolling improvements.
Three different cross-border UPI services
| Service | Who uses it and in which direction | What it does |
|---|---|---|
| UPI Global Acceptance | An eligible Indian UPI user paying a merchant abroad | Enables QR payments at participating international merchant locations through a supported app, bank and acceptance partner. |
| UPI for NRIs | Eligible NRE/NRO account holders using supported international mobile numbers | Allows eligible users to link supported numbers to participating accounts and apps, subject to bank terms. It is not the same thing as merchant acceptance abroad. |
| UPI One World | International visitors paying merchants in India | An app-based prepaid wallet for inbound visitors. It is the reverse direction from an Indian bank-account holder paying a merchant abroad. |
For NRI mobile-number eligibility, check NPCI’s current UPI for NRIs live-members list and your bank’s terms. The participating country codes, banks and apps are subject to change; a listed number or bank alone does not guarantee support in every app.
NPCI announced UPI One World for delegates from more than 40 countries attending the India AI Impact Summit in February 2026. That was a summit pilot, not evidence of permanent general availability. Its announced terms included wallet loading limits of INR 25,000 per transaction, no more than two loadings per month and INR 50,000 total per month; unused balance could be transferred to the original payment source subject to foreign-exchange regulations. These limits apply to that specific pilot, not to outbound international UPI payments. See NPCI’s February 2026 announcement for the pilot details.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minuteBest Value
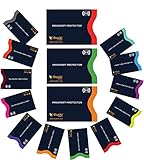
- RFID sleeve with electronic armor is the identity theft protection for your bank cards. This credit card and ID holder prevents electronic access to your cards, valuable credit card protection, an ID card protector and a passport protector RFID to block scanning and skimming
- Made from special RFID blocking material: This credit card holder and RFID blocking passport holder is thin and lightweight, certified secure sleeves for credit cards protect against scanning of digital and electronic chips by thieves, tear and water resistant
- RFID sleeve with electronic armor is the identity theft protection for your bank cards. This credit card and ID holder prevents electronic access to your cards, valuable credit card protection, an ID card protector and a passport protector RFID to block scanning and skimming
- Credit card protection sleeve designed with color coding system to find each card easily and quickly. RFID credit card holder and passport holder RFID have different colors for superior convenience; the special high quality rigid aluminum foil coating of these tiny slim RFID blocking wallets ensures you will never be a victim of high tech crime
- Includes 12 RFID credit card protector sleeves and 3 RFID sleeves as a passport protector. Protect your drivers license, subway or green card, hotel keys and all family travel documents. You don’t need to carry an RFID blocking wallet with you, just several of these lightweight credit card protective sleeves and RFID passport protectors.
What published country and transaction figures mean
International acceptance is expanding through individual market arrangements, but dated milestones should not be mistaken for a current availability list. NIPL reported that UPI merchant acceptance with Fonepay launched in Nepal in March 2024 and that cross-border person-to-merchant UPI transactions there passed 100,000 by August 2024. That figure is a historical milestone, not a current transaction count or a claim that all Nepalese merchants accept UPI. The NIPL Nepal announcement gives the dated context.
NPCI also reported 21.70 billion UPI transactions worth INR 28.33 lakh crore in January 2026. That figure describes overall UPI activity and should not be read as an international-payment total. The same February 2026 NPCI announcement placed the UPI One World summit pilot’s reach at over 40 countries, which likewise describes eligible delegates for that pilot rather than standing international merchant coverage.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




