Free tools Windows power users keep installed
One-click scans. No signup required.
For an individual in India, bank fixed-deposit (FD) interest is included in taxable income; there is no single final tax rate that applies to every depositor. Estimate its tax cost by calculating tax on your total taxable income with the FD interest and again without it. The difference is the estimated tax attributable to the interest. Treat any tax deducted at source (TDS) as a credit against that liability—not as the final tax on your FD.
How FD interest affects your income tax
FD interest is taxable as part of the depositor’s income. Its final tax effect depends on the person’s total income, the tax regime that applies or is chosen, and any deductions, rebates, surcharge, cess or other rules relevant to that tax year. As a result, the advertised FD rate is a gross rate: it does not tell you how much interest you will retain after tax.
As an Amazon Associate I earn from qualifying purchases.
A practical estimate isolates the FD interest by comparing two tax calculations under the same tax regime and for the same tax year:
- Calculate tax on your other taxable income plus the FD interest attributable to that year.
- Calculate tax on the same other taxable income without that FD interest.
- Subtract the second amount from the first. That difference is the estimated incremental tax caused by the interest.
This is more useful than multiplying FD interest by a flat percentage, because it reflects where the interest falls in your overall tax calculation. It remains an estimate: a full return calculation may be affected by other income, deductions, rebate eligibility, surcharge, cess and the taxpayer’s circumstances.
#1 Best Overall
- Offline app - you have full freedom to use the app without Wi-Fi.
- Beautiful eye-catching design.
- App uses little phone space and works fine with low memory.
- Low battery consumption - the app is optimized to use the battery wisely.
Estimate the post-tax interest step by step
Use figures for one tax year at a time. First identify the interest attributable to that year; then compare the two tax outcomes. Do not subtract TDS from the interest as though it were a second tax charge.
- Choose the tax year. Confirm which income period you are estimating. Keep the old assessment-year terminology separate from the Tax Year framework that starts on 1 April 2026.
- Find the year’s FD interest. Use the bank’s interest or account statement and the deposit’s payout or compounding terms. For multiple FDs, add the interest attributable to the relevant year across them.
- Assemble other taxable income. Use the same income and assumptions in both calculations. Consider the regime that applies or is selected for you, along with deductions and rebates you are actually eligible to use.
- Calculate tax with the interest. Work out tax on other taxable income plus the FD interest under that same regime and year.
- Calculate tax without the interest. Repeat the calculation with the FD interest removed, keeping the regime and all other assumptions unchanged.
- Find the incremental tax and retained interest. Subtract the no-interest tax from the with-interest tax. Subtract that incremental tax from the year’s FD interest to estimate post-tax interest.
- Calculate an estimated after-tax yield. Divide the estimated post-tax interest by the invested principal for the same period. If comparing deposits with different terms or payout patterns, compare equivalent periods and account for when interest is available.
- Reconcile TDS separately. Compare the estimated or final tax payable with tax already withheld and any advance tax paid. TDS is a credit in the tax reconciliation; it is not an additional tax cost to subtract from post-tax interest.
In compact form, let I be the FD interest attributable to the year, O be other taxable income, and T(x) be the tax calculation under the applicable regime and year. Then:
Estimated incremental tax = T(O + I) − T(O)
Estimated post-tax interest = I − [T(O + I) − T(O)]
Estimated after-tax yield for the period = estimated post-tax interest ÷ principal
For example, if you have the bank’s annual interest figure and the two tax calculations, the method does not require assuming a universal FD tax rate. It shows how much the interest changes your tax bill under your own income and regime assumptions. Use an official calculator or a qualified tax professional if your income, deductions or regime eligibility makes the comparison difficult; do not substitute a TDS percentage for the full calculation.
How to read the two tax calculations
Keep the comparison like-for-like. If you change the tax regime, deduction assumptions or other income between the with-interest and without-interest calculations, the difference will no longer isolate the FD’s effect. First calculate both outcomes under one eligible regime and one set of assumptions. If you are deciding between regimes, then run that same pair of calculations separately under each regime and compare each regime’s total tax outcome.
The difference is an estimate of the tax added by the interest, not necessarily the amount the bank withheld and not necessarily a separate tax line on your return. It can be smaller or larger than a simple percentage of the interest because your total-income calculation and applicable rules determine the outcome. A person’s deductions and rebate eligibility can also affect the two calculations, which is why the exact result cannot be inferred from the FD rate alone.
Rank #2
- General Features
- Feature to Animate results
- Works both Online & Offline(no need of internet connection)
- Easy to use interface with all data in single page
- Get result with one button click
Identify when FD interest belongs in the calculation
The deposit’s payout terms affect cash flow and the amount of interest shown by the bank during a year. A deposit may pay interest periodically or compound it for payment later. For an annual estimate, check the bank’s year-wise interest or accrual statement rather than using only the maturity amount.
Do not assume that all interest on a multi-year FD is necessarily taxable only in the year it matures. The official guidance establishing the TDS timing under section 194A refers to deduction at the earlier of payment or credit, including credit to an account by whatever name called. That describes withholding timing under the earlier Act; it does not by itself settle every depositor’s income-recognition method for every FD product. The appropriate reporting can depend on the deposit, taxpayer’s method and circumstances. If the bank statement and the tax reporting period seem inconsistent, get advice specific to your situation.
| FD feature | What to check for an annual estimate | Why it matters |
|---|---|---|
| Periodic payout | Interest credited or paid during the year, as shown in bank records | It affects the year’s cash receipts and may be relevant to the bank’s TDS timing. |
| Compounding or cumulative payout | Year-wise interest/accrual information, not just the final maturity value | A maturity-only figure does not show how the bank has recorded interest over each tax year. |
| Several deposits or accounts | Interest records for each deposit and the payer’s aggregate figures | A single FD’s interest may not reflect the total interest relevant to a tax calculation or withholding threshold. |
Before making the estimate, gather the relevant bank statements or interest certificates, note the FD’s principal and term, and identify whether interest is paid out or accumulated. If you hold several deposits, keep a year-wise total rather than relying on a single deposit’s maturity quote. The bank’s records help establish the interest figures and withholding shown by the payer; your tax calculation still has to account for your own income and applicable rules.
Tax deducted at source is not the final FD tax
A bank may withhold tax on deposit interest when the applicable conditions and annual threshold are met. The withholding amount is credited toward the taxpayer’s tax position; it does not determine the depositor’s final liability. If the final tax calculation exceeds TDS and other credits, a balance may remain payable. If credits exceed the final liability, the taxpayer reconciles the difference through the return and applicable refund process.
Recommended Free Tools
| Question | TDS | Final tax on the interest |
|---|---|---|
| What is it? | Tax withheld by the payer under applicable rules. | The depositor’s tax outcome after considering total income and applicable rules. |
| What determines it? | The relevant law, payer and depositor category, and applicable threshold and timing. | The taxpayer’s total income, regime, eligible deductions and rebates, and other relevant rules. |
| How does it affect payment? | It is a tax credit to account for in the reconciliation. | It determines whether a further balance is payable or a refund may be due, subject to normal rules. |
Do not rely on a single TDS threshold quoted without its tax year and category. Official section 194A materials distinguish among categories, including a higher threshold for resident senior citizens. The applicable threshold is not a universal allowance for each individual FD: the payer/category and aggregate interest matter. The sources reviewed do not establish a single current threshold applicable to every depositor, so check the official rule for your year and circumstances before acting.
The Income Tax Department’s filing guidance also treats deposit interest as income that can increase tax liability. Its ITR-1 and ITR-4 FAQs discuss filing and the possibility of self-assessment tax where tax remains after TDS and advance-tax credits. Whether a particular person can use a particular return form depends on that person’s circumstances; do not infer eligibility merely from having bank interest.
In practical terms, separate two questions: how much tax does your total-income calculation produce, and how much of that amount has already been paid through TDS or advance tax? If the credits do not cover the amount due, additional payment may be needed. If they exceed the final liability, the difference is handled through normal return and refund procedures. Neither result is determined simply by whether the bank deducted TDS from one FD.
Rank #3

- Fixed Deposit Calculator
- v 1.0
- -- Calculate the maturity value of your Fixed Deposit
Keep the tax-year rules and section numbers straight
India’s Income Tax Department says the Tax Year concept applies from 1 April 2026 to income earned from that date under the Income-tax Act, 2025. The new Act uses section 393 for TDS in the framework described by the Department. Earlier material may instead refer to the Income-tax Act, 1961, section 194A and assessment years. Those labels belong to different periods; do not combine a rate, threshold or section reference from one framework with a period governed by the other.
Quick wins for a faster PC:
Clear out junk files and repair common Windows errorsFree Scan →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →| Reference | Period or use | How to read it |
|---|---|---|
| Section 194A and assessment-year terminology | Earlier Act materials | Use for the period and rules those materials cover; the Department’s tutorial describes deduction at the earlier of interest payment or credit. |
| Section 393 and Tax Year terminology | Income under the Income-tax Act, 2025 from 1 April 2026 | Use the applicable new-Act provisions and current-year official guidance rather than carrying forward an older section number or threshold. |
The transition also matters when looking at slab tables. The Department’s individual guidance for Assessment Year (AY) 2026–27 lists the following new-regime slabs. These figures are specific to that assessment year and are not a confirmed slab schedule for Tax Year 2026–27.
| AY 2026–27 new-regime taxable income band | Rate listed by the Income Tax Department |
|---|---|
| Up to ₹4 lakh | Nil |
| Above ₹4 lakh to ₹8 lakh | 5% |
| Above ₹8 lakh to ₹12 lakh | 10% |
| Above ₹12 lakh to ₹16 lakh | 15% |
| Above ₹16 lakh to ₹20 lakh | 20% |
| Above ₹20 lakh to ₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
The Department describes the new regime as the default for covered individuals and says eligible taxpayers can choose the old regime under specified rules. Regime eligibility and the value of deductions or rebates can change which total-income calculation is better for an individual. These AY 2026–27 slabs should not be used as a substitute for verifying the official rates and rules that apply to income in Tax Year 2026–27. The sources reviewed do not establish that year’s individual slab schedule, so no current-year rate should be inferred from the table above.
When looking up a rate or threshold, match the official guidance to the income period and taxpayer category before using it. A page that uses assessment-year language may be describing income from an earlier period, while Tax Year terminology applies to income from 1 April 2026 onwards under the new Act. For TDS, also confirm the relevant payer and depositor category. Avoid carrying a figure forward just because it appeared in an older bank notice or tax explainer.
Compare gross and post-tax returns fairly
If you are comparing two FDs or tax regimes, compare the tax outcomes on the same basis. A higher headline FD rate does not necessarily produce a higher amount retained after tax, and a tax-regime comparison cannot be made from the FD interest alone if the regimes treat the taxpayer’s other income, deductions and rebates differently.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware match- Use the same tax year and income assumptions. Compare total tax under each eligible regime, including only deductions and rebates the depositor can actually claim.
- Use year-wise interest, not just maturity value. Match the interest attributable to each tax year to the bank’s payout or compounding records.
- Compare equivalent periods. Put gross FD interest, estimated incremental tax and after-tax yield on the same time basis and principal amount.
- Separate tax from withholding. Compare estimated final liability with TDS already deducted; do not treat the deduction as the final tax rate.
- Include non-tax terms when choosing a deposit. Term, access to funds, premature-withdrawal conditions and deposit risk can matter to a product choice, but they are separate from estimating the tax on interest.
For a regime comparison, first calculate the total tax outcome under each regime using the income and deductions that actually apply to you. Then calculate the with-interest and without-interest figures within each regime. This lets you see both the regime’s overall tax result and the estimated contribution from FD interest, without confusing one with the other. A regime that appears better before accounting for eligible deductions or rebates may not produce the same result once those items are included.
Common estimation mistakes to avoid
- Applying a flat TDS rate to all interest. Withholding is not a personalized calculation of final tax. Use the difference between the two total-income tax calculations.
- Assuming every depositor owes the same percentage. Total income and the applicable regime influence the incremental tax impact.
- Using only the maturity statement. A multi-year maturity amount does not by itself tell you the interest attributable to each tax year.
- Treating a threshold as per-FD. Confirm the payer/category and aggregate-interest rule for the relevant period.
- Mixing AY 2026–27 figures with Tax Year 2026–27. The AY table above is not a verified Tax Year 2026–27 schedule.
- Counting TDS twice. It reduces the amount left to settle after credits; it is not an extra expense on top of the tax liability.
- Assuming a refund is automatic. A difference between withholding and final tax must be reconciled under the normal filing and refund rules.
Frequently asked questions
Is FD interest taxed according to my income-tax slab?
The final tax effect depends on your total taxable income and the tax regime that applies or is selected for the relevant year, along with eligible deductions, rebates, surcharge, cess and other rules. To estimate the effect of FD interest, compare tax on your other taxable income plus that interest with tax on the same income without it. Do not assume that the bank’s TDS percentage is your final rate.
Rank #4

- PROTECTIVE HINGED COVER: Features a hinged, hard cover that protects the keys and display when stored, making this handheld calculator durable and easy to carry safely.
- DUAL-POWER SOURCE: Runs on solar energy with a battery backup, ensuring consistent and reliable use in any lighting condition or environment.
- LCD SCREEN SIZE: The 2-inch screen size, 8-digit LCD screen clearly shows each digit, helping to prevent reading errors and making numbers easy to read at a glance.
- CONVENIENT FUNCTION KEYS: Includes a 3-key independent memory, square root key, change sign key, automatic power down, and more to provide efficient, reliable everyday math.
- TRUSTED BY WORKPLACES FOR DECADES: Sharp has been a dependable name in office calculation for generations — practical tools built around the way people actually work.
Is FD interest taxed before the deposit matures?
Do not assume that all interest on a multi-year FD belongs only to its maturity year. Use the bank’s year-wise interest or accrual records and consider the deposit’s payout and compounding terms. The Income Tax Department’s section 194A tutorial says TDS is deducted at the earlier of interest payment or credit, but that withholding timing alone does not settle every depositor’s recognition method for every FD product.
Does TDS mean my tax on FD interest is settled?
No. TDS is withholding and is credited in your tax reconciliation. Your final liability depends on your total-income calculation and applicable rules. You may have further tax to pay if credits are insufficient, or a difference to reconcile through the return and applicable refund process if credits exceed the final liability.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Is the TDS threshold applied separately to each FD?
Do not treat it as a universal per-deposit allowance. The applicable threshold depends on the tax year and relevant payer and depositor category, and aggregate interest can matter. Official section 194A materials include a higher threshold for resident senior citizens, so check the current official rule that matches your circumstances instead of relying on one unqualified figure.
Which tax year should I use for an FD estimate?
Use the income period being estimated and the rules applicable to that period. The Income Tax Department says Tax Year terminology under the Income-tax Act, 2025 applies from 1 April 2026 for income earned from then onward. Earlier material may use section 194A and assessment-year terminology. Keep those frameworks and their figures separate.
Can I use the AY 2026–27 slab table for Tax Year 2026–27?
No. The listed slab table is specific to AY 2026–27. It is not a confirmed slab schedule for Tax Year 2026–27, so check the official tax tables for the relevant period rather than extrapolating from the AY table.
What records do I need to estimate post-tax FD returns?
Collect the bank’s interest or account statements, the deposit’s principal and payout or compounding terms, and the year-wise interest figure. You will also need your other taxable income and the deductions or rebates you are eligible to use to compare tax with and without the FD interest. For several deposits, include the relevant year’s interest across them.
Sources and scope
This explanation is scoped to an individual depositor’s bank FD in India. The relevant official material is from the Income Tax Department: its section 194A and TDS tutorials, the FAQs on the Income-tax Act, 2025 and Tax Year, individual tax-computation and AY 2026–27 guidance, and its ITR-1 and ITR-4 filing FAQs. The timing statement about deduction at payment or credit is specific to the Department’s section 194A tutorial; the new Act’s Tax Year framework begins on 1 April 2026. Rules and rates should be checked against official guidance for the precise income year and taxpayer category.
Best Value
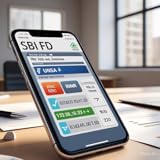
- Dual Currency Support - Input and view results in both USD and INR
- NRI-Friendly - Calculates NRE & FCNR FD returns for USD deposits
- Resident Option - Calculate regular INR fixed deposit returns
- Real-Time Conversion - Automatic USD-INR conversion with customizable exchange rates
- Comprehensive Results - Shows principal, interest earned, and maturity amount in both currencies
Frequently Asked Questions
Is FD interest taxed according to my income-tax slab?
The final tax effect depends on your total taxable income and the tax regime that applies or is selected for the relevant year, plus applicable deductions, rebates, surcharge, cess and other rules. Compare tax with and without the FD interest to estimate its incremental effect; TDS is not your final rate.
Is FD interest taxed before the deposit matures?
Do not assume that all interest on a multi-year FD belongs only to its maturity year. Check year-wise interest or accrual records and the deposit terms. Section 194A TDS timing at payment or credit does not by itself settle every depositor’s income-recognition method.
Does TDS mean my tax on FD interest is settled?
No. TDS is a credit in your tax reconciliation. Your final liability depends on total income and the applicable rules; a balance may remain payable, or an excess credit may be reconciled through the return and applicable refund process.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteIs the TDS threshold applied separately to each FD?
Do not assume a universal per-FD threshold. The applicable limit depends on the tax year and payer and depositor category, and aggregate interest can matter. Check the current official rule for your situation.
Can I use the AY 2026–27 slab table for Tax Year 2026–27?
No. The listed slab figures are specific to AY 2026–27 and are not a confirmed schedule for Tax Year 2026–27. Verify the official rates for the income period you are estimating.
What records do I need to estimate post-tax FD returns?
Use bank interest or account statements, the FD’s principal and payout or compounding terms, and the year-wise interest amount. You also need your other taxable income and eligible deductions or rebates for the two tax calculations.
The Bottom Line
To estimate what you keep from an Indian bank FD, use the year’s interest and compare your tax on total income with and without it under the same applicable regime. Subtract the difference from the interest, then compare TDS separately as a tax credit. Check official rates and withholding rules for the exact tax year and depositor category—AY 2026–27 figures should not be carried forward as Tax Year 2026–27 rules.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




