GHG accounting is the process of measuring and reporting the greenhouse gas emissions associated with an organization’s operations and value chain. A reliable inventory starts with clear boundaries, traceable activity data and suitable emissions factors; it also distinguishes direct emissions from emissions tied to purchased energy and the wider value chain. The accounting method is not the same thing as a disclosure rule or reporting program, and an organization’s legal obligations depend on its jurisdiction and reporting period.
What GHG accounting measures
Greenhouse gas (GHG) accounting turns operational and value-chain activity into an emissions inventory that can be reviewed, reported and tracked over time. The GHG Protocol Corporate Standard is a widely used accounting and reporting reference for corporate-level inventories. It is primarily written for businesses, but can also apply to other organizations with emissions-producing operations.


The standard covers seven gases addressed by the Kyoto Protocol: carbon dioxide, methane, nitrous oxide, hydrofluorocarbons, perfluorocarbons, sulphur hexafluoride and nitrogen trifluoride. Results are commonly expressed in carbon dioxide equivalent (CO2e), using global warming potential values to convert different gases to a common unit. The appropriate conversion and calculation approach depends on the source and the applicable accounting or disclosure requirements.
The Corporate Standard is program- and policy-neutral: it does not require an organization to report to the GHG Protocol’s publishers or prescribe how verification must be conducted. It is also not intended to quantify emissions reductions from mitigation projects for use as offsets or credits. The standard was originally published in 2004; the publisher’s page identifies a 2015 update to its Scope 2 Guidance.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
How the scopes differ
The scopes classify emissions by their relationship to the reporting organization. They help prevent direct operational emissions, purchased-energy emissions and other value-chain emissions from being conflated.
| Scope | What it covers | Examples |
|---|---|---|
| Scope 1 | Direct emissions from sources the organization owns or controls. | Fuel burned in company boilers, furnaces or vehicles. |
| Scope 2 | Indirect emissions associated with purchased or acquired electricity, steam, heat or cooling. | Emissions tied to electricity used at an office or facility. |
| Scope 3 | Other indirect emissions in the organization’s upstream and downstream value chain, outside Scope 2. | Emissions associated with relevant purchased goods, business travel or product transport. |
Scope 3 is organized into 15 categories under the GHG Protocol Corporate Value Chain Standard. Those categories provide a structure for examining value-chain sources; the existence of 15 categories does not mean every organization has emissions in all of them or must report every category as a measured figure.
Accounting method, disclosure regime and reporting program are different
An accounting standard describes how emissions are identified and quantified. A disclosure regime specifies what information an organization must disclose and to whom. A reporting program or initiative is a channel or framework through which an organization may report. One organization may use the GHG Protocol to prepare an inventory, disclose information under IFRS Sustainability Disclosure Standards where applicable, and also participate in a voluntary program. Those are related choices, not interchangeable terms.
What IFRS S2 adds
IFRS S2 addresses climate-related risks and opportunities reasonably expected to affect a company’s prospects and includes disclosures for Scope 1, Scope 2 and Scope 3 emissions. IFRS Foundation educational material published in May 2025 explains that IFRS S2 calls for absolute gross GHG emissions for the reporting period. “Absolute” means a total rather than an intensity ratio; “gross” means before deducting removals or credits.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11The same educational material describes IFRS S2’s use of the 2004 GHG Protocol Corporate Standard for measuring emissions, subject to the standard’s conflict rule and jurisdictional relief. It uses the 2011 Scope 3 standard’s categories to define Scope 3 and identify which categories are included. For Scope 3, an entity must consider all 15 categories and determine which are relevant in its circumstances and to users’ material information needs; it should disclose the categories included. This is not a blanket instruction to report all 15 as measured emissions.
Why requirements change by place and year
In December 2025, the International Sustainability Standards Board (ISSB) issued targeted amendments to IFRS S2. Its announcement describes changes concerning Scope 3 Category 15 financed emissions, classification of financed emissions, jurisdictional relief where only part of an entity must use another measurement method, and global warming potential values. The announcement quotes ISSB Vice-Chair Sue Lloyd saying the priority was “to provide a timely response to challenges.” The technical changes and their applicability should be checked against the relevant effective date and reporting period.
Rank #3

- EFFICIENT ACCOUNTING MADE SIMPLE: Clever Fox Horizontal Accounting Ledger Book is an effective and easy-to-use tool for tracking payments, deposits, and balances in each of your accounts.
- PERFECT FOR SMALL BUSINESS OR PERSONAL USE: This accounting book ledger is perfect for keeping books on your small business or tracking personal finances. With a clear record of transactions, you can easily spot fraudulent charges or other errors.
- TAKE CONTROL OF YOUR FINANCES & SUCCEED: Using this accounting log book, you will have everything you need to analyze your financial operations, assess your income and spending, and prepare accurate financial statements.
- PREMIUM MATERIALS FOR EXTRA DURABILITY: This columnar book has an eco-leather hardcover, thick 120gsm paper, pen loop, elastic band, lay-flat binding, bookmark, and pocket for loose notes. The personal & business ledger measures 10 by 7 inches.
- 60-DAY MONEY-BACK GUARANTEE: We will exchange or refund your business bookkeeping ledger if you aren’t satisfied with your book keeping log for small business for any reason. Reach out to us via message to refund your accounting journal book.
Whether a particular organization is legally required to disclose emissions cannot be determined from a global accounting overview. Check the law, listing or exchange rules, and reporting framework that apply to the organization, including local adoption dates and any jurisdiction-specific relief. A voluntary commitment, an accounting standard and a legal filing requirement may have different scopes and deadlines.
How to build a GHG inventory
The U.S. Environmental Protection Agency (EPA) describes inventory development as a four-step process. The sequence below turns that guidance into practical work for a company team.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minute- Set the purpose and boundaries. Identify the reporting purpose and accounting standard, then determine which entities, facilities and emissions sources belong in the inventory. Choose a base year and document the approach for recalculating it if organizational changes or improved data materially affect comparisons.
- Collect activity data and calculate emissions. Assign data owners and gather relevant records, such as utility bills, fuel purchases, process data, fleet records, refrigerant logs, purchasing information, travel data and supplier information. Select emissions factors that match the activity, geography and reporting year. Estimate missing data when necessary and document how estimates were made.
- Establish controls and documentation. Formalize collection procedures in an inventory management plan. Retain source records, factor references and versions, assumptions, exclusions, estimates and calculation files so another reviewer can follow how reported figures were produced.
- Review, report and track progress. Check calculations and data for errors, finalize the inventory and report it through the relevant channel. An organization may seek third-party verification, depending on its needs or requirements, and can use the inventory to track progress against targets over time.
How the calculation works—and why factors matter
A basic calculation combines activity data with an emissions factor: for example, a quantity of fuel multiplied by a factor that estimates emissions per unit of that fuel. Where multiple gases are involved, suitable global warming potentials may be used to convert results to CO2e before aggregation. Actual methods vary by emissions source, data quality, geography and applicable framework, so one factor or formula should not be applied indiscriminately to every activity.
Rank #4
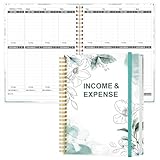
- EASY TO MANAGE - Use this income & expense log book to record your income and expenses each day.Keep your budget in balance, and develop good bookkeeping habits to meet your financial goals
- ACCOUNTING FOR THE WHOLE YEAR - This income and expense tracker is undated and is used to lasts a whole year.The keeping log has 1 page Year Overview, 53 weekly spreads, 2 pages annual summary, 10 notes pages, to track weekly and yearly income & expenses
- HIGH QUALITY - The accounting bookkeeping tracking ledger log book is used to high quality 100gsm pure white paper, teal elastic band and a back pocket for extra space. Make sure you have enough space for all financial activities
- UNIQUE DESIGN & A4 SIZE - Income and expense log book is spiral bound design, size of 8" x 10.5". Just the perfectly size to fit in your backpack, purse or laptop case. Without taking up your space and always helping you keep track of your small business
- THE PERFECT GIFT - Income & expense notebook as gift for woman & man. Use it to track your week-to-week progress, make efficient adjustments whenever needed
For electricity, the factor set and method need to match the applicable accounting approach and location. Where the framework permits, supplier-specific information and grid-average factors may be relevant alternatives. Record the factor publication, version, year and geography used; factor datasets are updated, and using a different vintage can change an inventory even when underlying energy use has not changed.
EPA’s Emission Factors Hub is updated periodically. Its January 2025 annual update revised factors for purchased electricity, mobile combustion, transportation, business travel, product transport and employee commuting. A company preparing a U.S. inventory should identify the applicable EPA factor publication and reporting year rather than treating a factor as timeless or universally applicable.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Scope 3 data and supplier outreach
Scope 3 estimates can depend on information from suppliers and other value-chain partners, as well as the company’s own purchasing and activity records. Supplier data may improve estimates, but a request for data is not automatically more useful than a transparent estimate: the method, coverage and limitations still need to be documented.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →EPA’s supplier-engagement guidance recommends choosing suppliers strategically, keeping questionnaires simple, explaining how sensitive information will be used, piloting outreach and considering third-party programs. Prioritize outreach using the organization’s own assessment of materiality, spend, risk and data availability; a spend-based shortcut should not be treated as a universal rule for deciding what matters.
Keeping an inventory traceable and useful
Inventory quality depends on more than arithmetic. A reviewer should be able to connect reported emissions to the underlying source data, understand where estimates were used and reproduce the calculation using the recorded factors and assumptions.
- Keep original bills, logs, invoices and other source records, with clear links to the activities they support.
- Assign a named owner and collection timetable to each material data stream.
- Reconcile facility and finance totals where it makes sense, and investigate material differences.
- Mark estimates, exclusions and assumptions explicitly rather than allowing them to appear as measured data.
- Record factor source, publication date or version, geography, units and any conversions.
- Use a documented review process and retain calculation files so results can be recreated and compared across reporting periods.
Tools for an organization starting out
EPA offers a free Simplified GHG Emissions Calculator that estimates annual Scope 1, Scope 2 and Scope 3 emissions from activity data. EPA describes it as primarily intended for small- to medium-sized organizations that are early in GHG management. Its Excel edition has version requirements and uses macros for navigation.
A calculator can help organize an initial estimate, but it does not determine which reporting rules apply, ensure the factor vintage is appropriate, create complete source records or satisfy assurance requirements by itself. Before relying on a tool, assess whether it supports the organization’s relevant emissions sources, jurisdiction and sector; provides factor transparency and an update cadence; offers an adequate audit trail and permissions; and can produce the reporting outputs and supplier workflows the organization needs. Paid inventory software or specialist support may offer capabilities beyond a spreadsheet, but the sources cited here do not establish a particular commercial provider as best.
Recommended Free Tools
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




