Forbes Advisor’s five 2026 homeowners insurance picks are Chubb, Westfield, Erie, USAA and Farmers. Forbes names Chubb best for liability coverage, Westfield best for price, Erie best for add-on coverage, USAA best for military members and veterans, and Farmers best for discounts. Its modeled annual premiums for a home with $350,000 of dwelling coverage range from $1,644 to $2,524, although Forbes displays two different USAA figures: $1,644 on the company card and $1,664 in its comparison table.
These are use-case recommendations, not a universal ranking. A company may be unavailable in your state, restrict eligibility, decline your property because of its age or risk, or quote a very different price in your ZIP code. The practical winner is the insurer that offers the coverage your home needs, at a sustainable price, from a financially sound underwriting company with acceptable claims terms. Use Forbes’ list as a shortlist, then compare identical quotes.
As an Amazon Associate I earn from qualifying purchases.
Forbes’ best home insurance companies at a glance
Forbes says its 2026 review evaluated 14 insurers using more than 39,000 home-insurance rates, 115,869 consumer sentiments and 182 coverage details. The page was audited and verified on August 7, 2026, and was live as of August 10, 2026. The table below summarizes the five editorial picks shown on the page. Ratings, modeled premiums, complaint levels and coverage counts are Forbes’ figures, not independent determinations that one company is best for every homeowner.
| Forbes pick | Best for | Forbes rating | Modeled annual premium $350,000 dwelling |
Complaint level | Important limitation |
|---|---|---|---|---|---|
| Chubb | Liability coverage | 5.0/5 | $2,288 | Very low | High-value positioning; no guaranteed replacement cost in Forbes’ comparison |
| Westfield | Price | 4.8/5 | $1,794 | Very low | Available in only 10 states according to Forbes and requires an agent for a quote |
| Erie | Add-on coverage | 4.6/5 | $2,273 | Very low | Available in 12 states and Washington, D.C.; generally agent-based |
| USAA | Military members and veterans | 4.4/5 | $1,644 or $1,664* | Very low | Membership eligibility is required |
| Farmers | Discounts | 4.2/5 | $2,524 | Low | Most discounts in the review, but the highest modeled $350,000 premium among the five |
*Forbes’ detailed USAA card says $1,644, while the comparison table says $1,664. Forbes does not explain the $20 difference on the page. The broader rate table later in this article uses $1,664 because that is the figure displayed in the comparison table. See the Forbes review for the source figures.
#1 Best Overall
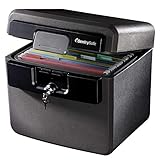
- FIRE AND FLOOD PROTECTION FOR ESSENTIAL PAPERS: UL Classified to withstand high temperatures for up to thirty minutes and ETL Verified to protect contents during water exposure, helping safeguard critical paperwork during common home emergencies
- DESIGNED FOR IMPORTANT DOCUMENT STORAGE: Spacious interior fits hanging file folders and is ideal for organizing passports, birth certificates, insurance records, and legal paperwork
- KEY LOCK SECURITY YOU CONTROL: Durable key lock helps prevent unauthorized access and keeps the lid securely closed during fire events. Two keys are included for backup access
- HOME FRIENDLY SIZE WITH PORTABLE DESIGN: Compact footprint fits easily in closets, offices, or under desks while remaining portable enough to relocate when needed
- BUILT FOR EVERYDAY PEACE OF MIND: Black exterior offers a clean, neutral look that blends into home or office spaces while providing dependable document protection year round
1. Chubb: Forbes’ pick for liability coverage
Chubb is Forbes Advisor’s highest-rated pick, with a 5.0 out of 5 rating and a modeled annual premium of $2,288 for $350,000 of dwelling coverage. Forbes classifies it as best for liability coverage rather than as the cheapest choice.
The reason is Chubb’s high-net-worth orientation. Forbes highlights the company’s Masterpiece excess-liability capability of up to $100 million. That figure refers to excess or umbrella liability, not the dwelling limit on a standard homeowners policy and not an amount automatically included with every policy. Eligibility, state availability, underlying-liability requirements and the limit actually offered to an applicant still matter. Chubb’s Masterpiece excess-liability materials provide additional context.
Forbes also highlights the possibility of a cash settlement after a covered total loss if the policyholder does not want to rebuild or wants to rebuild elsewhere. That is not a blanket promise: the right to a cash settlement, its calculation and its eligibility conditions depend on the policy form and claim circumstances.
Free tools Windows power users keep installed
One-click scans. No signup required.
- Replacement-cost options: Forbes lists extended replacement cost, but not guaranteed replacement cost.
- Discounts: Forbes counted 16.
- Consumer Sentiment Index: 6.8 out of 10.
- Customer feedback reported by Forbes: strong comments about high-value-home claims service, alongside criticism that premiums can be expensive.
Best fit: A high-net-worth household, owner of a high-value or historic home, or homeowner with substantial assets and an unusually large liability exposure.
What to verify: Ask whether the policy provides the desired limits for jewelry, art, collectibles, wine and other valuables; whether it covers matching or historic restoration materials; what temporary-housing standard applies; whether a cash settlement is available for your property; and whether the umbrella follows exclusions in the underlying homeowners policy. Also check the actual underwriting company’s current financial-strength ratings.
2. Westfield: Forbes’ pick for price and value
Westfield has Forbes’ second-highest rating, 4.8 out of 5, and the lowest clearly stated general-market modeled premium among the five at $1,794 per year for $350,000 of dwelling coverage. Forbes says its modeled rates were 34% below average at $350,000 of dwelling coverage, 39% below average at $500,000 and 42% below average at $750,000.
Westfield stands out because Forbes lists both extended replacement cost and guaranteed replacement cost options. Its WesPak products may also include expanded replacement-cost protection, equipment breakdown, service-line, identity-theft, cyber and inland-flood options, subject to the policy, underwriting rules and availability. Westfield describes its package on its WesPak page.
Recommended Free Tools
- Discounts: Forbes counted 10.
- Consumer Sentiment Index: 5.7 out of 10.
- Quoting: Forbes says homeowners cannot complete a quote entirely online and must work through an agent.
- Availability: Forbes says Westfield homeowners coverage is available in only 10 states.
- Customer feedback reported by Forbes: mixed, with particular criticism involving claims response times.
Best fit: A homeowner in Westfield’s service area who wants a low modeled premium and the option to add stronger rebuilding-cost protection.
What to verify: A low national or multistate average does not guarantee a low quote in a wildfire-, hurricane-, hail- or wind-exposed ZIP code. Ask the agent to show the dwelling limit, the exact percentage or formula behind extended replacement cost, any conditions attached to guaranteed replacement cost, roof settlement terms and catastrophe deductibles. Confirm that the quote is for the same endorsements and liability limit as competing quotes.
3. Erie: Forbes’ pick for add-on coverage
Erie receives a 4.6 out of 5 Forbes rating and a modeled annual premium of $2,273 for $350,000 of dwelling coverage. Its main appeal is not discount quantity; it is the breadth of certain optional coverage features.
Forbes lists both extended and guaranteed replacement cost for Erie. It also highlights Erie’s Extended Water coverage, which can address certain flood and other water losses that a standard homeowners policy generally excludes. Extended Water is a specific product or endorsement with its own scope and exclusions. It is not a promise that every kind of flood is covered and is not automatically a replacement for a separate flood policy.
- Discounts: Forbes counted five, fewer than any of the other four picks.
- Consumer Sentiment Index: 7.0 out of 10, the highest CSI score among Forbes’ five picks.
- Availability: Forbes says Erie operates in 12 states and Washington, D.C. Kiplinger identifies those states as Illinois, Indiana, Kentucky, Maryland, New York, North Carolina, Ohio, Pennsylvania, Tennessee, Virginia, West Virginia and Wisconsin.
- Customer feedback reported by Forbes: positive comments about affordability, coverage and claims processing, but some complaints about customer service and dog-breed restrictions.
Erie says guaranteed replacement cost is not available with all policies or in all states. Review the insurer’s home-insurance information and ask the agent to identify the endorsement and its conditions in writing.
Best fit: A homeowner in Erie’s service territory who wants broad replacement-cost options and water-related coverage and is comfortable obtaining a quote through an agent.
Rank #2

- ESSENTIAL Car Auto Insurance Registration BLACK Document Wallet Holders 2 Pieces
What to verify: Determine exactly which water losses are covered, including surface water, sewer backup, sump overflow and groundwater. Ask whether the guaranteed replacement-cost provision requires a particular dwelling-limit calculation, periodic updates, approved contractors or other policy conditions. A low discount count does not matter if the underlying coverage is better suited to your risk.
4. USAA: Forbes’ pick for military members and veterans
USAA is Forbes’ recommendation for military members, veterans and eligible families. Forbes gives it a 4.4 out of 5 rating and the lowest modeled premium in the five-company comparison, but the page contains an unexplained data inconsistency: the detailed USAA company card reports $1,644 annually for $350,000 of dwelling coverage, while the comparison table reports $1,664.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11USAA’s membership is generally limited to eligible active-duty personnel, veterans, National Guard and Reserve members, certain officer candidates and cadets, military spouses and eligible family members. The company’s membership information controls; eligibility for membership does not necessarily mean every insurance product is available for every property or in every situation.
Military-specific features are the differentiator. USAA describes deployment-property coverage for property taken overseas, including replacement-cost protection and no deductible under the product description, subject to its terms. Review the deployment and mobilization coverage page rather than assuming that ordinary homeowners coverage automatically follows every item overseas.
- Replacement-cost options: Forbes lists extended replacement cost but not guaranteed replacement cost.
- Discounts: Forbes counted 11.
- Consumer Sentiment Index: 5.5 out of 10.
- Customer feedback reported by Forbes: positive comments about rates and military-specific coverage, with negative comments involving responsiveness during claims.
Best fit: An eligible military household that values deployment-related benefits and receives a competitive quote.
What to verify: Confirm membership, property-policy eligibility, the actual dwelling-limit calculation, replacement-cost conditions and how overseas property, vacant periods or deployments are handled. Compare the quote and claims process with other eligible insurers rather than assuming military affiliation makes USAA the automatic choice.
5. Farmers: Forbes’ pick for discounts
Farmers earns a 4.2 out of 5 Forbes rating and a modeled annual premium of $2,524 for $350,000 of dwelling coverage. Its selling point is discount breadth: Forbes counted 22 home-insurance discounts, the most among the insurers it assessed.
Farmers lists discounts involving bundling, claim-free history, paperless billing, payment history, connected-home devices, leak detection, fortified construction, protective devices, newer homes, qualifying roofs and certain affiliations. Examples are described on Farmers’ homeowners-discount page. Discounts can vary by state, may require documentation, may not stack freely and may be subject to caps or eligibility restrictions.
- Replacement-cost options: Forbes lists extended replacement cost and, under stated conditions and eligible packages, guaranteed replacement cost.
- Consumer Sentiment Index: 6.4 out of 10.
- Customer feedback reported by Forbes: mixed, with some consumers reporting quick claims handling and others criticizing responsiveness and communication.
Best fit: A homeowner whose actual quote benefits substantially from several qualifying discounts.
What to verify: Request the undiscounted premium, each discount applied and the final premium. A list of 22 possible discounts is not the same as 22 discounts available to you, nor does it prove that Farmers will be cheaper than an insurer with fewer discounts. Compare the final price at the same deductible and coverage limits.
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →How Forbes chose its winners
Forbes’ published 2026 methodology assigns the following weights:
| Factor | Weight | What it represents |
|---|---|---|
| Home-insurance rates | 40% | Modeled premiums at several dwelling-coverage limits |
| Complaints | 25% | Complaint data from state insurance departments, focused on upheld or verified complaints |
| Consumer Sentiment Index | 15% | Feedback about coverage, service, claims, cost, value and satisfaction |
| Extended or guaranteed replacement cost | 10% | Availability of these rebuilding-cost features |
| Discount availability | 10% | Number and availability of discounts counted in the review |
Forbes explains the scoring in its home-insurance rating methodology. Its modeled rate profile assumes:
- Dwelling coverage of $200,000, $350,000, $500,000 or $750,000.
- Personal-property coverage equal to 50% of dwelling coverage.
- Loss-of-use coverage equal to 10% of dwelling coverage.
- A $500 deductible.
- $1,000 of guest medical-payments coverage.
- $100,000 of liability coverage.
- A 40-year-old woman with good credit.
- Rates analyzed in 25 ZIP codes in each state.
- Quadrant Information Services as the rate source.
Forbes says its complaint data covers the preceding four years and comes from state insurance departments. That is different from its Consumer Sentiment Index, which combines feedback from multiple sources and scores several aspects of the customer experience on a 10-point scale. A very low complaint level is not a guarantee of a smooth claim, and a sentiment score is not a claims audit.
Rank #3

- ORGANIZE UP TO 2,000 SHEETS:Store tax records, medical documents, insurance papers, receipts, school assignments, and office files in one place. Expands up to 12 inches and holds up to 2,000 sheets of A4 or letter-size paper.
- STANDS UPRIGHT FOR EASY ACCESS:Unlike traditional accordion folders, the flap can be secured behind the folder using the rear locking hole. Keep documents visible and within reach while sorting, reviewing, or filing paperwork on your desk.
- SORT BY MONTH OR CATEGORY:Includes 12 monthly labels, 24 blank labels, and 12 dividers for flexible organization. Easily manage bills, invoices, projects, household records, school subjects, or client files.
- LARGE TABS & UPGRADED INDEX CARD:Large 4.5 × 1.5 cm tabs provide more writing space for clear labels. The upgraded front index card features larger writing grids, making notes and file references easier to read.
- SOFT-TONE DESIGN & EVERYDAY PROTECTION:Features dividers in Dusty Blue, Blush Pink, Warm Beige, Butter Yellow, Sage Green, and Lavender for easy visual organization. Made from lightweight water-resistant PP material with a flap cover and elastic cord closure to help keep documents protected and organized.
Forbes’ modeled rates versus what you may actually pay
Forbes’ figures are standardized averages, not quotes or price guarantees. Your premium can change by hundreds or thousands of dollars because of location, construction type, roof age, claims history, credit-based insurance score where permitted, deductible, replacement-cost estimate, protective devices and exposure to wildfire, wind, hail, hurricanes or other catastrophes.
Forbes’ broader comparison table reports these modeled average annual premiums:
| Company | $350,000 dwelling | $500,000 dwelling | $750,000 dwelling |
|---|---|---|---|
| Chubb | $2,288 | $3,141 | $4,513 |
| Westfield | $1,794 | $2,154 | $2,787 |
| Erie | $2,273 | $3,047 | $4,244 |
| Farmers | $2,524 | $3,587 | $5,007 |
| USAA | $1,664 | $2,105 | $2,787 |
The same Forbes comparison reports an average across the listed insurers of $2,720 for $350,000 of dwelling coverage, $3,538 for $500,000 and $4,802 for $750,000. Those figures are useful for understanding the modeled comparison, but they should not be treated as national market quotations. Forbes’ quote-comparison guidance explains why actual prices differ.
How to obtain useful comparisons
- Estimate reconstruction cost first. The dwelling limit should reflect the cost to rebuild the structure, not its market value, purchase price or tax assessment. Account for square footage, local labor, materials, architectural features, demolition, debris removal and current building codes.
- Use the same limits on every quote. At a minimum, keep the dwelling, personal property, loss of use, personal liability, guest medical payments, deductible and selected endorsements consistent.
- Disclose the property honestly. Tell the agent about roof age, prior claims, a pool, trampoline, detached structures, home business, short-term rental, vacant periods, unusual construction, expensive animals and planned renovations.
- Ask for the quote in writing. Request the declarations page or quote worksheet showing the underwriting company, forms, endorsements, deductibles, exclusions and every discount applied.
- Get multiple channels. Compare the Forbes picks available in your state with at least one independent agent who can access regional carriers and at least one direct or captive option where appropriate. Three or more genuinely comparable quotes are more useful than many quotes with different coverage.
- Confirm the policy is bound before switching. Do not cancel the current policy until the replacement policy has an effective date and the insurer confirms coverage is bound. Avoid even a one-day lapse.
Which Forbes pick is right for your situation?
If your priority is the lowest modeled price
Start with Westfield if it writes new business in your state and accepts your property. USAA has the lowest modeled figure in Forbes’ table, but only eligible military households can generally use it. Erie may also be competitive in its territory. Farmers’ discount structure could lower its quote for some households, but its $2,524 modeled premium is higher than the other general-market picks at the $350,000 level.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Do not select an insurer from the table alone. A catastrophe-exposed ZIP code, older roof or prior claim can reverse the order completely.
If you need unusually high liability protection
Investigate Chubb first, especially if you have significant assets, a high-profile occupation, multiple properties, high-risk recreational activities or a high-value home. Ask about the Masterpiece excess-liability limit, underlying insurance requirements and exclusions. A $100 million capability does not mean that amount is available to every applicant or in every state.
If rebuilding costs are your biggest concern
Westfield, Erie and Farmers show both extended and guaranteed replacement-cost options in Forbes’ comparison. Chubb and USAA show extended replacement cost but not guaranteed replacement cost in the comparison. The labels are not interchangeable:
- Replacement cost generally pays the cost to repair or replace covered property with materials of similar kind and quality without deducting depreciation, subject to the policy limit and conditions.
- Actual cash value subtracts depreciation. A damaged roof, appliance or older furnishing may be worth substantially less under an actual-cash-value settlement, leaving you to fund more of the replacement.
- Extended replacement cost provides a stated buffer above the dwelling limit, usually subject to a percentage, covered-cause requirements and other conditions.
- Guaranteed replacement cost can pay the full covered rebuilding cost above the stated limit, subject to policy terms, eligibility rules, exclusions and required steps such as maintaining an accurate dwelling limit.
For example, suppose the dwelling limit is $400,000 and a covered regional disaster makes rebuilding cost $470,000. An extended-replacement endorsement might pay only the amount permitted by its stated buffer and conditions. A guaranteed-replacement provision may cover the full covered rebuilding cost above $400,000, but only if the policy’s requirements are met. Neither endorsement automatically pays for every upgrade, code improvement, excluded loss or design change. Westfield’s explanation of actual cash value and replacement cost is a useful starting point.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
If you are eligible for USAA
Check USAA because its military-specific deployment and mobilization features may be more valuable than a generic premium comparison. Then compare the quote against other eligible insurers, paying attention to claims communication, overseas-property terms, replacement-cost conditions and the exact underwriting company.
If you want to maximize discounts
Farmers is the obvious first quote because Forbes counted 22 discounts. But ask how many apply to your home, whether they stack, whether a device or roof certification is required and whether the final price is lower after all coverage differences are normalized. A carrier with five discounts can still be cheaper than one with 22.
If you own valuable possessions
Do not rely on the base personal-property limit alone. Standard policies commonly impose sublimits on categories such as jewelry, artwork, antiques, collectibles and firearms. Ask about scheduled or blanket personal-property coverage, appraisals, valuation methods, mysterious disappearance, pairs and sets, and whether the item is covered away from home. Forbes specifically recommends scheduled personal property for valuable items.
If your home is exposed to wildfire, hurricane, wind, hail or another catastrophe
Availability may matter more than a national ranking. Ask about roof-age restrictions, cosmetic-damage exclusions, wind or named-storm deductibles, wildfire mitigation requirements, vacancy rules and whether the insurer is currently accepting new policies in your ZIP code. If private coverage is unavailable, ask an independent agent about the state’s residual market or FAIR Plan and whether excess coverage is needed.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsRank #4
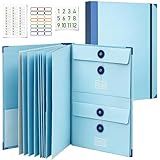
- Keep Important Family Records Together:Keep birth certificates, passports, insurance paperwork, medical records, tax documents, legal papers and other essential family records in one organized place instead of spreading them across drawers, cabinets and separate folders.
- 12 Sections for Different Document Sizes:Three vertical, three horizontal and six half-size sections give different types of paperwork their own space, making this document folder organizer easier to use for full-size papers, passports, certificates, cards and smaller records.
- Fits Standard Letter-Size Papers:Sized for standard 8.5 × 11 in documents, the full-size sections hold important papers while half-size sections provide convenient space for passports, certificates, cards and smaller records.
- Made for Important Life Events:Use this folder for important documents for estate planning, moving, emergency preparedness, insurance matters and other major life events, helping essential family information stay organized and easier to access when needed.
- Practical Home Filing for Everyday Records:Use this family document organizer for household paperwork, personal records, tax-season documents and frequently needed files. A practical home document organizer for keeping important information organized and easier to find throughout the year.
The market is highly location-specific. The Government Accountability Office reported that average U.S. homeowners premiums rose 3% after inflation from 2019 through 2024, while premiums in parts of southern coastal states rose 25% or more. It also found that high wind risk was associated with substantially higher premiums and that disaster risk can reduce availability.
What Forbes’ list leaves out
The list is not the whole market
Forbes says it evaluated 14 insurers, but its article presents five visible editorial picks and says its site does not include all companies or products available. A company not appearing in the five is not necessarily a poor choice. Regional carriers, independent-agent markets and insurers with different underwriting appetites may be more competitive for your property.
Other 2026 comparison publishers reach different conclusions. NerdWallet’s current list includes Chubb, NJM, Andover, Amica, Cincinnati, Country Financial, State Farm and USAA, among others. Amica and Auto-Owners also appear prominently in other comparison and customer-satisfaction research even though they are not among the five visible Forbes picks. The NerdWallet list illustrates how rankings depend on methodology. J.D. Power’s 2025 U.S. Home Insurance Study ranked Amica first, Chubb second and Erie third, demonstrating why a 2025 satisfaction result should not be presented as a 2026 Forbes ranking.
Financial strength is not a published Forbes scoring factor
Forbes’ published weights cover rates, complaints, sentiment, replacement-cost options and discounts. They do not separately list AM Best, S&P or Moody’s financial-strength ratings. That omission does not mean the five insurers are financially weak; it means you should perform the check independently. Confirm the rating for the actual underwriting company named in the policy, not merely the brand on the advertisement.
Coverage breadth is wider than two replacement-cost labels
Replacement-cost availability and discount count do not tell you enough about flood, earthquake, sewer backup, sump overflow, ordinance-or-law, service line, equipment breakdown, cyber, valuables, roof settlement, home business, secondary-home or short-term-rental coverage. Read the forms and endorsements that apply to your home.
Availability can override the ranking
Westfield is limited to 10 states according to Forbes, Erie operates in 12 states plus Washington, D.C., and USAA is membership restricted. Even where a company writes policies, it may not accept a particular roof age, construction type, claim history or catastrophe exposure.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Coverage gaps to check before you buy
| Risk or feature | Question to ask |
|---|---|
| Flood | Is surface-water flooding excluded? Do I need an NFIP or private flood policy? |
| Water backup | Does the policy cover sewer backup and sump overflow, and what is the limit and deductible? |
| Earthquake | Is earthquake damage excluded, and is a separate policy or endorsement available? |
| Wind and hail | Is there a separate wind, named-storm or percentage deductible? Are cosmetic roof damages excluded? |
| Wildfire | Are there vegetation-clearance, roof, defensible-space or high-risk underwriting requirements? |
| Ordinance or law | Will the policy pay the increased cost of bringing an older structure up to current code? |
| Roof | Is the roof settled at replacement cost or actual cash value, and how does age affect payment? |
| Valuables | Should jewelry, art, antiques, collectibles or firearms be scheduled? |
| Service line and equipment | Are underground utility lines, HVAC systems, generators and appliances covered? |
| Liability | Are pools, trampolines, dogs, ATVs and other activities covered, and should I add an umbrella policy? |
| Home business | Does the policy cover business property, visitors and liability, or is a business policy required? |
| Rental use | Is a short-term rental, long-term rental, second home or vacancy covered under this policy? |
Flood is a separate issue
Standard homeowners insurance generally does not cover flood damage. Erie’s Extended Water option may address specified water losses, but it is not universal flood insurance. An NFIP or private flood policy may be necessary. FEMA’s NFIP manual generally limits building coverage for a single-family dwelling to $250,000, so owners of expensive homes may need private or excess flood coverage.
Dog restrictions affect liability
Ask each insurer for its current underwriting rules rather than relying on a generic dog-breed list. Verify breed restrictions, bite-history rules, whether liability is excluded or surcharge-priced, whether rules differ by state and whether an umbrella policy follows the same animal exclusion. Forbes identifies banned dog lists as part of its methodology and notes that they can affect eligibility or liability coverage.
Recommended Free Tools
How to compare home-insurance quotes correctly
Premium is meaningful only when the policies are meaningfully alike. Give every insurer the same information and use this checklist:
- Dwelling limit: Base it on reconstruction cost, not market value. Ask how the insurer calculated it and whether an inflation guard updates the limit.
- Other structures: Confirm the limit for detached garages, sheds, fences, pools and similar property.
- Personal property: Keep the percentage and valuation basis consistent, then separately schedule items that exceed sublimits.
- Loss of use: Compare the dollar limit, time limit and any standards for temporary housing.
- Liability: Quote the same limit on every policy. Consider whether $100,000 is adequate; many households should price higher limits and an umbrella separately.
- Medical payments: Keep guest medical-payments limits consistent.
- Deductibles: Compare both the ordinary dollar deductible and any percentage deductible for wind, hail or named storms.
- Replacement cost: Identify whether the structure and personal property are replacement cost or actual cash value, and whether extended or guaranteed replacement cost is included or optional.
- Endorsements: Add the same water backup, service-line, equipment-breakdown, valuables, ordinance-or-law, cyber and other endorsements to each quote.
- Underwriting details: Disclose roof age, prior losses, construction, occupancy, home business, rental use, pets, pool, trampoline, solar panels and detached structures.
- Financial strength and claims route: Record the actual underwriting company, its current financial-strength rating, agent or direct claims channels and emergency-service availability.
- Discounts: Ask for the final premium and a line-by-line list of discounts. Do not assume discounts are additive.
When two quotes differ, ask the agent to explain the difference in limits, deductibles, exclusions and endorsements before concluding that one insurer is cheaper.
How to file a claim and protect your position
Forbes says claim payments are generally based on the adjuster’s estimate, less the deductible and subject to policy limits. A well-documented loss makes it easier to identify missing items or disputes.
- Make the situation safe and stop further damage. Board up a broken window, shut off water or arrange emergency mitigation when reasonable. Do not put yourself at risk.
- Notify the insurer or agent promptly. Use the available phone, website, chat, email or app channel and record the claim number and contact details.
- Document the event. Write down what happened, when it happened and what was damaged or lost. Photograph and video the damage before cleanup if it is safe.
- Make only emergency repairs at first. Keep receipts. Avoid permanent repairs, demolition or disposal before the insurer has an opportunity to inspect, except where necessary to prevent additional damage or protect health and safety.
- Preserve damaged items where safe. Do not discard them until the adjuster or insurer says they are no longer needed for inspection.
- Prepare a detailed contents list. Include item, age, purchase price if known, replacement cost, photographs, receipts and location.
- Track additional expenses. Keep receipts for emergency repairs, temporary housing, meals or other potentially covered loss-of-use costs.
- Compare the estimate with the policy. Check the adjuster’s scope against the dwelling limit, deductible, replacement-cost conditions, endorsements, depreciation and code-upgrade coverage.
- Escalate methodically. Ask for written explanations of disputed items, request a reinspection or supervisor review when appropriate, and contact your state insurance department if the dispute cannot be resolved.
Before a loss, create a home inventory with photographs, video, receipts or an inventory app. Store a copy somewhere other than the home. This is particularly important for valuables and property that is difficult to identify after a fire or total loss.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Bottom-line buying strategy
Forbes’ 2026 list is a useful starting point, but the five picks answer different questions:
Best Value

- EASY TO READ: The car registration and insurance holder with 4 transparent pockets. Once you facing an emergency, the car registration and insurance holder can quickly show the proof in seconds
- COMPREHENSIVE CAR DOCUMENT HOLDER: Car registration and insurance holder can help to organize the car document easily and quickly. The car document holder not only can keep your registration and insurance card, but also can keep your license, ID cards, AAA cards, business cards, receipt, and others
- MAGNETIC CLOSURE DESIGN: To consider the situation for moisture, wear, tear, and other special situations. The design of magnetic closure is an excellent design to protect your car documents safely and easily
- HIGH-QUALITY MATERIAL: Car registration and insurance holder is made of high-quality PU leather and vinyl PVC. The registration and insurance card holder is durable and convenient with premium material
- CARBON FIBER BLACK FINISH: Features an attractive carbon fiber black exterior design that complements any vehicle interior while providing a professional and sleek appearance for your important documents
- Westfield is the first price/value quote to consider where available.
- Erie is attractive for replacement-cost options and specific water-related add-ons in its territory.
- Chubb deserves attention when liability limits, high-value property or cash-settlement flexibility matter more than a low premium.
- USAA is worth checking first for eligible military households, while remembering that the Forbes page contains a $1,644/$1,664 price discrepancy.
- Farmers is the logical discount-focused quote, but the final premium—not the number of available discounts—is what matters.
Shortlist the companies available for your state and property, then get comparable quotes with the same reconstruction limit, deductible, liability limit and endorsements. Fill coverage gaps for flood, water backup, earthquake, valuables, code upgrades, home business and rental use. Finally, verify the actual underwriting company’s financial strength and do not cancel the existing policy until the replacement policy is bound.
Frequently Asked Questions
Which company does Forbes rank as the best home insurer for 2026?
Forbes does not present one universal winner. It names Chubb best for liability coverage and gives it the highest star rating, 5.0 out of 5. Its other category picks are Westfield for price, Erie for add-on coverage, USAA for military members and veterans, and Farmers for discounts.
Which Forbes pick has the cheapest modeled premium?
USAA has the lowest modeled premium in Forbes’ comparison, but the page contains conflicting figures: $1,644 on the detailed company card and $1,664 in the comparison table for $350,000 of dwelling coverage. Westfield is the lowest-priced generally available pick shown at $1,794, subject to state and property eligibility.
Free tools Windows power users keep installed
One-click scans. No signup required.
Is USAA available to everyone?
No. USAA membership is generally limited to eligible active-duty personnel, veterans, National Guard and Reserve members, certain officer candidates and cadets, military spouses and eligible family members. Confirm eligibility through USAA before treating it as an insurance option.
Is Erie available nationwide?
No. Forbes says Erie operates in 12 states and Washington, D.C. The states identified by Kiplinger are Illinois, Indiana, Kentucky, Maryland, New York, North Carolina, Ohio, Pennsylvania, Tennessee, Virginia, West Virginia and Wisconsin.
Is Westfield available in my state?
Forbes says Westfield homeowners coverage is available in 10 states. Because availability and new-business underwriting can change, check directly with a Westfield agent for your state and ZIP code.
Does homeowners insurance cover floods?
Standard homeowners insurance generally does not cover flood damage. A specific endorsement, such as Erie’s Extended Water coverage, may address defined water losses but is not automatically a substitute for flood insurance. An NFIP or private flood policy may be necessary.
What is the difference between extended and guaranteed replacement cost?
Extended replacement cost provides a stated buffer above the dwelling limit, subject to the endorsement’s percentage and conditions. Guaranteed replacement cost may pay the full covered rebuilding cost above the stated limit, also subject to policy requirements and exclusions. Neither automatically pays for every upgrade or excluded loss.
Should I choose a higher deductible?
A higher deductible can reduce the premium, but choose only an amount you could pay after a serious loss. Compare the premium savings with both the ordinary deductible and any separate percentage deductible for wind, hail or named storms.
How many home-insurance quotes should I get?
Aim for at least three genuinely comparable quotes, including available Forbes picks and at least one regional carrier through an independent agent when possible. Keep the dwelling limit, deductible, liability limits, personal-property coverage and endorsements the same so the prices are meaningful.
Does Forbes consider financial strength?
Financial strength is not listed as a separate factor in Forbes’ published 2026 methodology. Check the current financial-strength rating of the actual underwriting company through an independent rating service and review relevant state insurance information before buying.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchAre Forbes’ home-insurance prices actual quotes?
No. They are modeled average annual premiums based on a standardized profile: a $500 deductible, $100,000 liability coverage, personal property at 50% of dwelling coverage, loss of use at 10%, a 40-year-old woman with good credit and other assumptions. Your location, home, claims, roof, credit-based insurance score where permitted and coverage choices can produce a very different price.
What should I do if no insurer will cover my home?
Ask an independent agent about regional carriers, mitigation requirements, the state’s residual market or FAIR Plan and whether separate wind, flood or excess coverage is needed. Obtain the reason for each declination, address documented safety or roof issues where feasible and avoid letting the current policy lapse while seeking replacement coverage.
The Bottom Line
Forbes’ 2026 picks are best used as a shortlist, not a shopping decision. Compare Westfield for modeled price, Erie for add-ons, Chubb for unusually high liability needs, USAA if you qualify for military membership and Farmers if your home can use several discounts. Then compare the same reconstruction limit, deductible, liability limits and endorsements across multiple insurers, check exclusions and catastrophe deductibles, verify state availability and review the actual underwriting company’s financial strength before binding coverage.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →



