There is no single best place for a festive bonus. Match the money to when you may need it and how much short-term fluctuation or loss you can tolerate: keep near-term needs and emergency cash accessible, and consider market-linked investments only for money you can leave invested through ups and downs. A fixed deposit (FD) offers stated terms, not unlimited protection; mutual funds and gold do not guarantee better returns. No named expert recommendation or consensus is established here, so this guide compares the trade-offs rather than attributing advice to “experts.”
Start with the date you might need the money
Before choosing an investment, separate the bonus into money for known near-term expenses, emergency reserves, and longer-term goals. The first two need access and stability more than a chance of higher returns. A market-linked investment can fall in value when you need to sell it, and no source establishes a safe short-term equity return.

As an Amazon Associate I earn from qualifying purchases.
For longer-term goals, you may be able to accept fluctuations, but only if they fit your finances and temperament. Do not invest the whole bonus in one asset simply because its recent performance looks attractive. Compare likely after-tax outcomes, access rules and costs, not just headline returns.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
How the three choices differ
| Choice | How returns are determined | Main risks and access considerations | What to check |
|---|---|---|---|
| Bank FD | The bank sets the rate and terms for the deposit. | Early withdrawal can reduce interest; deposit insurance has a defined limit. | Current rate for the exact bank and tenure, tax on interest, early-exit terms, and total deposits at that bank. |
| Mutual fund | Depends on the scheme’s assets and performance; mutual funds are not one uniform risk category. | Market value can rise or fall. Exit loads and expenses may affect what you receive. | Scheme objective and asset mix, risk disclosures, holding period, exit load, expenses and tax classification. |
| Gold | Depends on gold prices and the route used to hold it; price movement does not guarantee a return. | Physical gold brings storage and purity considerations; financial products have their own costs and liquidity considerations. | Physical gold or ETF units, purchase and sale costs, liquidity, storage and purity if physical, and applicable tax. |
When an FD may fit
An FD may suit money for a known date when you value a stated rate and deposit terms over market-linked growth. Compare rates for the actual tenure and read the premature-withdrawal conditions: RBI directions allow banks to set and disclose penalties, and an FD closed early may earn the rate applicable to its actual holding period rather than the original contracted rate. RBI deposit directions.
#1 Best Overall

- ✔️Each coin contains 1/10 oz of gold.
- ✔️Obverse: Lady Liberty holding a torch with an olive branch.
- ✔️Reverse: The Type 1 reverse, used from 1986-2021, shows a male bald eagle in flight carrying an olive branch to his nest, where a female awaits with her young. The Type 2 reverse, introduced in 2021, shows a bold close-up portrait of an eagle.
- ✔️Each Gold Eagle is a sovereign monetized bullion coin fully guaranteed by the U.S. Mint.
DICGC deposit insurance is limited to ₹5 lakh per depositor per bank for deposits held in the same capacity and same right. It is not blanket protection for every amount or financial product. Consider all your deposits at that bank when checking the limit. RBI Annual Report 2024–25.
FD interest is taxable under the applicable rules, so compare what remains after tax rather than the quoted rate alone. The exact outcome depends on your income and tax circumstances.
Rank #2

- 99.99% Fine Gold; 24K
- Metal Content: 1 Troy Ounce
- Stock Photo; Image is indicative of quality
- Edge: Reeded ; Diameter: 32.70 mm; Thickness 2.95 mm
- You will receive a coin with a year date of our choice from 2006 – Present. Please kindly note that we are unable to accommodate specific year requests
Mutual funds: identify the scheme before judging risk
“Mutual fund” describes a broad category, not a return promise. Equity-oriented schemes invest in shares and can fluctuate substantially; debt-oriented schemes hold debt and money-market instruments and have different risks. A debt fund is not the same as a bank deposit. Review the scheme’s objective, holdings, risk disclosures, expenses and exit load before investing. AMFI’s scheme categorization guide explains the categories.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →A lump-sum investment may be exposed to market declines soon after purchase. Whether a scheme suits the bonus depends on your time horizon and ability to withstand losses, not on a claim that mutual funds generally earn more.
Rank #3

- ✔️Each coin contains 1/10 oz of gold.
- ✔️Obverse: Lady Liberty holding a torch with an olive branch.
- ✔️Reverse: Portrait with an American bald eagle, a design by Jennie Norris in 2021.
- ✔️Each Gold Eagle is a sovereign monetized bullion coin fully guaranteed by the U.S. Mint.
Gold: physical metal and ETF units are different routes
Physical gold means owning the metal; a Gold ETF provides electronic exposure to gold through units. AMFI explains that Gold ETF prices move with gold prices and that electronic holding avoids the physical theft and purity risks associated with holding gold directly. That does not establish that an ETF, or gold itself, will deliver a higher return. AMFI’s Gold ETF explanation.
With physical gold, account for purchase and sale costs, storage and purity. With ETF units, check the product’s costs, trading liquidity and the process for buying and selling. Either route can lose value if gold prices move against you.
Rank #4
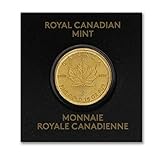
- Purity: .9999 Fine Gold (24-Karat)
- Diameter: 8 mm (0.314961 inches)
- Metal Content: 0.0322 Troy Ounces
- Stock Photo; Image is indicative of quality
- You will receive one coin per purchase in a divisible blister card with a unique serial number shown on the back of the assay card. The yer-date of the coin will be random.
Check tax and net returns for your exact investment
Tax treatment depends on the instrument, its classification, acquisition date, holding period and your applicable tax regime. Mutual-fund tax treatment is not identical across all schemes, and the rules can change. AMFI describes the specified-mutual-fund definition applicable from FY 2025–26 as including funds investing more than 65% of proceeds in debt and money-market instruments, and qualifying funds investing 65% or more in units of those funds. That classification is only one part of determining the tax result for a particular investment. Check the applicable rules for your transaction and tax year using the AMFI tax guidance and the Income Tax Department’s capital-gains guidance.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchPC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11For context, the Income Tax Department’s AY 2026–27 FAQ lists new-regime slabs of nil up to ₹4 lakh; 5% from ₹4 lakh to ₹8 lakh; 10% from ₹8 lakh to ₹12 lakh; 15% from ₹12 lakh to ₹16 lakh; 20% from ₹16 lakh to ₹20 lakh; 25% from ₹20 lakh to ₹24 lakh; and 30% above ₹24 lakh. It also lists a section 87A rebate of up to ₹60,000 for eligible total income up to ₹12 lakh. These are general figures, not a calculation of your liability; applicability depends on your circumstances and income composition. Check the Income Tax Department FAQ for the relevant year.
Best Value
A practical way to decide
- Set aside what must stay available. Reserve money for upcoming expenses and emergency needs before considering investments exposed to market or sale-price changes.
- Choose a realistic holding period. Use the date you may need the money, not an optimistic forecast, to rule out options that could force a poorly timed sale or early withdrawal.
- Compare like with like. For an FD, compare the exact bank, tenure, early-exit terms and post-tax interest. For a mutual fund, compare scheme category, risk, costs and exit load. For gold, compare physical ownership with ETF units and include route-specific costs.
- Check the downside you can accept. If a temporary decline would make you sell, a market-linked option may not fit that portion of the bonus.
- Verify current product and tax terms. Rates, scheme documents and tax rules can change. Read current bank terms, the relevant mutual-fund documents and official tax guidance before committing.
If you need a tailored allocation across several goals, consult a qualified, appropriately registered adviser who can consider your full financial situation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




