The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Sometimes. You may have to file a nonresident state income tax return if you earned income sourced to a state where you do not live and that state’s filing rules require a return. There is no single nationwide threshold: the answer depends on the state, tax year, income type and amount, where you worked, reciprocity rules, and whether you need to claim a refund. Your home state may also require a return.
How to tell whether you need a nonresident return
Work through the rules for each state connected to your income. A state’s right to tax some income does not automatically mean every person with that income must file; its filing threshold, exceptions, and refund rules matter too.

- List the states tied to your income. For wages, identify where you physically performed the work and whether you worked in more than one state. Do not assume your employer’s location alone determines where wages are sourced.
- Identify the income connected to each state. State-source income can include wages, rent or gains from property located there, business or professional income, and some pass-through income. The categories and treatment depend on state law.
- Check that state’s filing test for the tax year. The trigger may depend on a federal filing obligation, state-source taxable income above an allowance, or a state-specific rule. Use the instructions for the return year in question.
- Check reciprocity and exceptions. A reciprocal agreement may change how a state taxes certain wages, but it generally applies only to particular state pairs and income types.
- Consider whether you need to file for a refund. If a state withheld tax that you believe was not owed, a return may be necessary to request the money back.
- Review your resident-state filing separately. Your home state may tax income earned elsewhere and may allow a credit for qualifying tax paid to another state. The credit’s limits and exclusions are state-specific.
What counts as income sourced to another state?
Wages and work location
For wage income, the place where you performed services can matter. If you worked in more than one state, the relevant state may require you to allocate wages using its own method. New York’s 2025 nonresident instructions, for example, direct certain nonresidents with wages earned both inside and outside New York to complete a separate Schedule A for each job to allocate those wages.
That example is not a universal allocation formula. Follow the source state’s instructions for the relevant year, especially if you worked across state lines or worked remotely.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall
Property, business, and other income
Wages are not the only possible connection. Income from real or tangible property in a state, rental activity, business or professional services, and certain pass-through entities may also be treated as state-source income. New York and Georgia list several of these categories in their nonresident guidance. A wage reciprocity agreement does not necessarily exempt these other types of income.
How filing rules differ: official state examples
These examples show why you must check the specific state’s current instructions rather than apply one national income threshold. They are not an exhaustive state-by-state guide.
Rank #2
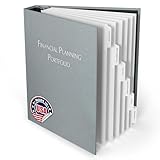
- EVERY FINANCIAL DOCUMENT IN ONE PLACE — This financial records organizer includes six pre-labeled tab dividers — Investments, Bank Statements, Insurance, Legal Documents, Taxes, and Retirement — so every important paper has a clear home. No more hunting through file boxes, drawers, and shoeboxes when you need a tax return or insurance policy.
- PEACE OF MIND FOR YOU, CLARITY FOR THE PEOPLE YOU LOVE — Whether it is a CPA appointment, a tax filing, a retirement decision, or a family member stepping in to help, every account number, policy, and statement is in one clearly-labeled financial binder — accessible in minutes, not hours. Designed to hold the financial records you actually need at hand — current policies, recent tax returns, key statements, beneficiary forms — not a replacement for your full file cabinet.
- PREMIUM LINEN CONSTRUCTION, MADE IN THE USA — Refined linen cover with silver foil detailing, rigid hardcover, and a 1.5-inch D-Ring that holds up to 350 sheets of standard 8.5 x 11 paper. Includes a heavyweight water-resistant document pocket, media sleeve for USB drive backups, and a business card holder for your CPA or financial advisor.
- A THOUGHTFUL GIFT WITH LASTING PURPOSE — Getting financial records organized is something most people mean to do one day. This portfolio makes starting easier — an ideal gift for aging parents, newly retired couples, adult children managing household finances, or anyone preparing for tax season, a financial advisor meeting, or retirement.
- FOR THE WAY HOUSEHOLDS ACTUALLY ORGANIZE — Built for the household record-keeper getting financial papers in one place, the adult child helping aging parents centralize accounts and policies, and anyone preparing a spouse, executor, or financial advisor with everything they would need to step in and find what matters.
| State | What the state guidance says | Important qualification |
|---|---|---|
| Georgia | Nonresidents who work in Georgia or receive Georgia-source income and are required to file a federal return generally must file a Georgia return. | The Georgia Department of Revenue describes an employee-services exception when Georgia work compensation is no more than the lesser of 5% of income from all places or $5,000, provided the activity is only performing employee services. Check the applicable tax-year guidance before relying on it. |
| Illinois | A full-year nonresident generally files Form IL-1040 with Schedule NR if Illinois-source taxable income exceeds the Schedule NR exemption allowance, or to claim a refund of Illinois tax withheld in error. | The allowance amount is not stated here; consult the Illinois Department of Revenue’s Schedule NR instructions for the return year. Reciprocity covers qualifying employee compensation for residents of Iowa, Kentucky, Michigan, and Wisconsin, not other income such as lottery winnings. |
| New York | New York-source income may include services performed in the state, income from in-state real or tangible property, business or professional activity, and specified pass-through income. | For certain wages earned both inside and outside New York, the 2025 instructions require a separate Schedule A for each job to allocate wages. |
| Arizona | Nonresidents working in Arizona must report Arizona-source income when it exceeds the filing requirements in the applicable instructions. | The Arizona Department of Revenue says a filer below the filing requirement may still need to file to recover withholding. Arizona also describes credits that may reduce overlapping tax. |
| Indiana | Residents of Kentucky, Michigan, Ohio, Pennsylvania, or Wisconsin with Indiana wages may use Indiana’s reciprocal nonresident form. | Other Indiana income, including farm, rental, or sole-proprietor income, may call for a different nonresident return. |
| North Dakota | The general test described by the North Dakota Office of State Tax Commissioner is a federal filing requirement plus North Dakota-source income. | The state also describes reciprocity for Minnesota and Montana wages and filing to recover North Dakota withholding. |
| Michigan | A resident of one of Michigan’s reciprocal states generally does not owe Michigan tax on Michigan wages alone. | Filing may still be needed to claim a refund of withholding. Michigan residents may be taxed on income regardless of where earned, subject to state rules for credits and exclusions. |
What reciprocity does—and does not—change
Reciprocity is an agreement between particular states that can exempt qualifying residents from tax on certain wages earned in the other state. It does not create a general exemption from every nonresident filing obligation. Before relying on it, confirm that your home state and work state have an agreement, that your income qualifies, and whether the agreement changes withholding, filing, or both.
For example, Illinois identifies reciprocal wage treatment for residents of Iowa, Kentucky, Michigan, and Wisconsin, while Indiana identifies a reciprocal form for qualifying wage earners who live in Kentucky, Michigan, Ohio, Pennsylvania, or Wisconsin. Both examples distinguish wages from other income. Michigan also cautions that a reciprocal-state resident may need to file to recover tax withheld from Michigan wages.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteRank #3
- Ruled Pages with Page Numbers and Fields for Subject, Date and Book Number
- Hard Bound Book with Reinforced Imitation Leather Cover, and Placeholder Ribbon
- Section Sewn - Books lies flat when open; Archival Quality, Acid-Free Paper
- Page Dimensions: 8.5" X 11" (21.6cm X 25.4cm )
Why you might file even if you think you owe no tax
Withholding is not the same as your final tax liability. A return may be the way to reconcile tax withheld with the amount actually due or to request a refund when tax was withheld in error. Illinois and Michigan describe refund-related filing situations, and Arizona and North Dakota also note circumstances in which a return may be filed to recover withholding.
How the nonresident return relates to your home-state return
You may have to file both a nonresident return in the state where income was earned and a resident return in your home state. A resident state may tax income regardless of where it was earned, but some states provide a credit for qualifying income tax paid to another state. The credit is governed by the resident state’s rules and may not eliminate all overlapping tax. Check the credit instructions rather than assume the nonresident return replaces your home-state return.
Before you decide, gather these details
- Your residence status for the tax year and the states where you lived.
- The locations where you physically worked, including any work performed in more than one state.
- Each category and amount of income connected to another state, including property, rental, business, or pass-through income.
- The applicable tax-year nonresident instructions and filing threshold for each state.
- Whether a reciprocity agreement applies to your residence state and income type.
- State tax withheld and whether you need to file to claim a refund.
- Your home state’s filing rules and its requirements for claiming a credit for tax paid elsewhere.
Thresholds and exceptions are state- and year-specific. A January 1, 2025 Tax Foundation compilation can provide broader context, but it is dated and should not replace the relevant state’s current forms and instructions. The examples above likewise do not determine your personal filing obligation; use the rules for your state, income, and tax year.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →



