Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsCash flow is the money a business receives and pays during a period. It is not the same as profit: a company can report income before customers pay, or record expenses before it pays the bills. A cash flow statement shows where cash came from, where it went, and how the business’s cash balance changed.
What is cash flow?
Cash flow is the movement of cash into and out of a business over a defined period, such as a month, quarter, or year. A cash flow statement reports those inflows and outflows and the resulting increase or decrease in cash. Unlike a balance sheet, which shows amounts at a particular date, the statement tracks movement over time. The U.S. Securities and Exchange Commission (SEC) explains that it draws on information from the income statement and balance sheet in its Beginners’ Guide to Financial Statements.


For a basic reading, the statement’s three sections add up to the net change in cash:
Operating cash flow + investing cash flow + financing cash flow = net change in cash
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall

- Daily Cash Flow Log Book 110 Pages Large Format:Daily Cash Flow Log Book with 110 pages in large 8.5 x 11 Inch format provides ample space for daily income expense tracking supporting long term financial record keeping
- Financial Record Keeping Notebook for Daily Accounting:Helps track cash in cash out balances and transactions making it ideal as a petty cash ledger book for small business store office and home accounting
- Structured Inner Page Accounting Fields:Daily Cash Flow Log Book pages include sheet number month year date from to starting balance date description cash in cash out balance total end date closing balance approved by and signature sections
- Petty Cash Large Ledger Book Spiral Bound:Petty Cash Large Ledger Book with spiral binding allows pages to lay flat for easy writing and efficient daily bookkeeping and cash management tasks
- Professional Cash Flow Ledger with Premium Paper:Daily Cash Flow Log Book uses 80 gsm double sided black and white printed pages with a laminated 300 gsm cover ensuring durability for long term financial tracking
Add that change to opening cash to get closing cash. This identity helps you follow a statement; it does not replace the accounting rules used to prepare one.
How is cash flow different from profit?
Profit is calculated using accounting rules, which can recognize revenue when it is earned and expenses when they are incurred—not only when money changes hands. Cash flow records receipts and payments. That difference in timing can make profit and cash movement diverge, as explained by OpenStax’s explanation of the statement of cash flows.
Rank #2
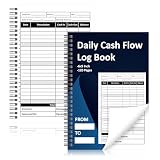
- 1.Daily Cash Flow Log Book 120 Pages Large Format:Daily Cash Flow Log Book with 120 pages in large 6 x 9 Inch format provides ample space for daily income expense tracking supporting long term financial record keeping
- 2.Financial Record Keeping Notebook for Daily Accounting:Helps track cash in cash out balances and transactions making it ideal as a petty cash ledger book for small business store office and home accounting
- 3.Structured Inner Page Accounting Fields:Daily Cash Flow Log Book pages include sheet number month year date from to starting balance date description cash in cash out balance total end date closing balance approved by and signature sections
- 4.Petty Cash Large Ledger Book Spiral Bound:Petty Cash Large Ledger Book with spiral binding allows pages to lay flat for easy writing and efficient daily bookkeeping and cash management tasks
- 5.Professional Cash Flow Ledger with Premium Paper:Daily Cash Flow Log Book uses 80 gsm double sided black and white printed pages with a laminated 300 gsm cover ensuring durability for long term financial tracking
| Measure | What it tells you | Why it can differ |
|---|---|---|
| Accounting profit | Revenue minus expenses recognized for the period | Revenue may be recorded before cash is collected, and expenses before cash is paid. |
| Cash flow | Cash received and paid during the period | It reflects the timing of actual cash receipts and payments. |
For example, a business might make a sale on credit and record revenue even though the customer has not paid yet. It can therefore show a profit while having less cash available than the profit figure suggests. The reverse can also happen: receiving a loan increases cash, but it does not represent sales profit.
What are the three sections of a cash flow statement?
Each section groups cash flows by the kind of business activity involved. The categories help distinguish cash generated by day-to-day trading from cash spent on assets or obtained through funding.
Operating activities
Operating activities cover cash tied to the business’s core revenue-producing work and its ordinary operating payments. Examples include money received from customers and money paid to suppliers or for operating costs. Changes in inventory, receivables, and other operating assets and liabilities can also affect this section. The SEC describes how the indirect presentation reconciles net income to operating cash by adjusting for noncash items such as depreciation and changes in operating assets and liabilities. The New Zealand government’s guide to understanding cash flow statements includes small-business examples such as customer receipts, supplier payments, interest, and tax.
Investing activities
Investing activities generally include cash paid for or received from long-term assets and investments. Buying machinery uses cash; selling a long-term asset or an investment can bring cash in. A large investing outflow is not automatically a warning sign: it may reflect a planned purchase intended to support the business.
Rank #4

- 1.Daily Cash Flow Log Book 120 Pages Large Format:Daily Cash Flow Log Book with 120 pages in large 6 x 9 Inch format provides ample space for daily income expense tracking supporting long term financial record keeping
- 2.Financial Record Keeping Notebook for Daily Accounting:Helps track cash in cash out balances and transactions making it ideal as a petty cash ledger book for small business store office and home accounting
- 3.Structured Inner Page Accounting Fields:Daily Cash Flow Log Book pages include sheet number month year date from to starting balance date description cash in cash out balance total end date closing balance approved by and signature sections
- 4.Petty Cash Large Ledger Book Spiral Bound:Petty Cash Large Ledger Book with spiral binding allows pages to lay flat for easy writing and efficient daily bookkeeping and cash management tasks
- 5.Professional Cash Flow Ledger with Premium Paper:Daily Cash Flow Log Book uses 80 gsm double sided black and white printed pages with a laminated 300 gsm cover ensuring durability for long term financial tracking
Financing activities
Financing activities show cash related to borrowing and contributed equity. Taking out a loan or issuing shares or bonds can bring cash in; repaying loan principal uses cash. Dividends may also be classified as financing cash flows under applicable presentations. The classification of particular transactions depends on the accounting framework and circumstances.
Why does cash flow matter?
A cash flow statement helps readers assess whether a business is generating cash through its operations, how it is funding investment, and whether it may need additional financing. It can also help show whether reported income has translated into cash receipts and whether cash is available to meet obligations. SEC Chief Accountant Paul Munter described the statement as “a critical piece of a complete picture of an issuer’s financial health and operations” in a December 4, 2023 staff statement. That statement was provided in his official capacity, does not necessarily reflect the views of the Commission or other staff, and has no legal force or effect.
Free tools Windows power users keep installed
One-click scans. No signup required.
Cash flow is useful evidence, but one number cannot establish that a business is profitable, solvent, or a good investment. The source and pattern of the cash matter: operating receipts are different evidence from a new loan or the sale of an asset.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How to read a cash flow statement
- Check the reporting period. Confirm whether the statement covers a month, quarter, or year. Cash movement is measured over that period.
- Read operating activities first. Look at cash generated or used in the core business. If the statement uses the indirect method, it starts from an earnings figure and adjusts for noncash items and changes in operating assets and liabilities.
- Review investing activities. Identify major purchases or sales of long-term assets and investments. Consider whether the flows fit the business’s plans rather than treating every outflow as a problem.
- Review financing activities. Note whether cash came from borrowing or contributed equity, or went to debt repayments or dividends.
- Reconcile the total. Add the three sections to find the net change in cash, then compare it with opening and closing cash. The New Zealand government guide explains this relationship in its cash flow statement guide.
- Interpret the direction and source together. A positive net change means cash increased during the period, not necessarily that operations were profitable. A negative change means cash decreased; planned growth or investment may explain one period, while repeated declines warrant closer attention to collections, timing, costs, and financing.
Direct and indirect methods: what changes?
The direct and indirect methods are different ways of presenting operating cash flows. The direct method shows cash receipts and payments. The indirect method starts with net income (or the relevant profit subtotal under the applicable rules) and adjusts for noncash items and changes in operating assets and liabilities. They do not describe different underlying cash movements; they present operating cash flow differently.
Formal presentation requirements vary by jurisdiction and accounting framework. The IFRS Foundation’s IAS 7 overview describes the standard’s operating, investing, and financing categories and notes that IFRS 18, issued in April 2024, amended IAS 7. The amendments use the IFRS 18 operating profit or loss subtotal as the indirect-method starting point and introduce requirements for classifying interest and dividend cash flows. For reporting or compliance, check the framework and effective date that apply to the business; rules may differ elsewhere.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




