High-yield savings account rates near 5.00% APY in March 2026 reflect a rare alignment between restrictive monetary policy and competitive pressure among online banks. These yields remain far above long-term historical norms for cash savings, which typically track closer to inflation rather than exceeding it. The persistence of elevated rates has drawn increased attention from retail savers seeking stability without market risk.
APY, or annual percentage yield, represents the total interest earned on a deposit over one year, including the effect of compounding. A 5.00% APY means interest is earned not only on the initial deposit but also on previously credited interest, assuming the rate remains unchanged. Because savings accounts use variable rates, the stated APY is not guaranteed beyond the current period.
Why Savings Rates Remain Elevated in March 2026
The primary driver of today’s high savings rates is a still-restrictive interest rate environment set by the Federal Reserve. Banks price deposit rates based on short-term benchmark rates, which influence how valuable customer deposits are for funding loans and maintaining liquidity. As long as policy rates remain elevated, banks can economically justify paying savers historically high yields.
Competition among online-only banks and fintech platforms further sustains these rates. Institutions without physical branch networks often operate with lower overhead, allowing them to pass more yield to depositors. This competitive dynamic has compressed the gap between the highest-paying accounts, resulting in clusters of offerings near the 4.75% to 5.00% APY range.
#1 Best Overall

- Effective Budget Plan Book – Take control of your finances with the SUNEE budget account book. This all-in-one budget planner allows you to plan and track your income, expenses, savings, and financial goals. Its intuitive layout and easy-to-use sections help you stay organized and make smart decisions to reach financial success. Our financial planner also included a comprehensive guidebook with valuable tips and instructions to help you get the most out of your budgeting planner.
- Full-Page Calendars – Each month’s full-page calendar provides plenty of space to track paydays, bills due dates, appointments, and important events. No more cramped boxes or tight writing areas, you can easily plan and organize your schedule at a glance.
- Colorful Pages Layout and Tabs – This vibrant budget planner features a user-friendly design for easy navigation and organization. Each month includes dedicated budget pages to set financial goals, track income, and plan expenses. Additional sections like debt trackers, savings goals, and bill payment trackers make managing your finances a breeze. The colorful backgrounds on each page offer clear, instant visibility.
- Bonus 4 Stickers and Convenient Design – This monthly budget planner is built for convenience and durability. Water-resistant cover protects against spills, while the elastic band keeps everything secure, and the dual-sided pocket offers extra storage. Plus, we’ve included 4 adorable sticker sheets to personalize your planner and make budgeting more enjoyable. Experience a budget planner that combines practicality with lasting quality.
- UNDATED DESIGN & 1 YEAR USE - Undated finance books start with 1 page-financial goals, 1 page-Mind Map, 1 page-Financial Strategy, 1 page-Tactics, 2 pages-Important Dates, 4 pages-Bill Tracker, 4 pages-Saving Tracker, 8 pages-Debt Tracker, followed by 12 Months(10 pages per month, 1 unique color for each month). 2 pages-Christmas Budgeting, 2 pages-Yearly Summary, 2 pages-Check Register and 12 pages-Notes(dotted). It is UNDATED, so you could start at any time, suitable for 1 year use.
Why 5.00% APY Is Not Permanent
Savings account rates are inherently variable, meaning banks can adjust APYs at any time without notice. When monetary policy shifts toward easing, deposit rates typically decline quickly as banks no longer need to incentivize new cash inflows. Historically, savings rates fall faster than loan rates once interest rate cycles turn.
Promotional pricing also plays a role. Some institutions use temporarily elevated APYs to attract deposits, with the expectation that rates will normalize once balances stabilize. Evaluating whether a high rate is sustainable requires attention to the bank’s rate history, balance requirements, and fee structure rather than the headline yield alone.
Safety, Liquidity, and Account Structure Considerations
High-yield savings accounts are designed to provide liquidity, meaning funds can be accessed without market risk or price fluctuation. However, access terms vary by institution, including withdrawal limits, transfer processing times, and minimum balance thresholds. These features affect usability even when the APY is attractive.
Account safety depends on Federal Deposit Insurance Corporation coverage, which protects deposits up to $250,000 per depositor, per institution, per ownership category. FDIC insurance eliminates credit risk from bank failure but does not protect against rate changes or inflation erosion. Evaluating a savings account in March 2026 requires weighing yield alongside institutional stability, transparency, and consistency, not simply the highest advertised APY.
Recommended Free Tools
How High-Yield Savings Account APYs Actually Work (And Why Quoted Rates Can Be Misleading)
Understanding how advertised yields function is essential when comparing savings accounts clustered near 5.00% APY in March 2026. While the quoted rate appears straightforward, the mechanics behind it introduce nuances that materially affect realized returns. These mechanics explain why two accounts advertising similar APYs can produce different outcomes for depositors over time.
What APY Measures—and What It Does Not
Annual Percentage Yield (APY) represents the effective annual rate of return assuming interest compounds over a full year and the balance remains unchanged. Compounding refers to earning interest not only on the original deposit but also on previously earned interest. Most high-yield savings accounts compound daily or monthly, which slightly increases returns compared to simple interest.
APY does not reflect how long a quoted rate will remain in effect. Because savings account rates are variable, the APY shown today is a snapshot rather than a contractual guarantee. Any change in the underlying interest rate environment can alter future earnings without notice.
Variable Rates and the Illusion of Stability
Unlike certificates of deposit, high-yield savings accounts do not lock in rates for a fixed term. Banks retain full discretion to raise or lower APYs based on funding needs, competitive pressures, and monetary policy. This flexibility benefits institutions but introduces uncertainty for depositors planning around a specific yield.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
During periods of declining benchmark interest rates, savings APYs tend to adjust downward rapidly. The headline rate may therefore overstate expected annual earnings if held through a rate-cutting cycle. Evaluating past rate behavior provides more insight than relying on the current figure alone.
Promotional APYs and Tiered Rate Structures
Some institutions advertise elevated APYs that apply only for a limited time or up to a capped balance. Promotional rates may revert to a lower standard rate after a predefined period, sometimes without explicit reminders. Tiered structures, where higher balances earn lower yields or vice versa, further complicate comparisons.
In these cases, the advertised APY reflects a best-case scenario rather than the typical depositor experience. Understanding how balances are segmented and how long promotional pricing lasts is necessary to estimate realistic returns.
Compounding Frequency and Interest Crediting Timing
While APY standardizes compounding assumptions, the timing of interest crediting still matters. Interest may be calculated daily but credited monthly, meaning funds withdrawn mid-cycle may not earn the full expected amount. This distinction affects liquidity-sensitive savers who move cash frequently.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Accounts with identical APYs can therefore deliver slightly different outcomes depending on how balances fluctuate throughout the month. These differences are modest but become more pronounced with larger balances.
Fees, Balance Requirements, and Net Yield
APY is quoted before accounting for fees or penalties. Monthly maintenance fees, excess withdrawal charges, or minimum balance requirements can materially reduce net yield. A 5.00% APY loses significance if account terms erode interest earned.
Evaluating net yield requires subtracting any recurring costs from expected interest income. This step is essential when comparing accounts that appear equivalent based on headline rates alone.
Why Headline APYs Should Be a Starting Point, Not a Decision Tool
Quoted APYs function as marketing signals rather than comprehensive performance indicators. They convey how aggressively an institution is pricing deposits at a given moment, not how the account will behave over time. Sustainable value depends on consistency, transparency, and alignment with liquidity needs.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →In a market where many accounts advertise near-identical yields, understanding the mechanics behind APY becomes the differentiating factor. The highest number on a rate table rarely tells the full story.
Rank #2

- Effective Budget Planning - Take control of your finances with the budget account book. This comprehensive planner allows you to plan and track your income, expenses, savings, and financial goals in one convenient place. With its intuitive layout and easy-to-use sections, you can stay organized and make informed decisions to achieve financial success.
- User-Friendly Layout - The budget planner features a user-friendly layout designed for easy navigation and organization. Each month, you'll find dedicated budget pages where you can set financial goals, track your income, and plan your expenses. Additional sections include debt trackers, savings goals, bill payment trackers, and more, making it simple to stay on top of your finances.
- Undated Monthly Calendar & Bonus Stickers - Featuring undated calendar each month, you'll have ample space to mark paydays, bills due, appointments, and important dates. Say goodbye to difficult writing spaces. Plus, we've included 3 cute sticker sheets that allow you to personalize your financial organizer and make budgeting more fun. Dates are not pre-printed and are completed by the user.
- Reliable and Convenient Design - Our monthly budget planner is designed for your convenience and built to last. The elastic band keeps everything securely in place, and the dual-sided pocket provides extra storage. Experience a budget planner that combines practicality and durability.
- Master Budgeting with Ease - Our financial planner includes a complete guidebook that provides valuable insights and instructions for optimal usage. From setting financial goals to tracking expenses, this guidebook offers step-by-step guidance and practical tips. Whether you're new to budgeting or an experienced user, this resource will help you make the most of your budget planner, empowering you to achieve financial success.
Best High-Yield Savings Accounts for March 2026: Rate Comparison and Key Features
Against this backdrop, a rate comparison is most useful when it is paired with a close examination of account structure and risk. As of March 2026, several federally insured institutions continue to offer savings APYs near or at 5.00%, though the conditions attached to those rates vary meaningfully. The accounts below represent widely accessible options for retail savers, not endorsements or recommendations.
Representative High-Yield Savings APYs Available in March 2026
As of this month, leading online banks and digital divisions of traditional banks cluster within a narrow rate band. Advertised APYs generally range from approximately 4.70% to 5.05%, with 5.00% serving as a psychological pricing threshold rather than a guarantee of superior outcomes.
Institutions offering APYs at the top of this range are typically online-only banks with lower overhead costs. Traditional banks with extensive branch networks tend to lag slightly, often pricing between 4.50% and 4.80% APY while emphasizing integrated checking, ATM access, and customer service infrastructure.
Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsFDIC Insurance and Institutional Safety
All legitimate high-yield savings accounts should be backed by Federal Deposit Insurance Corporation (FDIC) coverage or National Credit Union Administration (NCUA) coverage for credit unions. FDIC insurance protects deposits up to $250,000 per depositor, per institution, per ownership category, in the event of bank failure.
High APY alone does not indicate higher risk when FDIC coverage is present, but savers should confirm that the account is held directly at the insured institution. Some fintech platforms act as intermediaries, spreading deposits across partner banks; this structure can still be insured but requires additional diligence to verify coverage limits.
Rate Variability and Promotional Pricing Risk
Most high-yield savings accounts in March 2026 feature variable APYs, meaning rates can change at any time at the bank’s discretion. These changes are typically influenced by Federal Reserve policy, competitive deposit flows, and internal funding needs.
Some institutions advertise promotional APYs that apply only for a limited period or up to a capped balance. Once the promotional window expires, balances may revert to a materially lower standard rate, reducing long-term yield for savers who do not actively monitor changes.
Liquidity, Access, and Transaction Limitations
Savings accounts are designed for liquidity, but access terms differ. Many high-yield accounts allow unlimited electronic transfers, while others still impose internal limits or delays on outbound transfers, particularly for large withdrawals.
Interest is commonly calculated daily and credited monthly. Funds withdrawn before the crediting date may not earn interest for that cycle, which can slightly reduce realized yield for savers who move cash frequently. This factor is often overlooked when comparing accounts solely by APY.
Fees, Minimums, and Balance Tier Structures
Most competitive high-yield savings accounts advertise no monthly maintenance fees and no minimum balance requirements. However, exceptions exist, particularly among accounts offering the very highest headline APYs.
Tiered balance structures are increasingly common. Under these models, only a portion of the balance earns the top APY, while excess funds earn a lower rate. Savers with balances above tier thresholds may experience blended yields that fall below the advertised maximum.
Free tools Windows power users keep installed
One-click scans. No signup required.
Evaluating Accounts Beyond the Rate Table
A disciplined comparison weighs APY alongside safety, transparency, and operational consistency. Accounts that maintain competitive rates across multiple interest-rate cycles tend to deliver more predictable outcomes than those relying on short-term pricing spikes.
For cash-conservative investors, the primary role of a high-yield savings account is capital preservation with modest income. Evaluating how an account behaves when rates eventually decline is as important as capturing a temporary 5.00% APY during favorable conditions.
Beyond the Headline APY: Fees, Minimums, Withdrawal Rules, and Access to Your Cash
While APY captures the most attention, it represents only one component of total account value. The practical experience of using a high-yield savings account depends on its cost structure, balance requirements, transaction flexibility, and how quickly funds can be accessed when needed. These factors determine realized yield, not just advertised yield.
Fee Structures and Their Impact on Net Yield
Most leading high-yield savings accounts in March 2026 promote zero monthly maintenance fees, but fee-free status should never be assumed. Some institutions impose charges for paper statements, excessive withdrawals, wire transfers, or account inactivity. Even small recurring fees can materially offset interest earned, particularly for moderate balances.
Fees should be evaluated relative to account usage patterns. An account with a slightly lower APY but no ancillary charges may generate a higher effective return than a higher-yielding account with transactional costs. Transparency and consistency in fee disclosures are therefore critical evaluation criteria.
Minimum Balance Requirements and Funding Constraints
High-yield accounts vary widely in minimum opening deposits and ongoing balance requirements. While many online banks allow accounts to be opened with minimal or no initial funding, others require substantial deposits to qualify for their top advertised rate. Failure to maintain required balances may result in lower interest rates or the imposition of fees.
Rank #3

- Effective Budget Planning - Take control of your finances with the budget account book. This comprehensive planner allows you to plan and track your income, expenses, savings, and financial goals in one convenient place. With its intuitive layout and easy-to-use sections, you can stay organized and make informed decisions to achieve financial success.
- User-Friendly Layout - The budget planner features a user-friendly layout designed for easy navigation and organization. Each month, you'll find dedicated budget pages where you can set financial goals, track your income, and plan your expenses. Additional sections include debt trackers, savings goals, bill payment trackers, and more, making it simple to stay on top of your finances.
- Undated Monthly Calendar & Bonus Stickers - Featuring undated calendar each month, you'll have ample space to mark paydays, bills due, appointments, and important dates. Say goodbye to difficult writing spaces. Plus, we've included 3 cute sticker sheets that allow you to personalize your financial organizer and make budgeting more fun. Dates are not pre-printed and are completed by the user.
- Reliable and Convenient Design - Our monthly budget planner is designed for your convenience and built to last. The elastic band keeps everything securely in place, and the dual-sided pocket provides extra storage. Experience a budget planner that combines practicality and durability.
- Master Budgeting with Ease - Our financial planner includes a complete guidebook that provides valuable insights and instructions for optimal usage. From setting financial goals to tracking expenses, this guidebook offers step-by-step guidance and practical tips. Whether you're new to budgeting or an experienced user, this resource will help you make the most of your budget planner, empowering you to achieve financial success.
Balance minimums also interact with tiered APY structures. When only a portion of funds earns the highest rate, excess balances may dilute overall yield. Savers with larger cash reserves must calculate blended returns rather than relying on headline figures.
Withdrawal Rules and Transaction Limitations
Although federal Regulation D limits on savings withdrawals were relaxed, many banks continue to enforce internal transaction caps. These limits often restrict the number of outbound electronic transfers per month or trigger delays for frequent withdrawals. Such policies can affect liquidity during periods of unexpected cash need.
Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchWindows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallTiming also matters. Withdrawals executed before monthly interest crediting may reduce interest earned for that period, particularly in accounts that calculate interest daily. Understanding these mechanics is essential for savers who actively move funds between accounts.
Speed of Access and Cash Availability
Access to funds varies meaningfully across institutions. Some high-yield savings accounts support same-day internal transfers or instant access through linked checking accounts, while others require one to three business days for ACH transfers. Wire transfers may offer faster access but often involve fees.
For cash-conservative investors, liquidity is not merely theoretical availability but practical usability. Emergency funds should prioritize predictable access timelines over incremental yield differences, especially when rate gaps are narrow.
Operational Stability and Safety Considerations
Beyond usability, institutional stability underpins all savings decisions. FDIC insurance, which protects deposits up to $250,000 per depositor per institution, safeguards principal but does not address operational disruptions or service reliability. Accounts offered through fintech platforms may rely on partner banks, adding structural complexity.
Consistency in rate-setting behavior, customer service responsiveness, and system reliability contributes to long-term suitability. Evaluating these qualitative factors alongside quantitative terms provides a more accurate picture of an account’s true value beyond the advertised APY.
Safety First: FDIC Insurance, Bank Stability, and What ‘Risk-Free’ Really Means
Liquidity and yield matter, but safety defines whether a savings account fulfills its core purpose. High-yield savings accounts are often described as “risk-free,” yet that label depends on specific legal protections, institutional structures, and practical access to funds. Understanding these distinctions is essential when evaluating accounts offering elevated APYs in March 2026.
FDIC Insurance: What Is Actually Protected
The Federal Deposit Insurance Corporation (FDIC) is a U.S. government agency that insures bank deposits against bank failure. Coverage extends up to $250,000 per depositor, per insured bank, per ownership category, including accrued interest. This protection applies to savings accounts, checking accounts, and certificates of deposit held at FDIC-member banks.
FDIC insurance protects depositors from bank insolvency, not from market-driven interest rate changes or account-level restrictions. If a bank fails, insured deposits are typically made available within days, either through a transfer to another institution or a direct payout. Amounts exceeding insurance limits remain exposed to the bank’s liquidation process.
Ownership Categories and Coverage Optimization
Insurance limits apply separately across ownership categories, such as individual accounts, joint accounts, and certain trust accounts. For example, a single depositor may hold $250,000 in an individual account and an additional $250,000 in a joint account at the same bank without exceeding coverage limits. Accurate account titling is critical, as misclassification can unintentionally concentrate uninsured balances.
For savers with balances approaching or exceeding FDIC thresholds, spreading funds across multiple insured institutions is a structural risk-management tool. Some banks offer sweep or network programs that distribute deposits across partner banks, though these arrangements introduce additional layers of complexity that should be clearly documented.
Bank Stability Versus Platform Branding
Many high-yield savings accounts are marketed through fintech platforms rather than traditional banks. In these cases, the fintech typically provides the user interface, while one or more chartered banks hold the deposits. FDIC insurance applies only if the underlying bank is insured and the depositor is properly recorded as the beneficial owner.
This structure does not inherently increase credit risk but can affect operational reliability. Account access during outages, dispute resolution, and customer service responsiveness depend on coordination between entities. Evaluating the actual deposit-holding bank, not just the brand name, is a necessary step in assessing stability.
What ‘Risk-Free’ Means for Cash Savings
In financial terms, “risk-free” refers narrowly to the risk of principal loss due to default. FDIC-insured savings accounts meet this definition within coverage limits, as principal is protected even if the bank fails. However, they are not risk-free in a broader economic sense.
Interest rate risk remains, as APYs can change at any time and may lag inflation. Liquidity risk can also arise from withdrawal limits, processing delays, or temporary access disruptions. These factors do not threaten principal but can reduce the account’s usefulness during periods of financial stress.
Separating Safety From Yield
High APYs often attract attention, but safety is determined by legal protections and institutional resilience rather than headline rates. Two accounts offering identical yields may differ meaningfully in insurance structure, operational stability, and access reliability. These differences become most visible during periods of market volatility or systemic stress.
Rank #4

- ALL-IN-ONE B5 BUDGET PLANNER: With 15+ Functional Inserts –it covers every money-management pain point for beginners & pros. Stop juggling messy notebooks or incomplete trackers! The budget planner includes, monthly budget, bill expense detail, debt tracker, bill tracker, saving tracker...matches 90% of "how to manage money" search queries
- DURABLE BUDGET BOOK: Our budget organizer features a PVC waterproof cover and elastic band—no more ruined pages, made of 100GSM thick paper—no smudges or ghosting, coming with a heavy-duty double spiral binding—lays flat for easy writing. Built for daily use: toss it in your work bag, backpack, or purse without worry
- CONVENIENT B5 SIZE (7.3”X10.15”): No more choosing between "too small to write" or "too bulky to carry"! The B5 budget planner gives ample space to log expenses, note bill due dates, or map financial goals—without being cumbersome. Fits easily in laptop bags, backpacks, or purses—perfect for "on-the-go budget tracking
- UNMATCHED VALUE & COMPREHENSIVE GUIDEBOOK: Comes with 5 practical, high-quality freebies crafted, plus a comprehensive user guide that takes the guesswork out of financial planning. You’ll get: PVC waterproof colorful monthly tabs & wide range of label stickers, a ribbon bookmark, an elastic pen holder, a elastic band, an inner pocket, and a detailed step-by-step user guide handbook
- VISUAL CLARITY & LESS FATIGUE: Unlike plain black-and-white budget planners, our vivid color highlights reduce eye strain during long budgeting sessions, helping you track expenses, savings, and bills quickly and accurately. It’s the perfect fit for working professionals, international students, family financial managers, freelancers, new graduates, retirees
For cash-conservative investors, a savings account’s role is capital preservation with dependable access. Evaluating FDIC coverage, bank structure, and operational track record provides a clearer measure of safety than yield alone, particularly when rate advantages are narrow and potentially temporary.
Rate Volatility Explained: How and Why High-Yield Savings Rates Change Over Time
The distinction between safety and yield leads directly to the issue of rate volatility. Unlike fixed-rate instruments, high-yield savings accounts have variable interest rates that can change at the bank’s discretion. Understanding the structural reasons behind these changes is essential for evaluating whether a headline APY is durable or temporary.
The Federal Funds Rate as the Primary Driver
High-yield savings rates are indirectly anchored to the federal funds rate, which is the overnight interest rate at which banks lend reserves to one another. This rate is set through monetary policy decisions by the Federal Reserve and serves as the foundation for short-term interest rates across the financial system. When the federal funds rate rises or falls, banks typically adjust savings APYs in the same direction.
However, changes are neither automatic nor uniform. Banks may raise rates quickly when competing for deposits during tightening cycles, but reduce them more gradually when policy eases. This asymmetry explains why savings rates often lag rate cuts but closely track rate hikes.
Why Savings APYs Are Variable by Design
A variable APY allows banks to manage funding costs dynamically. Deposits represent a liability on a bank’s balance sheet, and the interest paid on savings accounts must remain economically viable relative to what the bank earns on loans and securities. When market yields decline, maintaining elevated savings rates can compress profit margins, incentivizing rate reductions.
Recommended Free Tools
For depositors, this means the advertised APY reflects current conditions, not a guaranteed return over time. Even accounts labeled as “high-yield” have no contractual obligation to maintain a specific rate, regardless of marketing language.
Competitive Pressures and Promotional Pricing
Rate volatility is also influenced by competition among online banks, fintech platforms, and traditional institutions. Some providers offer above-market APYs to attract new deposits quickly, particularly during periods of strong consumer cash inflows. These rates may be supported by short-term strategic objectives rather than long-term funding needs.
Such pricing can reverse once deposit targets are met or competitive dynamics shift. A rate that appears to lead the market in March 2026 may converge toward the average within months, especially if overall interest rates stabilize or decline.
Why Identical Economic Conditions Produce Different Rates
Even in the same rate environment, savings APYs vary meaningfully across institutions. Differences in balance sheet structure, loan demand, access to wholesale funding, and growth strategy all affect how much a bank is willing to pay for deposits. Smaller or rapidly expanding banks may offer higher rates than larger, well-funded institutions.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesOperational considerations also matter. Banks with higher customer acquisition costs or limited cross-selling opportunities often rely more heavily on interest rates to attract deposits, increasing volatility over time.
Implications for Evaluating High-Yield Accounts
Rate volatility does not indicate increased credit risk or reduced FDIC protection. It reflects the economic reality that savings accounts are floating-rate instruments tied to short-term monetary conditions and bank-specific incentives. Evaluating an account therefore requires more than comparing current APYs.
A stable savings strategy prioritizes consistent access, transparent terms, and institutional reliability, with yield viewed as a variable component rather than a fixed benefit. Understanding why rates change clarifies why short-term APY leadership should not be mistaken for long-term suitability.
Choosing the Right Savings Account for Your Goals: Emergency Funds vs. Short-Term Cash vs. Parking Money
Understanding why savings rates fluctuate sets the foundation for selecting an account that fits a specific cash purpose. Because high-yield savings accounts are variable-rate instruments, suitability depends less on today’s APY and more on how the account functions under changing conditions. The same account can be appropriate for one goal and inefficient for another.
Free tools Windows power users keep installed
One-click scans. No signup required.
Different cash categories impose different requirements for access, stability, and tolerance for rate movement. Evaluating a savings account therefore begins with defining the role the cash plays rather than chasing the highest advertised yield in March 2026.
Emergency Funds: Prioritizing Liquidity and Reliability Over Yield
An emergency fund is cash reserved for unexpected expenses such as medical bills, job loss, or urgent repairs. The defining characteristics are immediate accessibility, minimal risk, and predictable account behavior. Yield is secondary to certainty.
For emergency savings, a high-yield savings account with no withdrawal penalties, no minimum balance requirements, and fast transfer capabilities is essential. Rate variability is acceptable, but abrupt restrictions on access are not. A slightly lower APY can be rational if the institution offers consistent customer service, clear terms, and operational stability.
Federal Deposit Insurance Corporation (FDIC) insurance, which protects deposits up to $250,000 per depositor per bank, is non-negotiable for emergency funds. This insurance eliminates credit risk, meaning the depositor is protected even if the bank fails, provided balances remain within coverage limits.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Best Value
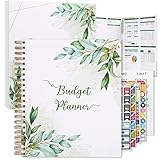
- Keep Track of Your Finances: Manage your personal and family’s finances with this monthly budget planner! Intuitive, comprehensive and fun, this budgeting planner allows you to keep track of your debts, expenses and bills, organize your spending and saving and optimize your budget for achieving your financial goals!
- Large Budgeting Planner: Our budget notebook features a large design of 8.5 x 11-inch that provides enough space for budgeting, financial planning and spending tracking but also for monthly reviews and building strategies for optimizing your budget!
- Well-Organized for Your Convenience: This budget book planner features an easy yet efficient template that includes a monthly budget with customizable categories, a debt tracker, a bill tracker, an expenses tracker as well as a section for financial goals and monthly review that will make things easier when it comes to budget planning!
- 12-Month Budget Management: Our budgeting book features a spiral-bound hardcover design made with high-quality 120gm thick paper and a 12-month undated design that allows you to start budget planning at any time of the year!
- Chic, Practical, Giftable: Featuring a superb boho cover and packed in a matching gift box, this budget book journal makes a lovely gift for a friend, family member or co-worker! The budget journal includes a special pocket for bills, receipts or other documents and comes with 5 stickers that will make your planning more fun and effective!
Short-Term Cash: Balancing Yield, Timing, and Access
Short-term cash refers to funds earmarked for known expenses within a defined timeframe, typically three to eighteen months. Examples include down payments, tuition payments, or planned large purchases. In this context, earning interest matters, but access timing still constrains account choice.
High-yield savings accounts are often suitable for short-term cash because they offer daily liquidity while paying interest tied to prevailing short-term rates. Annual Percentage Yield (APY) reflects the effective annual return, including compounding, but it is not guaranteed to persist. A competitive APY in March 2026 may decline before the funds are needed.
When selecting an account for short-term cash, attention should be paid to transfer limits, processing times, and any transaction caps. Fees for excessive withdrawals, while less common than in prior years, still affect net returns if access needs are underestimated.
Parking Money: Optimizing Yield on Idle Cash With Rate Awareness
Parking money describes surplus cash with no immediate use and flexible time horizons. This category includes proceeds from asset sales, temporarily idle business income, or strategic cash allocations awaiting redeployment. Yield sensitivity is highest here, and access requirements are lowest.
For parked cash, savers may reasonably favor accounts offering top-tier APYs, recognizing that these rates are often promotional or competitively driven. Rate volatility is expected, and periodic account changes may occur as market leaders shift. However, this approach requires monitoring and administrative effort.
Even when prioritizing yield, core safeguards still apply. FDIC insurance, transparent terms, and the absence of hidden fees remain critical. An elevated APY does not compensate for operational friction or unclear account disclosures.
Evaluating Account Features Across All Cash Categories
Across emergency funds, short-term cash, and parked money, several structural features determine long-term suitability. Rate variability is inherent and should be assumed rather than feared. Fees, access restrictions, and minimum balance requirements directly affect realized returns and usability.
Liquidity refers to how quickly and reliably funds can be accessed without loss. Safety is established through FDIC insurance and institutional soundness, not through yield levels. APY should be viewed as a variable input that enhances returns when favorable but does not define account quality.
Selecting a savings account is therefore an exercise in aligning cash purpose with account mechanics. High-yield savings accounts can serve multiple roles, but only when their limitations and behaviors are understood in advance.
Bottom Line: How to Lock In a Competitive Savings Strategy Without Chasing Rates
As the March 2026 rate environment continues to reward cash holders, the central challenge for savers is not finding a high headline APY, but maintaining a savings structure that remains effective as rates evolve. High-yield savings accounts offering around 5.00% APY reflect competitive conditions rather than permanent guarantees. The objective is therefore durability, not constant optimization.
Understand APY as a Variable, Not a Promise
Annual Percentage Yield (APY) represents the effective annual return on deposits, including the impact of compounding interest. In variable-rate savings accounts, APY can change at any time based on market conditions and institutional pricing decisions. A leading rate today does not imply leadership tomorrow.
Evaluating an account requires separating the institution’s current pricing strategy from its long-term account behavior. Consistency, transparency, and predictable adjustments matter more than brief periods at the top of comparison tables.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →Prioritize Structural Account Quality Over Headline Rates
Safety remains foundational. Federal Deposit Insurance Corporation (FDIC) insurance protects deposits up to applicable limits per depositor and institution, regardless of APY. Yield does not enhance safety, and lack of insurance introduces unnecessary risk for cash holdings.
Liquidity should align with the cash purpose. Savings accounts intended for emergencies or short-term obligations must allow timely withdrawals without penalties or processing delays. An additional 0.20% in APY is immaterial if access constraints interfere with financial flexibility.
Use Tiered Cash Allocation to Reduce Rate Sensitivity
A practical approach is to segment cash by function rather than forcing a single account to serve all needs. Core savings can reside in a stable, well-established high-yield account with reliable access and minimal friction. Excess or parked cash can be placed in more rate-competitive accounts where variability is expected and acceptable.
This structure reduces the need for constant account switching while still capturing favorable yields where appropriate. Administrative simplicity becomes a feature, not a cost.
The Tool Desk
Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Accept Rate Normalization as Part of the Strategy
Periods of elevated savings rates are cyclical. When policy rates eventually decline, savings yields will follow, regardless of provider. Attempting to outrun this process through frequent moves often results in diminishing returns after accounting for time, complexity, and missed interest during transfers.
A competitive savings strategy anticipates rate changes rather than reacting to them. Accounts should be selected with the expectation that APYs will fluctuate, not remain fixed.
Final Perspective: Control What Is Controllable
Savers cannot control future interest rate paths or institutional pricing decisions. What remains controllable is account selection discipline: insured balances, clear terms, appropriate liquidity, and alignment with cash purpose. High-yield savings accounts remain effective tools when used intentionally rather than tactically.
In March 2026, earning approximately 5.00% APY on cash is achievable. Sustaining a sound savings strategy, however, depends less on capturing the highest rate today and more on building a structure that continues to work as conditions change.
PC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Outdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchQuick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




