Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →The claim that banks adjusted loan limits “149 times” and confused borrowers is not verified by the available sources. A January 2026 Federal Reserve analysis does document frequent bank-initiated increases to U.S. credit-card limits—but it does not count all bank loan-limit changes or establish that borrowers were confused. Its findings offer a clearer picture of what happens when card issuers raise limits without a request.
What the “149 times” claim does—and does not—establish
The figure in the headline cannot be treated as a verified count: the available sources do not identify what was counted, over what period, or which lenders or types of loans were included. They also do not establish that the changes confused borrowers. The relevant Federal Reserve evidence concerns U.S. credit cards, not every kind of bank loan.
That distinction matters. A credit-card limit is the maximum amount a cardholder may borrow on that account. It is not the same as a limit on a mortgage, personal loan, or other installment loan. Nor does a study of card accounts establish how often every bank changes every borrower’s borrowing limits.
What the Federal Reserve found about credit-card limits
A January 16, 2026, note by Vitaly M. Bord, Agnes Kovacs, and Patrick Moran at the Board of Governors of the Federal Reserve System analyzes regulatory Y-14M data covering more than 70% of the U.S. credit-card market. The authors report that about 12% of credit cards receive a limit increase each year, adding about $160 billion in available credit annually. Approximately 80% of the increases are initiated by banks, rather than requested by cardholders. These figures describe the study’s U.S. credit-card data; they are not a count of all loan-limit adjustments. Read the Federal Reserve note.
#1 Best Overall
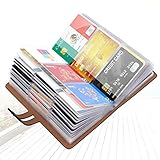
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
The note also reports different limit trajectories for borrowers in two credit-score groups. Among subprime borrowers with scores below 600, the average limit was $700 at origination and $2,700 five years later, a reported 285% increase. Among superprime borrowers with scores above 760, the average rose from $12,000 at origination to about $15,000 five years later, a reported 25% increase. These are group averages in the note’s credit-card data, not predictions for an individual account.
Why an issuer might increase a limit without a request
When an account is new, an issuer has limited information about how its holder uses credit. Over time, it can observe spending, account use, and payment behavior. The Federal Reserve authors describe limit increases as one way lenders respond to what they learn about an account.
Rank #2
- Large capacity business card storage: This book-style business card organizer can hold up to 240 business cards, two cards back-to-back in each pouch. It is very compact & professional. Enough capacity for your different cards: business cards, credit card, social security, gift cards, insurance cards, name cards, personal IDs, mini photos, and more
- Sturdy & Long-lasting card book: Name card holder is made from high-quality pu leather cover and PVC pocket sheets. Long-lasting and sturdy
- Easy to find & read: Card holder book transparent slots are good for reading and finding information on the business card
- Compact size business card folder: The slim profile and lightweight design make carrying a breeze – Carry it in your hand, pocket or handbag when on the go. Dimension: 7.7"x 4.5" x 0.7"
A higher limit can give a cardholder more room to borrow, including during a financial emergency. But added availability may also make it easier to carry a larger balance. The Federal Reserve note presents both possibilities; an increase does not, by itself, establish why an issuer acted or whether a particular cardholder will borrow more.
Who is more likely to receive an increase—and what the evidence says about debt
The Federal Reserve note reports that limit increases are more common among revolving borrowers—people who carry a balance from month to month. That is an association in the studied data, not proof of a lender’s intent in any individual case.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallOutdated Drivers Are Slowing You Down
One free scan finds every outdated or missing driver and matches the right update for your exact hardware.Free scan · exact hardware matchRank #3
- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
A related article in the Journal of Monetary Economics, “Automated credit limit increases and consumer welfare,” reports that revolving borrowers are more likely to receive bank-initiated increases and that debt rises after increases. It also evaluates possible restrictions using a quantitative model. Its policy results are simulations, not observed outcomes of a rule applied to every borrower. Read the journal article.
In that model, prohibiting increases for revolving borrowers produces an estimated 1.1% improvement in consumption-equivalent welfare and a roughly 2-percentage-point decline in the debt-to-income ratio. These are model estimates for the authors’ policy counterfactual, not guaranteed effects for an individual or proof that the same rule would produce the same results in practice. The article also describes a trade-off: some people may lose access to credit they would otherwise use.
Rank #4

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
What a cardholder can do if a limit changes
If an issuer raises a card limit and the change is unwelcome, the practical question is whether the new limit affects the cardholder’s own spending or borrowing choices. A higher ceiling does not require using the additional credit. Check the account notice and current card terms for the issuer’s explanation and any available options; the sources cited here do not establish a universal procedure for accepting, declining, or reversing an increase.
For people concerned about carrying more debt, the key distinction is between available credit and a balance actually borrowed. A larger limit expands what can be charged; it does not mean the cardholder has borrowed that amount. Whether the added availability is helpful or risky depends on the person’s circumstances, spending, and ability to repay.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Best Value
- Material: Genuine Cowhide Leather and PVC card slots.
- Size: 7.48"*3.54"*0.98" (19*9*2.5 CM)
- Large Capacity: The card holder has 60 cards slots and 2 ID Windows. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking Design: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift: Great gift for mother, daughter, grandmother and so on.
Why the rules depend on where you live
The Federal Reserve note describes U.S. requirements concerning ability to repay when limits are increased, as well as reason-giving in certain circumstances involving limit decreases or denied increase requests. The journal article discusses policy approaches in other countries, including restrictions on unsolicited increases and requirements for consumer consent.
Those descriptions are not a current, country-by-country legal guide. The sources do not establish the implementation date or present status of every policy described. Anyone seeking to understand a specific account or legal right should check the applicable regulator’s current guidance and the law in their jurisdiction.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




