Home equity can make a household wealthy on paper without making cash available when it is needed. With Freddie Mac’s 30-year mortgage-rate survey averaging 7.28% on October 1, 2026, advisors are weighing how to account for homes that may take time to sell or be costly to borrow against—without treating borrowing as the default answer.
Why mortgage rates change the liquidity calculation
Higher financing costs can make homes less affordable to prospective buyers. They can also discourage owners with low-rate mortgages from selling and taking on a more expensive loan elsewhere—the rate-lock-in effect. Neither factor guarantees a slower sale or a lower price for a particular home, but both can make it harder to assume that equity will be available on a household’s preferred schedule.
| Freddie Mac survey measure | Reported average | What the figure represents |
|---|---|---|
| 30-year fixed, week ended September 24, 2026 | 7.03% | National survey average; InvestmentNews reported it was the first reading above 7% since January 2025. |
| 30-year fixed, October 1, 2026 | 7.28% | National survey average. |
| 15-year fixed, October 1, 2026 | 6.60% | National survey average. |
Freddie Mac’s Primary Mortgage Market Survey reflects qualifying applications, not a rate quote or promise for an individual borrower. InvestmentNews also reported Treasury yields of roughly 5.5% for the 30-year bond and about 5.2% for the 10-year note at the time of its October 6, 2026 article; those are dated market observations, not live quotes.
Home-equity borrowing has become more visible in aggregate, though those trends do not establish whether it suits any one household. A Federal Reserve Bank of St. Louis analysis using New York Fed Consumer Credit Panel data constructed from Equifax, covering borrowers aged 20–64, found that the share of people with housing debt who had a HELOC rose from 9.18% in Q1 2022 to 10.82% in Q1 2026, an 18% increase. The inflation-adjusted HELOC amount per borrower rose from $67,357 in Q3 2022 to $76,562 in Q1 2026, a 14% increase. Separately, the CFPB reported that nearly one million consumers borrowed through home equity loans or lines in Q2 2022, 37% more than in Q2 2021; that is historical activity, not a 2026 volume estimate.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall

- ENTER DIMENSIONS JUST LIKE YOU SAY THEM: Input measurements directly in feet, inches, building fractions, decimals, yards and meters, including square areas and cubic volumes; one key instantly converts your measurements into all standard Imperial or metric math dimensions that work best for you and the project you are working on
- DEDICATED BUILDING FUNCTION KEYS: Make determining your project needs easy; just input project measurements, select material type like wallpaper, paint or tile; then calculate the quantity needed and total costs to avoid surprises at the homecenter checkout
- ACCURATE MATERIAL ESTIMATION: Helps you estimate material quantities and costs for your projects, ensuring you never buy too much or too little material; simplifies your home improvement and decorating jobs and cuts down on the number of trips to the hardware store
- PRECISE PAINT CALCULATIONS: Calculate exactly how much paint you need to ensure you finish the job without finding yourself with a half-painted room at night with a wet paint roller, and avoid storing or disposing of excess paint
- 11 BUILT-IN TILE SIZES: Make it easy to estimate the quantity needed to complete your project; simply calculate your square footage, then determine the tile required based on tile size and compare tile usage and costs by size; comes complete with hard cover, easy-to-follow user's guide, long-life battery and 1-year warranty
Should the home count as an investable asset?
It depends on what the plan is measuring. A home belongs on a household’s full balance sheet: it affects net worth, housing costs, retirement choices, debt management and estate planning. But its market value is not equivalent to cash or a readily saleable portfolio holding. Accessing it may require selling, moving, qualifying for a loan, taking on secured debt, or accepting fees and repayment obligations.
The advisors quoted by InvestmentNews in its October 6, 2026 article emphasize different parts of that distinction:
- Ryan Botzong, 49 Financial: He said some clients have a residence representing 60% to 70% of net worth. For those households, he plans as if home equity is less liquid than it once was and uses short-term cash or bond reserves to preserve flexibility if a sale takes longer. He also described a home’s utility—peace of mind, family life and gatherings—as distinct from investment growth, while noting that housing can still be an inflation hedge.
- Jim Worden, The Wealth Consulting Group: He generally does not count a home as an investable asset in a portfolio or financial plan unless the owner has borrowed against it and invested the proceeds. He cautioned against interest-only or negative-amortization borrowing when income is insufficient to support it.
- Vance Litchfield, Sagient: He includes the home in the full balance sheet and plan without treating it as a liquid investment. He points to downsizing, a home-equity strategy, refinancing when conditions permit, or building liquid assets outside the home as possible ways to create flexibility.
For retirement planning, the practical distinction is between wealth that can support a future choice and wealth that can only do so after a sale, move or financing decision. Botzong put the risk this way: “Ultimately, retirement is about having optionality. You may have a high net worth on paper because your house elevates it, but if you don’t have liquidity, you don’t have optionality. You have constraints.” Litchfield similarly warned against having a large share of retirement wealth in an asset that may be difficult or costly to access when income is needed.
Rank #2
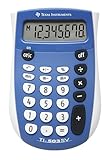
- Easy-to-read 8 digit display
- Large 7-millimeter display height
- Three key memory
- Switch key +/-
- Power saving LCD
How to test a household’s home-equity liquidity
- Separate housing utility from potential proceeds. Identify why the household wants to stay—such as family, location or support—and whether selling would be an acceptable way to access equity. A home can be valuable for its use even when its equity is not part of near-term spending capacity.
- Measure concentration. Compare the home’s value and mortgage debt with liquid investments and available cash. A high home-equity share can make a household’s net worth more dependent on one illiquid asset; Botzong reported seeing residences account for 60% to 70% of some clients’ net worth.
- Map the timing of cash needs. Identify expenses that may arise before a realistic sale or move could be completed. A slower sale or lower-than-hoped proceeds can matter more when the household has little cash or short-term bond reserves.
- Stress-test debt service before borrowing. For a variable-rate line, assess whether the borrower could manage higher rates and payments once the line is fully drawn and enters repayment. Include existing debt, income stability and essential living costs rather than relying on home value alone.
- Compare access strategies by their full consequences. Evaluate borrowing against the home, selling and downsizing, or increasing liquid assets outside real estate. Consider net proceeds after transaction and moving costs, the replacement home, personal preferences, and retirement and estate-plan effects.
What are the main ways to turn home equity into flexibility?
| Approach | How it works | Key planning trade-off |
|---|---|---|
| HELOC | Revolving credit secured by the home, generally with an adjustable rate, a draw period and a later repayment phase. | May avoid replacing a low-rate first mortgage, but adds secured debt and potentially changing payments. |
| Home equity loan | A fixed amount secured by the home, generally at a fixed rate and repaid over a set term. | May provide a defined amount and payment structure, but still creates a home-secured repayment obligation. |
| Cash-out refinance | Replaces the existing mortgage with a new first mortgage and releases part of the equity as cash. | Reprices the entire refinanced balance, not just the cash withdrawn; compare total costs and repayment term. |
| Downsizing | Selling the current home and buying or renting a less costly or better-suited residence. | Sale proceeds must be weighed against transaction and moving expenses, replacement housing, support needs and the value of staying. |
| Reverse mortgage | For eligible older borrowers, a home-secured loan that can provide funds in different payout forms, with interest added to the balance. | Occupancy, repayment triggers, fees, spouse and heir effects, and payout terms can substantially affect suitability. |
HELOCs and home equity loans
The CFPB explains that a HELOC typically lets the borrower draw repeatedly during a defined period—often about 10 years—before a repayment phase begins and additional draws stop. Because rates are usually adjustable, a payment affordable during the draw period may not remain affordable later. Federal Reserve guidance says borrowers should account for rate increases and the payments required to repay a fully drawn line.
A home equity loan is generally a one-time advance with a fixed rate and set repayment term. For either product, compare the amount and timing of the need, the rate structure, draw and repayment terms, total cost, and the borrower’s credit and income qualification. Using a home-secured loan to cover living expenses or unsecured debts does not remove those expenses; it changes the collateral at risk. The CFPB warns that failure to repay can put the home at risk.
Cash-out refinancing
A cash-out refinance replaces the existing first mortgage. If that mortgage has a low rate, compare the cost of repricing the full new balance with the cost of borrowing only the smaller amount needed through a second-lien product. Freddie Mac says refinance costs commonly run 3%–6% of mortgage principal; actual costs depend on the lender, credit score and location. Compare lender estimates, fees, interest rate, monthly payment, loan term, expected time in the home and whether the transaction extends the repayment period.
Rank #3

- COMPACT & PORTABLE DESIGN – Space-saving design that fits easily on any desk or in a briefcase, making it ideal for both home and office use.
- LARGE EIGHT-DIGIT DISPLAY – Clear and easy-to-read 8-digit display, perfect for everyday calculations, ensuring accurate results in home or office settings.
- GENERAL PURPOSE CALCULATOR – Ideal for a wide range of applications, from basic math to business and personal use.
- DUAL POWER SOURCE: Operates on solar power with battery backup to ensure reliable use in any lighting condition.
- DURABLE HARD COVER: Built-in protective case shields the calculator from scratches, drops, and everyday wear.
Downsizing or staying put
Downsizing can release equity without adding a new loan, but gross sale price is not the same as usable proceeds. Account for transaction and moving costs, the price and ongoing costs of replacement housing, location and support needs, and tax and estate considerations. A one- or two-person household with more space than it needs may want to consider the option, but there is no universal financial threshold that makes a move worthwhile. Include the personal value of remaining in the home in the decision.
Reverse mortgages
The FTC says a reverse-mortgage borrower generally must be at least 62. Depending on the product, funds may be available as a lump sum, monthly payments or a combination. Interest accrues into the balance, and repayment usually comes due when the borrower dies or moves out. Before proceeding, examine who must continue occupying the home, how a spouse or heirs may be affected, the time horizon, fees, non-recourse terms and payout structure.
The CFPB recommends considering alternatives such as waiting, conventional home-equity options, reducing expenses or moving, borrowing only what is needed, and receiving counseling from a HUD-approved counselor. Counseling can help an older homeowner understand the product and compare it with other choices.
Rank #4
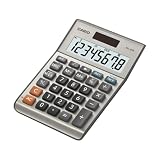
- LARGE EIGHT-DIGIT DISPLAY – Clear and easy-to-read 8-digit display, perfect for everyday calculations and ensuring accurate results in home or office settings.
- TAX & CURRENCY EXCHANGE FUNCTIONS – Effortlessly handle tax calculations and convert home currency to other currencies for easy financial management.
- GENERAL PURPOSE CALCULATOR – Ideal for a wide range of applications, from basic math to business and personal use, with memory keys for quick storage and recall.
- USER-FRIENDLY KEYBOARD – Easy-to-use layout, featuring square root, percent calculation, and simple functions that make it perfect for everyday tasks.
- COMPACT & PORTABLE DESIGN – Space-saving design that fits easily on any desk or in a briefcase, making it ideal for both home and office use.
Does refinancing make sense when the existing mortgage is cheaper?
Not automatically. The decision is about the cost and terms of the entire replacement loan compared with the alternatives—not simply whether cash is released. A household with a low-rate first mortgage may prefer to preserve it, but a second lien still has costs and puts the home behind the debt. A refinance may be worth comparing when its overall terms fit the household’s cash need, horizon and ability to pay.
- Request written estimates and compare the full fee total, not only the advertised rate or monthly payment.
- Compare the new mortgage balance and payment with the existing loan plus any proposed second-lien borrowing.
- Account for the expected time in the home and the effect of restarting or extending repayment.
- For adjustable borrowing, test affordability at higher rates and during the repayment phase.
Regardless of the financing route, borrowing converts some home equity into cash while creating a payment obligation secured by the home. If the plan depends on income the household cannot reliably support, preserving the property’s value on paper does not solve the cash-flow problem.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




