Recommended Free Tools
Long-term care insurance can help pay for eligible help at home or in a care facility, but it does not guarantee that every cost will be covered. Whether it makes sense depends on the policy’s limits and premium, the care you may want, your health and finances, and whether you can keep paying if premiums rise.
What long-term care insurance covers—and what it does not
Long-term care (LTC) is extended assistance for someone whose chronic illness, disability, or cognitive impairment makes everyday activities difficult. Depending on the policy, covered care may include help at home, adult day care, assisted living, or nursing-home care. Benefits are subject to the contract’s eligibility requirements, covered-service definitions, exclusions, and limits.
LTC is not the same as medical treatment or skilled nursing care. Medicare says it does not pay for most long-term care, much of which is non-medical support. Medicaid may help when a person meets the applicable state eligibility rules. Ordinary health insurance and Medicare Supplement (Medigap) policies generally do not fill the long-term-care gap.
Potential advantages of long-term care insurance
It can offset some eligible care costs
If you meet the policy’s claim requirements, benefits can help pay for covered care at home or in a facility, up to the policy’s limits. That may reduce the amount you or your family need to draw from savings or pay directly. It is not a promise that the insurer will cover the full cost of care.
#1 Best Overall

- ESSENTIAL Car Auto Insurance Registration BLACK Document Wallet Holders 2 Pieces
It may help you plan around care preferences
A policy that covers the settings you would consider can make it easier to plan for care at home, in adult day care, assisted living, or a nursing home. Coverage varies: check the contract’s definitions rather than assuming every setting or service is included. Benefits may also help reduce reliance on unpaid family caregiving, although they cannot guarantee that family support will not be needed.
A qualifying policy may support Medicaid asset planning
Some states offer Long-Term Care Partnership Programs. If a policy qualifies and the insured later meets Medicaid’s eligibility requirements, the state may allow an asset disregard tied to benefits the policy paid. This is not a feature of every policy or state. Confirm both the program’s current state rules and that the exact policy is partnership-qualified before counting on this protection.
Rank #2

- 👁️Quick Accessible: Inside the car insurance and registration card holder, the clear inner material makes you easy to find documents when you open it up, you can see exactly what they are and quickly show them when asked, even no need to take the stuff out.
- 💼Document Well Organized: The car document holder keeps your car documents organized and keep them tidy and secured, which make it easy to quickly identify and reach paper or cards in the folder. The glove box organizer for car has 6 compartments to keep all your car essential auto car essentials organized.
- 🧲Hidden Magnetic Closure: The glove box document holder are built with hidden magnetic closure, which will keep your car paperwork organizer neat and tidy and ensure the certifications stay closely and and completely protective within the registration pouch.
- 💖Premium Material: The car manual holder is made from high-quality ECO-friendly PU leather material. The car insurance holders with the best sewing and crafted is durable, wear-resistant, and has a luxurious look. This material of the registration holders is durable, wear resistant and waterproof. The insurance card holder for car has a clear window so you can easily see all the documents when you open it up.
- 🌷Compact Size: With the perfect size dimensions of 5.0in x 9.4in x 0.4in, this vehicle license and registration holder for car will fit into glove compartments, sun visors, door holders, consoles, etc. The glove box organizer is precisely designed to fit all of your car documents.
Drawbacks and risks to weigh
Premiums can strain a budget or rise
Premiums depend on factors such as age and policy design. The Administration for Community Living (ACL) notes that insurers may raise premiums if the assumptions used to price a policy prove wrong. Ask the insurer for its history of rate increases and the options available if the premium becomes unaffordable. A benefit that looks attractive today is not useful if you cannot maintain the policy.
Limits and claim rules can leave a gap
A policy may cap the daily or monthly benefit, limit how long it pays, require an elimination period before benefits begin, exclude certain services, or impose claim requirements. Actual care costs can exceed the benefit. Find out how the elimination period is counted and how the policy calculates benefits; the contract, not the headline benefit amount, determines what it pays.
Rank #3
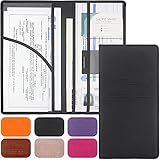
- 💼 CAR ORGANIZER PRACTICALITY: Car registration and insurance holder has multi-function clear compartments which can organize various items very well. The car document holder large pocket for insurance documents and 2 pockets for vehicle registration, 3 small pockets for driver's license, ID cards, AAA cards, business cards, receipt, key contact information cards, etc. It can fully meet your needs
- 👁EASY TO ACCESS AND READ: Car registration and insurance holder keeps your documents organized and keep them tidy and secured, which is stress-free to identify the documents in the folder and quickly reach the document when asked
- 🧲MAGNETIC CLOSURE DESIGN: The car insurance card holder is built with inner magnetic closure, which will keep your vehicle paperwork organizer closed to secure your vehicle documents from humidity and wear and tear. The car insurance holder is your first choice for protecting important car documents and certificates
- ✨PREMIUM MATERIAL: Car registration and insurance holder are made of high-quality PU leather and vinyl PVC. The beautiful cover of 3d embossing provides a comfortable soft touch feeling and professional look. This material is durable, Tolerant, and looks very naturally beautiful
- 💖SECURED & ASSURED: If you have any product problem when you use our car registration and insurance holder. Please feel free to contact us by email, we will do our best to offer a satisfactory solution for you within 24 hours
Inflation protection adds cost
A fixed benefit may buy less care as prices rise. Inflation protection can increase benefits over time, but it also increases premiums. The NAIC calls it “one of the most important features you can add to a long-term care insurance policy”; whether it is worth the additional cost depends on your circumstances and the policy’s terms.
Health may affect eligibility and price
Individual policies commonly involve medical underwriting. Poor health or already receiving care can lead to a higher rate, limited coverage, or rejection. Do not assume you will be able to buy the same coverage later if your health changes.
Rank #4

- PREMIUM: A fashionably slim, all-in-one design, the CoBak leather car document holder offers solid protection along with space for your essential documents. The case holder is handcrafted from premium-quality PU leather and present of luxurious lining.
- QUCIK ACCESS: This car document holder is a great way to keep all of your important documents together. Clear inner PVC pouches makes it easy to identify the papers or cards you need, with only one glance you will know exactly where the documents are when asked.
- MAGNETIC CLOSURE: Strong built-in magnets ensure the files and documents will be well protected and closed like a breeze.
- 6 COMPARMENTS: Comes with 3 large pockets for insurance documents, vehicle registrations cards and other valueable information. And 3 small pocket for driver's license, ID cards, business cards, key contact information cards.
- COMPACT SIZE: 9.5" x 5.1"(24cm x 13cm), slim profile and lightweight design, perfect size for any glove box or console compartment, ideal choice to protect your important documents. Also a great gift for yourself, lovers, friends and family.
You may never receive benefits
Traditional coverage is risk protection. If you never meet the policy’s claim requirements, you may receive no claim payment, even though the policy provided protection while it was in force. Consider whether that trade-off is acceptable alongside the premium and the possibility of future care needs.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.What to compare between policies
Compare written policy terms from several state-licensed insurers or agents. The NAIC cautions that “Policies from different insurance companies often have the same coverage and benefits but may not cost the same.” Compare the same assumptions and benefit design so the differences are meaningful.
Do these 3 things before closing this tab:
1Scan for outdated or missing drivers - takes under a minute2Repair Windows errors before they cause bigger problems3Fix the driver behind crashes, sound loss and screen glitchesBest Value

- Premium: The CoBak leather car document holder is handcrafted from premium-quality PU leather and present of luxurious lining
- Easy Access: Clear inner PVC pouches makes it easy to find the papers or cards with only one glance when asked
- Well Organized: The car document holder offers solid protection and space for your essential documents. It comes with 2 large pocket for car registration and insurance document and other information
- Compact Size: 5.4" x 5.3" (13.7cm x 13.4cm) , it is a perfect size for any glove box or console compartment
- Reliable and Durable: Meticulously constructed with top-tier quality materials, our product exudes reliability and durability, ensuring your purchase is a confident choice
| Compare | What to check |
|---|---|
| Premium and rate history | Current premium, how it may change, the insurer’s history of increases, and what options exist if you cannot keep paying. |
| Benefit amount and payment method | Daily or monthly maximum, whether payment is based on reimbursement or a cash-indemnity approach, and what documentation or expenses are required. |
| Duration and total benefit | How long benefits can be paid and the policy’s aggregate maximum, if stated. |
| Elimination period | How long you must wait before benefits start and how the period is counted. |
| Care settings and services | Whether home care, adult day care, assisted living, and nursing-home care are covered, and the contract’s definitions for each. |
| Inflation protection | Available benefit-increase options, how they work, and their effect on premiums. |
| Eligibility, exclusions, and safeguards | Claim triggers, exclusions, and any nonforfeiture or reduced-benefit options if you stop paying premiums. |
| Insurer and state status | Whether the insurer is licensed in your state and information about its financial condition; check state-specific partnership rules if relevant. |
How to decide whether it fits your situation
- Estimate local care costs. Research costs where you expect to receive care, including home care, assisted living, and nursing-home care. National figures may not reflect your area.
- Decide what care you want to plan for. Consider which settings you would use and how much family support you expect or want. Use those preferences to assess which services a policy must cover.
- Compare several offers in writing. Ask state-licensed insurers or agents to specify premiums, benefit limits, claim triggers, exclusions, inflation options, and rate-increase history. Compare contracts, not just summaries or sales estimates.
- Check partnership rules directly with your state. Ask your state insurance department whether a program is available and verify that the specific policy qualifies before relying on any potential Medicaid asset disregard.
- Test affordability over time. Decide whether the premium remains manageable under plausible future household budgets, including the possibility of increases. Do not base the decision on the advertised benefit alone.
What the published figures can—and cannot—tell you
The NAIC reports HHS estimates that 70% of adults who survive to age 65 develop severe long-term-services needs before they die, and 48% receive some paid care over their lifetime. The NAIC page does not state the estimate’s year. These population estimates describe risk, not an individual’s likelihood of needing care or whether a particular policy is a good purchase.
ACL’s figures for 2007 describe a historical market, not current pricing: the average policy cost about $2,207 per year, covered 4.8 years of benefits excluding the 20% of buyers who elected lifetime coverage, had a $160 daily benefit, and included some automatic inflation protection. ACL’s page was last modified on February 18, 2020. These dated figures should not be used as today’s premium or as a guide to current policy design. The NAIC shopper guide, published in 2022, also gives illustrative premiums for specified ages and benefit designs and warns that an individual’s actual premium may differ.
Bottom line
Long-term care insurance may be worth considering if its covered settings match your care plans, its benefits meaningfully offset costs you could not comfortably absorb, and you can afford premiums over time. It may be a poor fit if the premium would compete with essential expenses, the contract’s limits leave too large a gap, or you are unlikely to maintain the policy. Base the decision on your own finances, health, state rules, and the contract—not on a single national statistic or a headline benefit.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.




