Free tools Windows power users keep installed
One-click scans. No signup required.
The Supreme Court has asked the Trump administration to weigh in on three disputes over whether federally chartered banks must pay interest on some mortgage-escrow balances when state law requires it. That invitation, issued October 5, 2026, is not a decision to hear the cases and does not resolve whether homeowners are entitled to interest. As of October 7, the Solicitor General’s position and the Court’s next step were still unknown.
What the Supreme Court’s request means
The Court invited the Solicitor General to file a brief stating the United States’ views in Cantero, Flagstar Bank v. Kivett, and Citizens Bank v. Conti. The request is sometimes called a “call for the views of the Solicitor General.” It gives the federal government an opportunity to address the legal questions before the justices decide what to do with the petitions.
CU Today reported on October 6, 2026, that the Court had not agreed to hear the cases. An invitation for the government’s views is not a grant of review, a ruling for either side, or a decision that the petitions will be considered together. The government’s eventual recommendation and the Court’s response had not been reported as of October 7.
Why mortgage-escrow interest is disputed
A mortgage-escrow account holds money collected from a borrower so a servicer or bank can pay bills such as property taxes and homeowners insurance. The legal dispute is whether federal banking law lets national banks disregard state laws requiring interest on qualifying escrow balances.
#1 Best Overall

- SPEAKS YOUR LANGUAGE: Keys clearly labeled in residential mortgage finance terms like Loan AMT, Int, Term, PMT. This industry-standard calculator is super easy to use on all realty financing matters from finding a loan that works for your client to considering trust deeds investments, or finding remaining balances or balloon payments and much more
- CONFIDENTLY AND EASILY SOLVES: All your clients' financial questions whether they are buyers, sellers, investors or renters. Increase your perceived professionalism as a new agent, experienced broker or seasoned loan officer. Close more home sales and impress your clients with fast, accurate answers to all their real estate finance questions
- DEDICATED BUYER QUALIFYING KEYS: Enter client's income, debt and expenses to pre-qualify them to only show properties they can afford. Include tax, insurance and mortgage insurance then compare loan options and payment solutions to give your client choices before they make an offer to buy
- FIGURE OUT THE RIGHT LOAN: At the press of a button for jumbo, conventional, FHA/VA, or even 80:10:10 or 80:15:5 combo loans; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices; easily perform what if loan or tvm calculations Find loan amount, term, interest or PITI or PI payments
- BECOME AN INVALUABLE RESOURCE: Reduce your clients' confusion and uncertainty; ensuring they are able to make a purchase offer; knowing they can afford the down payment; and determining which is the right loan for them. Date-math for listings and contracts too. Comes with a protective slide cover, quick reference guide, pocket User's Guide, and long-life batteries
Federal law regulates aspects of escrow administration. The Second Circuit’s May 5, 2026, opinion notes that the Real Estate Settlement Procedures Act (RESPA) limits how much lenders may require borrowers to keep in escrow and requires a remaining balance to be returned after payoff, but does not generally require interest to be paid on escrow funds.
That means the dispute is not a rule that every mortgage escrow account must earn interest. A borrower’s entitlement can depend on the applicable state law, the account and institution involved, and later court or regulatory action. The cases concern how particular state requirements interact with federal banking law.
Rank #2

- DEDICATED FUNCTION KEYS for Quick Financial Solutions: Clearly labeled function keys enable you to quickly and confidently provide financial answers and options for your clients, whether in the office, in the car or at an open house. Compare loan options and provide payment solutions to give your client choices
- INSTANT FINANCIAL PROBLEM SOLVING: Solve the financial questions your clients have whether they are buyers, investors or renters; increase your perceived professionalism and close more home sales by quickly answering real estate finance problems including remaining balances
- RESIDENTIAL REAL ESTATE FINANCE TERMS: Keys labeled in residential real estate finance terms like Loan AMT, Int, Term, PMT; Calculator is super easy to use to determine a mortgage loan that works for your client
- VERSATILE LOAN CALCULATION OPTIONS: Calculate 80:10:10 or 80:15:5 combo loans at the press of a button; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices
- COMES COMPLETE: Comes with a protective slide cover, quick reference guide, pocket user's guide, two long-life batteries, and 1-year warranty
How the three Supreme Court petitions differ
| Case | State-law issue | What the current record establishes |
|---|---|---|
| Cantero | New York General Obligations Law § 5-601 requires covered mortgage-investing institutions to credit qualifying residential escrow accounts with at least 2% interest annually. | The Second Circuit held on remand that the requirement was preempted as applied to Bank of America. A petition is before the Supreme Court; the Court has not granted review. |
| Flagstar Bank v. Kivett | California Civil Code § 2954.8(a) addresses interest on mortgage-escrow funds. | The petition raises whether the National Bank Act preempts California’s requirement. The Ninth Circuit dispute is pending before the Supreme Court; the supplied case summary does not establish a Supreme Court ruling. |
| Citizens Bank v. Conti | Rhode Island is involved, according to CU Today’s October 6, 2026, report. | The Supreme Court invited the Solicitor General’s views on the petition. The available reporting does not specify the Rhode Island statutory requirement or establish that the Court granted review. |
The National Bank Act is central to the dispute over national banks: the question is whether a state requirement impermissibly interferes with powers federal law gives those banks. The California case summary frames the broader issue as whether the Act preempts state rules setting financial terms for federally chartered banks’ escrow accounts. The three petitions raise related questions, but the available sources do not establish that they have been consolidated.
What the Supreme Court decided in 2024—and what it did not
The Cantero litigation reached the Supreme Court after the Second Circuit initially found New York’s interest requirement preempted. In 2024, the Supreme Court vacated that decision and sent the case back because the appeals court had not compared the nature and degree of the state law’s practical interference with national-bank powers against the Court’s earlier preemption decisions. AP described the required review as a “nuanced analysis.”
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Rank #3

- Loan Amortization and Remaining Balances
- Instant Principal, Interest, Interest Only and Total Payments
- Future Values
- Date math function
The 2024 decision did not decide that New York’s law was valid or invalid. It supplied the approach the lower court had to apply on remand: assess the practical effect of the state requirement rather than rely on a categorical rule.
What happened on remand in the New York case
On May 5, 2026, a divided Second Circuit again held that New York’s two-percent requirement was preempted as applied to Bank of America. The majority reasoned that the law affected national banks’ mortgage-lending powers, constrained the terms of escrow accounts, and interfered with those powers to a degree comparable to state laws invalidated in earlier cases.
Rank #4

- PROFESSIONAL FINANCIAL CALCULATOR : Built-in TVM, IRR, NPV. Engineered for business analysts, real estate investors, accountants, and finance students.
- ADVANCED CASH FLOW & AMORTIZATION : Execute time value of money, break-even analysis, depreciation schedules, and bond pricing. Trusted for professional exam prep", MBA coursework, and banking certifications.
- CATIGA CF-300 : Flip-open hard case with a snap-close design for a secure fit. Compact and portable: designed for daily professional use in office, classroom, or on-site.
- ALL-IN-ONE FOR PROFESSIONALS : From NPV/IRR for real estate analysis to statistical calculations for business analysts. Handles probability, linear regression, and complex financial formulas.
- MORTGAGE, LOAN & INVESTMENT CALCULATOR : Covers bond pricing, loan amortization, investment analysis, and exam-level computations. Your go-to accounting calculator, business calculator, and real estate calculator in one device.
Judge Myrna Pérez dissented. She emphasized the Supreme Court’s warning against a categorical approach and argued for a different assessment of the law’s practical effects. Her dissent is a competing judicial view; the panel’s majority opinion is the Second Circuit’s holding.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.A separate lawsuit challenges OCC escrow rules
The Supreme Court petitions are distinct from a separate challenge to rules issued by the Office of the Comptroller of the Currency (OCC) in May 2026 concerning the discretion of national banks and federal savings associations over interest on escrow accounts.
Recommended Free Tools
Best Value
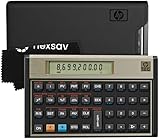
- HP 12C: INDUSTRY STANDARD SINCE 1981 – Trusted by professionals in real estate, banking, and finance for over 40 years. The HP 12C finance calculator remains the go-to tool for fast and accurate calculations in high-stakes business environments.
- 120+ FUNCTIONS FOR FINANCIAL ANALYSIS – Calculate loan amortization, bond pricing, mortgage payments, NPV, IRR, depreciation, and more with this large calculator. Built-in business and statistical functions allow you to perform complex calculations in just a few keystrokes.
- RPN ENTRY FOR FASTER WORKFLOWS – Reverse Polish Notation (RPN) allows for efficient data entry with fewer keystrokes and no formulas. This RPN calculator is perfect for a mortgage payment calculator, accounting calculator, business calculator, or real estate calculator for desktop.
- PROGRAMMABLE FOR REPEAT TASKS – The HP12C desk calculator stores custom keystroke sequences for repeated use. This large calculator supports up to 20 cash flows for IRR/NPV analysis, modeling investment scenarios, projecting returns, and automating routine calculations.
- INCLUDES CLEANING CLOTH, CASE & BATTERIES – Compact design fits easily on a desk or crowded table area. Includes a protective carrying case, cleaning cloth, and comes with pre-installed batteries so it's ready to use out of the box. A great choice for home finances, business professionals, and accountants.
On August 11, 2026, California’s attorney general announced that a coalition of ten states had sued in the U.S. District Court for the District of Oregon. The states allege that the rules exceed the OCC’s authority and improperly displace state consumer protections. Those are the states’ allegations, not a final judicial determination; the available announcement does not establish the outcome of the lawsuit.
What this could mean for homeowners
The invitation alone does not change what a bank pays, establish a homeowner’s right to interest, or resolve an individual account dispute. The Supreme Court has not ruled on the petitions, and the sources describing these cases do not establish a nationwide estimate of how many borrowers could be affected or how much any borrower might gain or lose.
Homeowner-side advocate Jonathan Taylor characterized the Supreme Court’s 2024 decision as vindicating Congress’ decision in Dodd-Frank to rein in aggressive preemption of state consumer-financial laws. That is an advocate’s interpretation of the decision, not a holding by the Court.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




