The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Parker-Hannifin and Honeywell are both diversified industrial companies with aerospace exposure, but they are not clean substitutes: their product mixes, reporting periods and corporate boundaries differ, and both have portfolio changes under way. Parker reported 6.6% organic sales growth and a 27.3% adjusted segment operating margin for FY2026. Honeywell reported 4% organic sales growth in Industrial Automation for Q2 2026. At the October 2, 2026 close, a third-party provider listed lower forward P/E for Honeywell than for Parker, but that snapshot alone cannot establish which stock is cheaper or the better value.
What do Parker-Hannifin and Honeywell sell?
Both companies sell engineered products and systems to industrial and aerospace customers, but their businesses span different markets. A comparison is most useful when it starts with what each company includes in its reported portfolio.
Parker-Hannifin
Parker’s FY2026 Form 10-K reports two segments: Diversified Industrial and Aerospace Systems. Parker describes a broad motion-and-control portfolio, including engineered solutions and aftermarket support for aerospace and defense, industrial equipment, transportation, off-highway, energy, and HVAC and refrigeration markets. That range makes Parker a diversified component and systems supplier, not a single-product aerospace peer.
Honeywell
Honeywell’s business perimeter has been changing. Its 2025 annual filing reported Aerospace Technologies, Industrial Automation, Building Automation, and Energy and Sustainability Solutions. Advanced Materials was spun off as Solstice Advanced Materials on October 30, 2025. A segment realignment took effect in the first quarter of 2026; Honeywell’s 2026 filing reports Aerospace Technologies, Building Automation, Process Automation and Technology, and Industrial Automation. The 2026 filing also describes a planned separation of Honeywell Aerospace.
#1 Best Overall

- Globally interchangeable with other manufacturer's couplings complying to ISO 7241 series B
- Multi-purpose coupling, widely used in varied applications
- Metal valve stop prevents flow checking to provide steady performance
- Brass couplers have double O-rings for redundant sealing and stainless steel locking balls for corrosion resistance
These segment lists describe different reporting periods, not two directly comparable snapshots. Honeywell’s 2025 categories should not be treated as its current segment structure, and figures that include Honeywell Aerospace should not be mixed casually with figures that exclude it.
What do the latest reported results show?
| Company and reporting period | Reported measure | How to interpret it |
|---|---|---|
| Parker-Hannifin, FY2026; year ended June 30, results released August 6, 2026 | Record sales; 6.6% organic sales growth; 27.3% adjusted segment operating margin | Company-reported FY results. The margin is adjusted and segment-level, not a consolidated GAAP margin. |
| Honeywell, Q2 2026 | Industrial Automation sales grew 4% organically | This is growth for one reported segment, not a directly equivalent measure of Parker’s company-wide organic growth. |
Honeywell’s Q2 2026 release defines its Honeywell Technologies results as excluding results attributable to Honeywell Aerospace and related perimeter adjustments. Use that perimeter when interpreting those results; it is not interchangeable with pre-separation consolidated Honeywell.
Rank #2
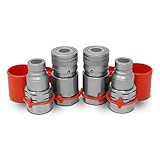
- 2 Sets, These Universal Quick Disconnect Coupler & Plug sets feature a new improved design for high flow performance and maximum service life.
- 1/2" NPT Thread, 1/2" Body, These flat face couplers interchange with most models of skid steers loaders including Bobcat Case / New Holland, Kubota, and many others
- Heavy Duty Design with 5076 PSI Rating - 23.78 GPM Max Flow Rate
- Locking sleeve helps prevent accidental disconnects
- Harden steel construction with anti-corrosive plating - Valve design allows for a minimal pressure drops and one hand operation
Honeywell’s 2025 Form 10-K reported a backlog of $37.475 billion at December 31, 2025, and said approximately 57% of remaining performance obligations were expected to be recognized as 2026 revenue. These are dated, company-specific figures, not a current backlog comparison with Parker.
Which portfolio changes could affect the comparison?
Parker’s pending acquisitions
Parker’s FY2027 guidance excludes its pending acquisitions of Filtration Group and CIRCOR’s Commercial and Defense Aerospace Business. Treat them as prospective portfolio additions, not as contributors to the guidance or FY2026 results.
Rank #3

- Globally interchangeable with other manufacturer's couplings complying to ISO 7241 series B
- Multi-purpose coupling, widely used in varied applications
- Steel nipples have a hardened body for strength and durability
- Metal valve stop prevents flow checking to provide steady performance
Honeywell’s spin-off and planned separation
Solstice’s spin-off is completed, so it affects the boundary of Honeywell’s continuing business relative to older filings. Honeywell’s planned separation of Honeywell Aerospace is a separate, prospective change; the 2026 filing describes it as planned, not completed. Honeywell’s 2025 filing also describes plans to realign certain industrial and energy-related businesses and to evaluate strategic alternatives for Productivity Solutions and Services and Warehouse and Workflow Solutions.
For an investor, these events matter because a change in the company boundary can alter reported sales, earnings, segment margins and valuation denominators even when the underlying operations have not changed in the same way. Compare results only after checking which businesses are included in each period.
Rank #4

- Globally interchangeable with other manufacturer's couplings complying to ISO 7241 series B
- Multi-purpose coupling, widely used in varied applications
- Metal valve stop prevents flow checking to provide steady performance
- Brass couplers have double O-rings for redundant sealing and stainless steel locking balls for corrosion resistance
How should investors compare growth, profitability and financial strength?
- Growth: Parker’s 6.6% FY2026 organic growth is a company-wide measure for its reported business, while Honeywell’s 4% Q2 2026 figure is for Industrial Automation. The periods and scopes differ, so the figures do not establish which company is growing faster overall.
- Margins: Parker’s 27.3% figure is an adjusted segment operating margin. Do not compare it as though it were a GAAP consolidated margin or assume it includes corporate costs on the same basis as another company’s reported margin. The cited Honeywell Q2 measure is sales growth, not a directly comparable margin figure.
- Cyclicality and mix: Both companies span multiple end markets, but their exposure differs. Consider the mix of industrial, building, process and aerospace activity, and check how acquisitions, divestitures and segment realignments affect each period.
- Cash generation and debt: A proper comparison would align operating cash flow, capital spending, debt, interest burden and acquisition funding to the same continuing-business perimeter. The reported figures here do not provide enough like-for-like balance-sheet and cash-flow information to rank the companies on financial strength.
What do the forward P/E figures say—and what do they leave out?
At the October 2, 2026 close, Stock Analysis listed forward P/E ratios of 27.38 for Parker and 23.37 for Honeywell. The same provider listed market capitalizations of about $122.7 billion and $67.8 billion, respectively. These are third-party market and estimate figures, not company-reported operating results; they can change with share prices, earnings estimates, share counts and provider methodology.
On that date, Honeywell’s listed forward P/E was lower. That is a snapshot of price relative to the provider’s forward earnings estimate, not proof that Honeywell is undervalued. It also does not mean Honeywell has the lower market capitalization because it is a better bargain: market capitalization reflects the company’s equity value and scale, not value relative to earnings.
Best Value
- Globally interchangeable with other manufacturer's couplings complying to ISO 7241 series B
- Multi-purpose coupling, widely used in varied applications
- Steel nipples have a hardened body for strength and durability
- Metal valve stop prevents flow checking to provide steady performance
Before drawing a valuation conclusion, align the share-price date, earnings period, diluted share count and net debt, and make sure both earnings figures cover comparable continuing businesses. Then compare forward P/E with measures such as enterprise value to EBITDA or free-cash-flow yield, and test normalized earnings rather than relying on one estimate. The companies’ different portfolios and ongoing corporate changes make that reconciliation especially important. The available figures do not establish a same-perimeter sum-of-the-parts value or a definitive intrinsic-value ranking.
What is the practical takeaway for an investor?
Parker’s reported FY2026 results show broad-based organic growth and a strong adjusted segment margin, while its next-year guidance excludes pending acquisitions. Honeywell’s Q2 2026 release shows organic growth in Industrial Automation, but its reported perimeter is shifting after the Solstice spin-off and ahead of a planned Honeywell Aerospace separation. The October 2 forward P/E snapshot favors Honeywell on that single ratio, but it is not enough to choose between the stocks. An investment comparison needs current, consistently defined earnings, debt and cash-flow figures for the businesses investors would actually own.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




