Free tools Windows power users keep installed
One-click scans. No signup required.
Strictly speaking, a Health Savings Account (HSA) is one specific U.S. tax-favored account—not a name for every way to set aside money for medical care. The main alternatives are health Flexible Spending Arrangements (FSAs), Health Reimbursement Arrangements (HRAs), and two narrower medical savings account types: Archer MSAs and Medicare Advantage MSAs. They differ in who funds them, who qualifies, and whether unused balances stay available.
For calendar year 2026, the HSA contribution limit is $4,400 for self-only HDHP coverage or $8,750 for family coverage. An HSA is not health insurance: eligibility generally depends on qualifying coverage and your full insurance and tax situation. IRS Publication 969 explains the federal rules.
How the five account types differ
The most useful distinction is whether you own an account, receive an employer benefit, or participate in a specific Medicare arrangement. A high-deductible health plan (HDHP) is insurance coverage; an HSA is a separate account that may be available to someone with qualifying coverage.
| Arrangement | Who funds it | Eligibility or context | What happens to unused money |
|---|---|---|---|
| HSA | The eligible individual, employer, or another person may contribute, within the annual limit. | Generally requires qualifying HDHP coverage, no disqualifying other coverage, no Medicare enrollment, and not being claimable as another taxpayer’s dependent. | Remains in the account, may earn tax-free interest or other earnings, and is portable when the owner changes jobs. |
| Health FSA | Usually employee salary reductions; the employer may also contribute. | Available through an employer plan. A general-purpose FSA can prevent HSA contributions, though limited-purpose or post-deductible designs may be compatible. | Generally subject to a use-it-or-lose-it rule; the plan may offer a carryover or grace period under federal rules. |
| HRA | The employer only; employees cannot contribute. | An employer-established reimbursement plan governed by its terms. Some designs may be integrated with individual insurance or Medicare under federal conditions. | Some plans allow carryforward, but the balance is not an individually owned account and cannot simply be refunded as cash. |
| Archer MSA | Eligible individual or employer, but not both for the same year. | Restricted to certain small-employer employees and self-employed people who meet requirements; new eligibility is generally limited under legacy rules. | Remains in the account and is portable. |
| Medicare Advantage MSA | Medicare makes deposits into the account. | For eligible Medicare participants enrolled in an approved Medicare Advantage MSA plan. | May earn interest or dividends; qualified medical distributions are not taxed. |
These are U.S. federal tax and benefits categories. Actual employer-plan terms and state or market availability can affect what is offered.
#1 Best Overall

- High-Quality Materials: Protect your files with ENGPOW fireproof accordion file organizer.It is made of 3-layered non-itchy silicone-coated fiberglass which withstand the temperature up to 2200℉.It has passed the UL94 -V0/5VA flame retardant test.Fireproof File Folder is fireproof&Water-resistant,which can effectively protect your important documents in a fire,flood,and wet weather. They will further keep your files intact.Giving you time to save your important documents when disaster strikes
- Accordion File Organizer: A Safe Enough Folder to Keep Your Files. Say goodbye to cluttered files and disorganization with ENGPOW's file organizer folders. Compared with other folders,our fireproof folders is allows you to neatly store and classify letter/A4 files, receipts, cards, USB drives, pen, passports and more in a safe and orderly way. Perfect for daily file filing and storage.The Non-dusty material can prevent dust from sticking to the outside of our folder,always keep it neat and tidy.
- Large Capacity: 14.2" x 10.4" x 2", Compared with other folders, our Accordian File Organizer adopts a multi-layer design that can meet all your storage needs.These include 13 accordion Pockets with labels(each expanding to 1.2 inches),1 zipper pocket,2 pen slot,6 card slots,4 small mesh bags,4 medium mesh bags,and 1 main pocket. You can securely store all your important documents and other items in this fireproof expanding file folder while effectively classifying and finding your files.
- Innovative Humanized Design: Design with a strong grab handle for carrying everything you needed easily. Featuring a double zipper for convenient opening and closing,you won't have to worry about losing any important documents. The included colorful labels make categorizing your files effortless. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place.
- Trusted after sales service: In the event of an emergency, our fireproof accordion file organizer folders are lighter, easier to carry than fireproof safes and quick to grab and go. We only wish to present the best to customers,to protect your valuables.If there any quality problem, please feel free to let us know.We promise to arrange a REPLACEMENT or 100% REFUND immediately. Ready to respond within a 24 hour time,your suggestion has a great impact on the upgrade of our products.
What makes an HSA different
Eligibility is about your whole coverage situation
Under the ordinary monthly rule, you generally must be covered by an HSA-qualified HDHP on the first day of a month, have no other disqualifying health coverage, not be enrolled in Medicare, and not be claimable as another taxpayer’s dependent to contribute for that month. A plan having a high deductible does not by itself establish that it qualifies. Confirm HSA compatibility with the insurer or employer.
Spouses cannot share one joint HSA. Each spouse who is eligible and wants an account must open a separate one. You can open an HSA through a qualified trustee, such as a bank or insurance company; it need not be the company providing your health plan.
Contributions and tax treatment
For calendar year 2026, the IRS sets an HSA contribution limit of $4,400 with self-only coverage and $8,750 with family coverage. The limit applies to total contributions from all sources; opening multiple HSAs does not multiply it. Eligible individuals age 55 or older may also qualify for a $1,000 catch-up contribution. The general contribution limits are set by the IRS in Revenue Procedure 2025-19; check current IRS instructions for how the catch-up rule applies to your circumstances.
Rank #2

- Fireproof & Waterproof Protection for Important Documents: Built with upgraded silicone fiberglass fabric that withstands temperatures up to 2200°F, main materials passed the UL94-V0/5VA flame retardant test, this fireproof document organizer shields your important documents, passports, and birth certificates from fire, water, and dust — giving you peace of mind when disaster strikes
- Multifunctional Folding Accordion Folder: Compared to other folders, our accordion file organizer features a multi-level partitioning design to meet all your storage needs. This accordion file organizer features 13 accordion pockets, a zippered pocket, an expandable pocket, 4 passport-sized bags, 6 card slots, and 4 USB slots — so you can sort documents, passports, credit cards, and USB drives into dedicated compartments and find what you need in seconds.
- Large File Folder with abels: Sized at14.6''×10.23''×1.6'', this expanding file folder holds Letter and A4 papers flat without folding. A-Z labels let you categorize files by project or document type, while the external pocket keeps your phone, pens, and ID cards within easy reach.
- Portable Home Office Safe Travel Storage: The sturdy handle and double zipper make this document organizer easy to grab and go — whether you're heading to the office, packing for a trip, or storing it in your home safe. Double zipper closure keeps every pocket securely sealed, so papers stay in place even when the folder is carried upright or packed in a bag. It's slim enough to fit in a backpack or closet, keeping your important papers organized and within reach.
- Complete Customer Support: During urgent situations, our fireproof accordion file folders outperform bulky fire safes — lightweight, highly portable, and ready for instant grab‑and‑go access. Tamfile is committed to researching fireproof products, just to bring you good products and excellent customer experience. If you have any questions, please contact us and we will try our best to solve your problem
Subject to eligibility, limits, and proper use, individual HSA contributions are generally deductible even if you do not itemize, employer contributions may be excluded from income, account earnings are tax-free while held, and distributions for qualified medical expenses may be tax-free. The IRS describes an HSA as “portable”: it stays with you if you change employers or leave the workforce.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →2026 HDHP thresholds and rule changes
For calendar year 2026, the IRS minimum deductible for HSA-qualified HDHP coverage is $1,700 for self-only coverage and $3,400 for family coverage. The maximum out-of-pocket limit is $8,500 for self-only coverage and $17,000 for family coverage; these limits exclude premiums. The deductible and out-of-pocket figures are coverage thresholds, not amounts you contribute to the HSA.
Two changes affect HSA compatibility. Treasury and IRS guidance published December 9, 2025 says pre-deductible telehealth and other remote-care services are permanently allowed without disqualifying HSA contribution eligibility for plan years beginning on or after January 1, 2025. Beginning January 1, 2026, bronze and catastrophic plans offered through an Exchange are treated as HSA-compatible even when they do not meet the general HDHP definition. This does not remove the other eligibility rules or establish that every plan in every market is available or suitable; confirm the coverage-year and state-specific plan terms. See the IRS announcement.
Rank #3

- Get Organization in Style: This elegant folder with attractive color schemes definitely adds a pop to your workspace! Go for our folder with pleasant colors to brighten up your space and give a little flare to your life.
- Made to Last: Reinforced plastic folders withstand tearing, flexible to stretch but firm enough to keep from getting deformed and creased. Snap closure increases its ease of use and access yet prevents your papers from slipping out.
- Effortless Organization: This expanding file folder makes sorting and organizing your papers a breeze. 8 expandable pockets with tabs allow you to sort by subject or task. Sticky labels for easy labeling and tracking, enhancing your document organization and retrieval efficiency.
- Larger Capacity: This accordion folder with the expandable spine design is more stretchy to fit over 250 sheets without bulking up too much. Unlike regular spines that can easily get dented, our spine is made for quality and not easy to deform in transit.
- Portable & Lightweight: 13 x 9.5 inches. Fit A4/letter size. Convenient size to carry around. An alternative for a binder to fit perfectly in your backpack without making it bulky. Easily take your paperwork to a meeting or school.
The last-month rule has a condition
If you qualify under the IRS last-month rule by being eligible on the first day of the final month of the tax year, you may be able to contribute the full-year amount. A testing period applies afterward. If you lose eligibility during that period, the amount that would not otherwise have been contributed is generally included in income and subject to an additional 10% tax, with exceptions such as death or disability. It is not an unconditional way to claim a full-year contribution limit.
How an FSA works—and when it can conflict with an HSA
A health FSA is an employer plan, usually elected at the beginning of the plan year and funded through payroll salary reductions. During the coverage period, the full elected reimbursement amount is generally available even before all the planned payroll deductions have been taken. Self-employed people generally cannot participate in an employer health FSA.
Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Repair Windows errors before they cause bigger problemsFix Now →Scan for outdated or missing drivers - takes under a minuteDriver Scan →A general-purpose health FSA can make you ineligible to contribute to an HSA, even if you also have HDHP coverage. Limited-purpose FSAs, which typically cover eligible dental and vision expenses, and post-deductible FSAs may be designed to coexist with an HSA; check the plan documents rather than assuming compatibility.
Rank #4
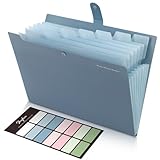
- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
For tax years beginning in 2025, IRS Publication 969 lists a $3,300 salary-reduction limit and a maximum permitted FSA carryover of $660. Those are 2025 figures, not a 2026 limit. An employer may offer no carryover or a smaller one. Instead, a plan may allow a grace period of up to 2½ months after the plan year; a health FSA cannot offer both a carryover and a grace period. The plan determines whether either option is available.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.How an HRA differs from an account you own
An HRA is an employer-funded reimbursement benefit, not an account employees fund themselves. The employer sets the contribution or reimbursement terms and covered expenses within applicable rules. Some HRA plans permit unused amounts to carry forward; others do not. A remaining balance cannot simply be paid to the employee as cash.
An individual coverage HRA is one possible design. IRS materials say federal rules finalized in 2019 permit certain HRAs to be integrated with individual health insurance or Medicare if specified conditions are met. This remains an employer plan, not a consumer-owned account. The IRS’s HRA overview describes these arrangements.
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Scan for outdated or missing drivers - takes under a minute3Clear out junk files and repair common Windows errorsBest Value

- Size: 13 x 10 x 0.7 inches. Fits A4 and letter-size paper, standard documents and filing needs.
- User-Friendly Features: Included sticker labels allow you to easily distinguish between different categories of files, maintaining neatness and enhancing productivity!
- Sleek and Portable: Designed to slip seamlessly into backpacks, laptop bags, or file cabinets, our lightweight folder keeps your documents tidy and accessible wherever you go.
- Built to Last: Crafted from polypropylene, our folders resist tears and deformation while remaining flexible. The secure snap closure offers easy access while keeping your papers securely in place.
- Versatile Utility: This folder isn't limited to organizing course papers for college students; it's perfect for storing business tax documents, recipes, important receipts, and more!
Why Archer MSAs and Medicare Advantage MSAs are narrower options
Archer MSAs
Archer MSAs are a legacy category, not a broadly available alternative to HSAs. Eligibility is generally limited to certain small-employer employees and self-employed people who meet the requirements. IRS Publication 969 says new eligibility is restricted after 2007, subject to exceptions for some existing participants or qualifying employer coverage. For the same year, an eligible person and employer cannot both contribute to the Archer MSA.
Medicare Advantage MSAs
A Medicare Advantage MSA combines a Medicare-approved high-deductible plan with a medical savings account. It is available only to eligible people enrolled in Medicare who choose an approved plan, and Medicare—not the individual or employer—makes deposits. It is not an HSA. HSA contributions generally stop after Medicare enrollment, although an existing HSA balance remains available for qualified expenses.
What counts as a qualified medical expense
Tax rules and, for employer arrangements, plan terms determine which expenses qualify. In general, the IRS describes medical expenses as costs for diagnosis, cure, mitigation, treatment, or prevention of disease, or for affecting a body function. An expense that is merely beneficial to general health generally does not qualify. You cannot claim a tax-free reimbursement and also deduct the same expense.
- Dental, eye, and physical examinations can qualify as diagnostic medical expenses.
- Therapy for a diagnosed mental illness can qualify; marital counseling does not under the IRS example.
- Nutritional counseling or a weight-loss program generally qualifies only when it treats a specific disease diagnosed by a physician.
- A gym membership is generally not eligible just because it supports general health. Narrower exceptions may apply when it treats a diagnosed disease or affects body structure or function.
- Nonprescription over-the-counter medicines and menstrual care products may qualify under IRS guidance.
For expenses whose eligibility depends on diagnosis, documentation, or the plan’s terms, keep receipts and confirm with the administrator or a tax adviser. The IRS’s medical expenses FAQ gives examples involving wellness and nutrition.
Choosing the right arrangement
Start with the coverage or benefit you can actually access, then compare ownership and balance rules. An HSA may suit an eligible person who wants a portable balance for current or future qualified expenses. An FSA is an employer benefit with election deadlines and a balance rule to check. An HRA is determined by the employer’s reimbursement design. Archer MSAs and Medicare Advantage MSAs apply only in narrower circumstances.
Quick Recap
- Check the plan: Ask the insurer or employer whether the coverage is HSA-qualified for the applicable year, and review any other coverage that could affect eligibility.
- Confirm the account terms: For an HSA, compare trustee fees, investment options, minimum balances, and transfer policies; these are provider-specific, not tax rules. The account trustee can differ from the health plan provider.
- Read employer plan documents: For an FSA or HRA, check eligible expenses, election timing, carryover or grace-period terms, and whether the arrangement is compatible with HSA contributions.
- Keep records: Retain expense documentation and ensure each reimbursement is for an eligible expense that has not already been reimbursed or deducted.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




