The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →The best short-term business financing depends on how you’ll repay it: a term loan delivers a lump sum, a line of credit lets you draw as needed, invoice factoring advances money against unpaid invoices, and a merchant cash advance is repaid from sales. NerdWallet’s 2026 comparison lists five options across those structures: Bluevine, AltLINE, Fora Financial, Giggle Finance and Fundbox. Its published limits and minimum credit scores are comparison-page figures, not live offers or approval guarantees; confirm current terms and state availability with each provider before applying.
Five short-term business financing options to compare
These five selections represent different financing structures and use cases, rather than a ranking based on verified current prices. The figures below are those reported in NerdWallet’s 2026 page, “Best Short-Term Business Loans of 2026 | 7 Picks.” They have not been independently verified as current lender offers. The comparison information summarized here does not state each provider’s APR, fees, funding speed, payment cadence, collateral requirements or personal-guarantee terms.
| Provider | Product type | Potential fit | Reported maximum amount | Reported term | Reported minimum credit score |
|---|---|---|---|---|---|
| Bluevine | Line of credit | Businesses managing recurring or fluctuating cash needs | $200,000 | Up to 12 months | 625 |
| AltLINE | Invoice factoring | Businesses with unpaid invoices and customers likely to pay | $5 million | 3 months | 300 |
| Fora Financial | Online term loan | Businesses seeking a lump sum for a defined near-term expense | $1.5 million | 18 months | 570 |
| Giggle Finance | Merchant cash advance | Businesses considering sales-based repayment | $15,000 | 6 months | 300 |
| Fundbox | Line of credit | Businesses that want revolving access to funds | $250,000 | Up to 24 months | 600 |
“Maximum” does not mean an applicant will qualify for that amount or term. Underwriting, product availability and terms can depend on the business, its location and the lender’s current policies. A low reported minimum credit score also does not establish that credit score alone is enough to qualify.
Which financing structure fits your cash need?
Term loan: a lump sum with scheduled repayment
A term loan can suit a one-time expense with a clear amount and payoff plan, such as buying inventory ahead of a selling season or covering an unexpected repair. You receive a lump sum and repay it over a fixed period. Short-term business loans commonly use frequent installments, so check the payment amount and timing against the cash your business actually brings in.
#1 Best Overall

- Profitability calculations; cash flow function Calculates NPV and IRR for uneven cash flows
- Time-value-of-money and Amortization keys solve problems including: pension calculations, loans, mortgages, etc.
- Ideal calculator for students, managers and statisticians
- Built-in functionality : List-based one- and two-variable statistics with four regression options: linear, logarithmic, exponential and power
- The BA II Plus calculator is approved for use on the following professional exams: Chartered Financial Analyst exam. GARP Financial Risk Manager (FRM) exam. Certified Management Accountants exam
Line of credit: draw funds when needed
A line of credit can help with uneven cash flow because you draw funds as needs arise rather than taking the full amount at once. It may be useful for recurring working-capital gaps, but compare the cost of each draw, any fees, repayment rules and whether repaid funds become available to borrow again.
Invoice factoring: advance against receivables
With factoring, a provider advances money against unpaid invoices in exchange for a fee. It is not a conventional term loan: the fit and economics depend on your invoices and your customers’ payment behavior. Understand who collects from customers, what happens if an invoice is paid late or disputed, and whether the agreement creates obligations beyond the advance and fee.
Rank #2

- PROFESSIONAL FINANCIAL CALCULATOR : Built-in TVM, IRR, NPV. Engineered for business analysts, real estate investors, accountants, and finance students.
- ADVANCED CASH FLOW & AMORTIZATION : Execute time value of money, break-even analysis, depreciation schedules, and bond pricing. Trusted for professional exam prep", MBA coursework, and banking certifications.
- CATIGA CF-300 : Flip-open hard case with a snap-close design for a secure fit. Compact and portable: designed for daily professional use in office, classroom, or on-site.
- ALL-IN-ONE FOR PROFESSIONALS : From NPV/IRR for real estate analysis to statistical calculations for business analysts. Handles probability, linear regression, and complex financial formulas.
- MORTGAGE, LOAN & INVESTMENT CALCULATOR : Covers bond pricing, loan amortization, investment analysis, and exam-level computations. Your go-to accounting calculator, business calculator, and real estate calculator in one device.
Merchant cash advance: repayment tied to sales
A merchant cash advance is sales-based financing, not a standard loan with fixed monthly installments. Providers may collect a percentage of sales or revenue through automatic account withdrawals or card transactions. Repayments that vary with sales can still strain cash flow, and a high total cost can make the advance expensive even when the payment percentage appears manageable.
How to compare the real cost and risk
Do not choose on advertised speed, an introductory rate or a factor rate alone. NerdWallet’s 2026 comparison gives a broad 14%–99% APR range for short-term loans; this is a comparison-level range, not a quote or prediction for an individual business. It also reports an average short-term loan amount of $77,904 and says 65% of approved borrowers in its 2026 Business Loan Study needed funds for working capital. Those figures describe the study, not what your business should borrow.
Recommended Free Tools
Rank #3

- Extra large 12-digit angled display.
- Loan Wizard.
- Automatic Tax Keys.
- Selectable decimal setting.
- Input any three loan variables to compute the fourth.
- Ask for the full repayment picture. Get the amount delivered to your business, every fee, the total dollars to be repaid, the payment amount and schedule, and any amount withheld from the advance.
- Normalize the price. If the offer uses a factor rate or simple-interest method, ask the provider for the APR and the assumptions behind it. Include fees and the actual repayment schedule when comparing offers. If an APR cannot be provided or meaningfully compared, use the total repayment amount and timing to make the trade-off explicit.
- Test payments against cash flow. Map daily, weekly or monthly payments to expected receipts, including a slower-sales scenario. Frequent fixed payments can become difficult during a seasonal dip; sales-based collections can still reduce the cash available to run the business.
- Check obligations and exit terms. Ask about collateral, personal guarantees, prepayment penalties, grace periods, default consequences, and any circumstances in which the lender can demand full repayment. Find out whether early payoff actually reduces the total cost.
- Compare more than one offer. Ask each lender the same questions and compare on the same borrowing amount and expected payoff date where possible.
The SBA recommends asking lenders about rates, minimum credit score, cash-flow requirements, prepayment penalties, grace periods and whether the lender may demand full repayment. The Federal Reserve Banks’ 2026 Report on Employer Firms, based on the 2025 Small Business Credit Survey, found that 60% of borrowers from online lenders said their actual borrowing costs were higher than expected, versus 37% of small-bank borrowers and 32% of large-bank borrowers. These are survey responses from borrowers in that study, not a forecast of an individual offer.
When an SBA-backed option may be worth checking
SBA 7(a) financing
The SBA 7(a) program can support short- or long-term working capital and other eligible business needs. It should not be treated as interchangeable with an online short-term loan: terms vary, and most 7(a) term loans are repaid monthly from business cash flow. The SBA’s Working Capital Pilot is a monitored line of credit for eligible financing needs. The agency says potential users may include businesses with at least a year of operating history and timely financial statements, receivables and payables aging, and inventory reports.
Rank #4
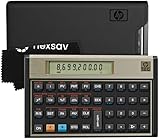
- HP 12C: INDUSTRY STANDARD SINCE 1981 – Trusted by professionals in real estate, banking, and finance for over 40 years. The HP 12C finance calculator remains the go-to tool for fast and accurate calculations in high-stakes business environments.
- 120+ FUNCTIONS FOR FINANCIAL ANALYSIS – Calculate loan amortization, bond pricing, mortgage payments, NPV, IRR, depreciation, and more with this large calculator. Built-in business and statistical functions allow you to perform complex calculations in just a few keystrokes.
- RPN ENTRY FOR FASTER WORKFLOWS – Reverse Polish Notation (RPN) allows for efficient data entry with fewer keystrokes and no formulas. This RPN calculator is perfect for a mortgage payment calculator, accounting calculator, business calculator, or real estate calculator for desktop.
- PROGRAMMABLE FOR REPEAT TASKS – The HP12C desk calculator stores custom keystroke sequences for repeated use. This large calculator supports up to 20 cash flows for IRR/NPV analysis, modeling investment scenarios, projecting returns, and automating routine calculations.
- INCLUDES CLEANING CLOTH, CASE & BATTERIES – Compact design fits easily on a desk or crowded table area. Includes a protective carrying case, cleaning cloth, and comes with pre-installed batteries so it's ready to use out of the box. A great choice for home finances, business professionals, and accountants.
SBA microloans
SBA microloans are made through approved intermediaries and can fund working capital, inventory, supplies, furniture, fixtures, machinery and equipment. The SBA says rates generally range from 8% to 13%, varying by intermediary, and the maximum permitted repayment term is seven years. They can be a smaller-dollar alternative, but that maximum term means a microloan is not automatically short-term financing.
SBA Lender Match
SBA Lender Match can help applicants find interested lenders, but a match is not a loan offer or an assurance of approval. The SBA says the service returns a summary of interested lenders two business days after a request and states: “No, using Lender Match doesn’t guarantee that you’ll get matched or be offered a loan.” Prepare the amount and purpose of the funding, credit history, financial projections, collateral details and a business plan if needed.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Repair Windows errors before they cause bigger problems3Scan for outdated or missing drivers - takes under a minuteBest Value

- HP 10BII+ FOR STUDENTS & PROFESSIONALS – This HP calculator is built for business, finance, accounting, and statistics courses. Perfect for learners and professionals who need to solve common financial problems quickly without memorizing formulas or relying on spreadsheets.
- 100+ FUNCTIONS FOR REAL WORLD MATH – Quickly solve time value of money, interest rates, loan payments, NPV, IRR, cash flows, and more. The 10bII+ also includes probability distributions for statistics courses—a feature not often found in financial calculators.
- ALGORITHMIC INPUT WITH DEDICATED KEYS – This high-school/college calculator uses algebraic and chain logic with minimal keystrokes. Layout appears the same as standard calculators for easy learning. Dedicated keys give quick access to commonly used financial and statistical functions
- APPROVED FOR MAJOR EXAMS – The HP 10bII+ algebra calculator is permitted for use on SAT, PSAT/NMSQT, and AP tests. An ideal statistics calculator and business calculator for school finance and accounting students preparing for class, coursework, or standardized exams.
- INCLUDES TRAVEL CASE, CLEANING CLOTH & BATTERIES– Slim, durable, and easy to keep on hand or store in a backpack or locker. Includes a protective case, cleaning cloth, and batteries so it’s ready out of the box. Large screen with clear contrast (non-backlit) is easy to read during exams or lectures.
Prepare before you apply
- Write down the amount you need and the specific use, such as inventory, payroll or covering a seasonal cash-flow gap.
- Estimate how and when the funds will be repaid, using a conservative sales forecast rather than an optimistic one.
- Gather business financial statements, projections and relevant receivables, payables or inventory records.
- Ask for written disclosures covering fees, total repayment, payment cadence, guarantees, collateral, prepayment and default terms.
- Confirm that the product is available in your state and that its repayment structure matches your expected cash flow.
Borrowing can address a short-lived gap, but a recurring shortfall may signal a deeper cash-flow problem that a new payment obligation will not solve. If the business cannot make the proposed payments under a realistic downside scenario, reconsider the amount, timing or financing structure before signing.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




