Card issuance is the process of making a payment-card account or credential available to a consumer or business. It connects financial institutions, payment networks, processors, issuing platforms, regulators, merchants and cardholders. Its impact is visible in everyday spending, business payments and access to credit—but the market cannot be understood from one headline number. Transaction counts, cards in circulation, factory shipments and processor volume measure different parts of the system.
Why card issuance still matters
Cards remain a major channel for noncash payments. In the United States, consumers and businesses made 236.6 billion noncash payments in 2024, according to the Federal Reserve Board’s initial findings from its 2025 triennial payments study released July 1, 2026. Cards accounted for more than three quarters of those payments by number.
The same release shows why payment mix needs careful interpretation: debit cards remained the majority of card payments, while credit-card payments grew faster than debit-card payments for the first time in almost a decade. The Federal Reserve also reported that ACH accounted for almost three quarters of noncash payment value. Card payment share by count and ACH share by value describe different dimensions of the market; neither is a complete measure of payment activity.
What “issuance” means—and who does what
Issuance begins when an eligible institution or sponsored program makes a card account or credential available to a customer. The credential may be physical, virtual or both.
Crashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minutePC Slower Than It Used to Be?
A free scan shows the junk files, broken settings and background clutter dragging Windows down - then fixes them in one click.Free scan · Windows 10 & 11Issuing institutions and sponsors
Banks and other eligible financial institutions commonly provide or sponsor the account relationship, underwriting, funding and compliance responsibilities. A fintech may design the customer experience while relying on a sponsor institution and specialized infrastructure.
#1 Best Overall

- QUICK ACCESS: Unlike traditional leather wallet, this mens slim wallet is equipped with the ejection mechanism. Simply press the side button on the card holder, all cards pop up at a step pattern that makes them very easy & convenient to take out.
- SLIM BODY, LARGE CAPACITY: This mens minimalist wallet holds up to 12+ cards. The aluminium chamber holds 6-8 and the leather flap holds 4-6 (1 ID window included). There are also removable money clips on the back capable of holding 15+ cash.
- CLEAR ID WINDOW: On the inside of the carbon fiber wallet, which has an ID card holder slot, which allows you to swipe the card without removing the card. It can be used to store ID card, work card, driver license, access card, traffic card, etc.
- RFID BLOCKING: This rfid wallet for men embeds a chip in the aluminum card case to block unknown scanning devices from scanning your credit cards, debit cards, and driver's licenses, maximizing the protection of your personal property.
- PERFECT PRESENT IDEA: This leather wallet is packaged in a beautiful premium box and it is great choice for men. It is a perfect credit card wallet for your friend, lover, parent or yourself on special Days.
Networks
Payment networks route authorization and clearing messages and establish network rules. A network is not automatically the issuer. The institution named on the account and the parties performing program and processing functions can be different.
Processors and issuing platforms
Processors and program platforms supply technology for authorization, ledgering, card production, fraud controls, compliance workflows and program management. Marqeta’s 2025 SEC filing, for example, describes consumer and commercial card issuing, transaction processing and card-program management.
Regulators
Regulators shape eligibility, disclosures, dispute rights, data handling, capital and consumer-protection obligations. The Consumer Financial Protection Bureau’s seventh biennial consumer credit-card market report, published December 30, 2025, examines the US consumer credit-card market as of the end of 2024, including promotional rates, transaction disputes, costs and credit availability.
Rank #2
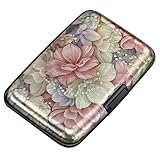
- This credit card holder is made of aluminum shells, ABS plastic frame and clasp closure, RFID-blocking will protect your card data from RFID scanners and readers.
- The size is 4.33 x 2.95 x 0.75 inches, Slim and small exterior design, are fit in your front pocket,suitable for travel and business carrying.
- Latches safely and securely when not in use. Rounded corner wouldn't damage on your clothes. With 7 accordion Slots, Capacity for up to more than 10 credit cards or more than 20 business cards.
- There are various patterns to choose from on the aluminum shell, including flowers, animals, and landscapes, to match your versatile style.
- This is an ideal gift that can express your thoughtfulness and kindness. Suitable for any day you want to express love on, such as Valentine's Day, birthdays, Mother's Day, etc.
What the latest regional figures show
| Measure | Geography and period | Reported result | What it measures |
|---|---|---|---|
| Noncash payments | United States, 2024 | 236.6 billion | Payment transactions across instruments |
| Card share of noncash payments | United States, 2024 | More than three quarters by number | Transaction count, not payment value |
| Noncash payments | Euro area, second half of 2025 | 83.5 billion | Six-month transaction count |
| Card share of noncash payments | Euro area, second half of 2025 | 57% by number | Transaction count |
| Cards in circulation | Euro area, end of second half of 2025 | 872.7 million, up 7.3% year over year | Cards outstanding at a point in time |
| Cards and chip modules shipped | Smart Payment Association members and advisory council members, 2025 | 2.47 billion | Association-member physical output; not global issuance |
The European Central Bank reported 32.9 billion contactless card payments in the euro area during the second half of 2025 and an average of 2.5 cards per inhabitant. “Cards in circulation” is a stock at period end, not the number issued during that half-year.
How issuance changes consumer finance
Access to credit
Issuing decisions determine who receives revolving credit, at what limit and on what terms. The CFPB’s consumer-market review covers consumers below prime, promotional interest rates, disputes and the cost and availability of credit. It is specifically a US consumer-credit-card analysis, not a measure of all debit, prepaid, commercial or international programs.
Payment choice and convenience
Debit, credit and prepaid cards place different funding sources behind a similar checkout experience. Contactless and virtual credentials can reduce friction, while controls such as spending limits, transaction alerts and card locks can give users more control.
Rank #3

- QUICK CARDS ACCESS: This minimalist wallet for men features a smooth pop-up mechanism. Just press the side button, and the cards slide out in a stepped layout for easy access.
- SLIM BODY WITH LARGE CAPACITY: Despite being slim at only 0.6 inches thick, this card wallet for men can hold 10-12 cards. The aluminum chamber holds 6-8 and the leather flap holds 4 (2 ID windows included). The money clip on the back holds 10+ bills.
- DOUBLE ID WINDOWS: KAFELLON designed the first pop up wallet on the market with 2 ID windows, based on real user needs. It's perfect for holding your ID and driver's license for quick access and quick view.
- RFID BLOCKING: This rfid blocking wallet features a built-in RFID-blocking layer that blocks unauthorized scans, protecting your finances and personal information.
- PERFECT GIFT IDEA: This money clip wallet combines a modern design with great practicality and comes with an elegant gift box. It's the perfect gift for men on Christmas, Valentine’s Day, Father’s Day, and other special occasions.
Risk and consumer protection
Issuers and their service providers must manage fraud, account takeover, chargebacks, unauthorized transactions and data security. Rules governing disclosures and disputes affect both the cost of programs and the remedies available to cardholders.
The Tool Desk
Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Why commercial and virtual cards are expanding
Businesses use commercial cards for employee expenses, procurement, travel, supplier payments and controlled disbursements. Mastercard’s 2025 SEC filing describes commercial credit, debit and prepaid products for corporations, midsize firms, small businesses and government entities. It also reports that its virtual-card technology was embedded in more than 10 global business-to-business and travel-and-expense platforms by the end of 2025.
Virtual cards can provide a number linked to a defined supplier, invoice, employee or spending rule without requiring a physical card. Visa’s FY2025 CEO message says, “We hold a leading share of about 40 percent in commercial card payments and are expanding into new use cases, like virtual cards for supplier payments and embedded finance for small businesses.” That is Visa’s reported company position, not an independently verified market total.
Rank #4
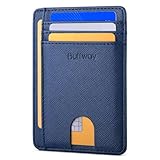
- STYLISHLY SMALL, SLIM & DISCREET: Measuring just 3 1/8" x 4 7/16", our RFID front pocket wallet is designed to be super thin and exceptionally slim. Its modern, minimalist profile fits perfectly in your pocket, purse, or travel pack without adding bulk.
- SURPRISINGLY SPACIOUS: Though slim, it features 8 slots to easily organize your essentials. Comfortably holds your driver's license, credit cards, debit cards, and membership cards, keeping everything you need right at your fingertips.
- ADVANCED RFID BLOCKING: Our slim wallets for men and women are outfitted with advanced RFID SECURE Technology. They block electronic signals to keep your identity protected while you travel, shop, or explore, safeguarding you from digital theft.
- DURABLE & STYLISH FAUX LEATHER: Crafted from premium synthetic leather, this minimalist wallet sleeve combines a luxurious look and feel with everyday functionality. Its durable construction is designed to withstand the rigors of daily use, travel, and shopping.
- THE PERFECT UNISEX GIFT: With its sleek design and practical security features, this wallet is a popular choice for both men and women. It arrives ready for gifting, making it an ideal present for the frequent traveler, minimalist, or anyone in your life!
Choosing an issuance model
Organizations evaluating a card program should compare the underlying design rather than assume one model is universally best.
Consumer, commercial or prepaid
- Consumer: optimized for personal spending, rewards, credit access or deposit-linked debit.
- Commercial: built around employee controls, accounting data, procurement and business cash flow.
- Prepaid: funded before use and often suited to controlled disbursements or specific-use programs.
Physical, virtual or dual credential
- Physical: useful where terminals, cash access or user expectations require a card.
- Virtual: useful for online, supplier and embedded-finance payments with granular controls.
- Dual: combines a physical card with virtual issuance for speed and flexibility.
In-house or platform-supported
- In-house: offers more direct control but requires substantial licensing, engineering, operations and compliance resources.
- Platform-supported: can shorten launch time and provide processing and program-management tools, while adding dependency on sponsors and vendors.
Available evidence does not establish like-for-like pricing or performance across these choices. The practical questions are who holds regulatory responsibility, how quickly credentials can be issued, which controls and APIs are available, how disputes are handled, and where data and funds are managed.
Free tools Windows power users keep installed
One-click scans. No signup required.
Keeping company metrics in perspective
Marqeta reported $382.5 billion in platform processing volume for 2025, compared with $291.1 billion in 2024. Those are Marqeta’s own operating metrics under its definition of total processing volume; they are not a count of cards issued or the size of the global card market.
Similarly, the Smart Payment Association’s 2.47 billion figure combines payment cards and chip modules shipped by its members and advisory council members in 2025. It excludes manufacturers outside that reporting population and cannot be compared directly with cards in circulation or payment transactions.
What the numbers cannot tell you
- There is no single authoritative figure here for newly issued cards worldwide across every issuer, region and card type.
- A payment count measures transactions, not unique cardholders or cards.
- Cards in circulation measure outstanding stock, including cards that may be inactive.
- Shipment data measures physical production for a defined association membership and includes chip modules in the cited figure.
- Processor volume measures one company’s activity and may include transactions processed for many programs.
- Company filings and shareholder messages describe what those companies report about their operations; they are not neutral market-wide estimates.
Bottom line for consumers and businesses
Card issuance remains foundational because it determines which payment credentials exist, who can use credit or controlled funds, and how transactions are authorized and protected. The strongest current evidence shows sustained card use in the United States and euro area, growth in euro-area cards in circulation, continuing physical-card and chip production, and expanding commercial and virtual-card capabilities. The responsible conclusion is not that one network, issuer or platform represents the whole market, but that issuance is a distributed infrastructure linking regulated account providers, networks, technology vendors and end users.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.




