Quick wins for a faster PC:
Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Scan for outdated or missing drivers - takes under a minuteDriver Scan →A mortgage is a loan used to buy a home or borrow against a home you already own; the home secures repayment, so missed payments can put it at risk. “Mortgage type” can refer to the loan program, repayment term, or interest-rate structure, and these dimensions can combine in one loan. To choose among offers, compare the same loan assumptions and look beyond the interest rate to fees, insurance, total housing costs, and your household budget.
What is a mortgage?
A mortgage is an agreement to borrow money for a home, with the property serving as collateral. The borrower promises to repay the loan with interest under the contract; if the borrower does not repay, the lender may have the right to take the property. The loan documents set out the repayment obligation and the lender’s security interest.
For a typical fully amortizing mortgage, scheduled principal-and-interest payments are designed to pay off the balance by the end of the term. Early payments generally devote a larger share to interest than later payments, as the balance declines. A servicer may also collect property taxes, homeowners insurance, or mortgage insurance with the payment, so the total amount due can be higher than principal and interest alone.
Mortgage types: three ways to classify a loan
Mortgage categories are not mutually exclusive. A loan can be conventional, have a 30-year term, and use a fixed rate, for example. Keep the program, term, and rate structure separate when comparing options.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
#1 Best Overall
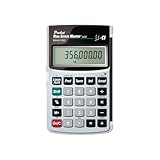
- Loan Amortization and Remaining Balances
- Instant Principal, Interest, Interest Only and Total Payments
- Future Values
- Date math function
| Classification | Common examples | What it tells you |
|---|---|---|
| Loan program | Conventional, FHA, VA, USDA, or local program | Eligibility rules, government backing or insurance, and potential fees |
| Repayment term | 15-year or 30-year | How long scheduled payments run; a longer term generally lowers monthly principal and interest but increases lifetime interest when other terms are comparable |
| Rate structure | Fixed-rate or adjustable-rate (ARM) | Whether the interest rate stays set or may change under the contract |
Loan programs: conventional, FHA, VA, USDA, and local options
Conventional loans
A conventional loan is not insured or guaranteed by FHA, VA, or USDA. Conventional loans may be conforming or non-conforming; conventional does not mean conforming. A conforming loan meets applicable standards for purchase by Fannie Mae or Freddie Mac, while a non-conforming loan does not. Borrowers with a down payment below 20% may have to pay private mortgage insurance (PMI), subject to the loan’s terms.
FHA loans
FHA loans are made by private lenders and insured by the Federal Housing Administration. They may allow lower down payments or lower credit scores than some alternatives, but eligibility, county-dependent loan limits, lender standards, and mortgage insurance requirements apply. A program’s minimum requirements are not a promise of approval.
VA loans
VA-backed loans are made by private lenders, with the Department of Veterans Affairs guaranteeing part of the loan. Eligibility depends on VA requirements and lender standards. A VA-backed purchase loan may offer no down payment when the sale price does not exceed the appraised value, and it does not require PMI. Check current eligibility, any funding fee, and the terms of the specific transaction.
Rank #2

- SPEAKS YOUR LANGUAGE: Keys clearly labeled in residential mortgage finance terms like Loan AMT, Int, Term, PMT. This industry-standard calculator is super easy to use on all realty financing matters from finding a loan that works for your client to considering trust deeds investments, or finding remaining balances or balloon payments and much more
- CONFIDENTLY AND EASILY SOLVES: All your clients' financial questions whether they are buyers, sellers, investors or renters. Increase your perceived professionalism as a new agent, experienced broker or seasoned loan officer. Close more home sales and impress your clients with fast, accurate answers to all their real estate finance questions
- DEDICATED BUYER QUALIFYING KEYS: Enter client's income, debt and expenses to pre-qualify them to only show properties they can afford. Include tax, insurance and mortgage insurance then compare loan options and payment solutions to give your client choices before they make an offer to buy
- FIGURE OUT THE RIGHT LOAN: At the press of a button for jumbo, conventional, FHA/VA, or even 80:10:10 or 80:15:5 combo loans; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices; easily perform what if loan or tvm calculations Find loan amount, term, interest or PITI or PI payments
- BECOME AN INVALUABLE RESOURCE: Reduce your clients' confusion and uncertainty; ensuring they are able to make a purchase offer; knowing they can afford the down payment; and determining which is the right loan for them. Date-math for listings and contracts too. Comes with a protective slide cover, quick reference guide, pocket User's Guide, and long-life batteries
USDA and local programs
USDA programs serve eligible rural borrowers, with qualification depending on the property’s location and other criteria. State and local housing agencies may also offer programs for particular borrowers or communities. Check official, current program resources before assuming a borrower or property qualifies.
Terms and interest rates: fixed versus adjustable
Repayment terms
Common term examples include 15 and 30 years, though other terms may be available. With the same loan amount and comparable rate assumptions, a shorter term generally means a higher scheduled monthly principal-and-interest payment and less interest over the full term. A longer term generally lowers that scheduled payment but gives interest more time to accrue.
Fixed-rate mortgages
With a fixed-rate mortgage, the interest rate and scheduled principal-and-interest payment stay set for the loan term. This makes those portions of the payment more predictable. The total housing payment can still change if taxes, homeowners insurance, or mortgage insurance changes.
Rank #3

- DEDICATED FUNCTION KEYS for Quick Financial Solutions: Clearly labeled function keys enable you to quickly and confidently provide financial answers and options for your clients, whether in the office, in the car or at an open house. Compare loan options and provide payment solutions to give your client choices
- INSTANT FINANCIAL PROBLEM SOLVING: Solve the financial questions your clients have whether they are buyers, investors or renters; increase your perceived professionalism and close more home sales by quickly answering real estate finance problems including remaining balances
- RESIDENTIAL REAL ESTATE FINANCE TERMS: Keys labeled in residential real estate finance terms like Loan AMT, Int, Term, PMT; Calculator is super easy to use to determine a mortgage loan that works for your client
- VERSATILE LOAN CALCULATION OPTIONS: Calculate 80:10:10 or 80:15:5 combo loans at the press of a button; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices
- COMES COMPLETE: Comes with a protective slide cover, quick reference guide, pocket user's guide, two long-life batteries, and 1-year warranty
Adjustable-rate mortgages (ARMs)
An ARM often starts with a fixed introductory period and then adjusts at intervals according to an index and the contract’s terms. Before choosing one, understand the initial fixed period, adjustment frequency, index, margin, caps, and possible payments at the first and later resets. A lower starting rate does not guarantee a lower lifetime cost, and payments can rise substantially.
Other contract features need particular care. Interest-only, negative-amortization, and balloon-payment loans can leave principal unpaid, increase the balance, or require a large later payment. Do not treat them as ordinary fully amortizing loans; read the terms and ask the lender how and when payments can change.
Free tools Windows power users keep installed
One-click scans. No signup required.
How to compare mortgage offers
Ask lenders to quote the same program, property assumptions, term, down payment, and rate structure so the offers are comparable. CFPB recommends reviewing official Loan Estimates. Compare the full cost and risks, not just the advertised interest rate.
Rank #4

- SPEAKS YOUR LANGUAGE: Keys clearly labeled in residential mortgage finance terms like Loan Amt, Int, Term, Pmt; this industry-standard calculator is super easy to use on all realty financing matters from finding a loan that works for your client to considering trust deeds investments, or finding remaining balances or balloon payments and more
- CONFIDENTLY AND EASILY SOLVE: Clients' financial questions whether they're buyers, sellers, investors or renters. Increase your perceived professionalism as a new agent, experienced broker or seasoned loan officer. Close more home sales and impress your clients with fast, accurate answers to all their real estate finance questions from PITI Payments to IRR, NPV and Cashflows
- DEDICATED BUYER QUALIFYING KEYS: Enter client's income, debt and expenses to pre-qualify them to only show properties they can afford. Include tax, insurance and mortgage insurance then compare loan options and payment solutions to give your client choices before they make an offer to buy
- FIGURE OUT THE RIGHT LOAN: For your client at the press of a button for jumbo, conventional, FHA/VA, or even 80:10:10 or 80:15:5 combo loans; check to see if ARMs or bi-weekly loans, quarterly payments or if interest-only payments are the answer; giving your client more choices; easily perform what if loan or TVM calculations find loan amount, term, interest or PITI or PI payments
- BECOME AN INVALUABLE RESOURCE: To your clients by reducing their confusion and uncertainty; ensuring they are able to make a purchase offer; knowing they can afford the down payment; and determining which is the right loan for them. Date-math for listings and contracts too. Comes with a protective slide cover, quick reference guide, pocket user's guide, and long-life battery
- Compare the interest rate and APR. APR includes the rate plus certain points, broker fees, and other charges, but it does not represent every cost of owning a home.
- Review discount points, lender credits, origination charges, appraisal and title costs, other closing costs, and estimated cash to close.
- Check mortgage insurance or program fees, when insurance may end, and whether costs are upfront, monthly, or both.
- Estimate the total monthly housing cost, including principal and interest, property taxes, homeowners insurance, and applicable mortgage insurance. Budget separately for costs such as HOA fees and maintenance.
- For an ARM, review adjustment dates, index, margin, caps, and the maximum payment exposure described in the contract.
- Look for prepayment penalties, balloon payments, interest-only periods, and negative-amortization features.
- Decide whether the payment fits your household budget. The amount a lender is willing to lend is not necessarily what you can comfortably afford.
Mortgage examples: compare like with like
These examples show how to structure a comparison without treating an unverified rate or payment as a quote. Request written Loan Estimates using the same borrower and property assumptions, then compare the actual terms.
| Example | What to compare | Reader takeaway |
|---|---|---|
| Same loan amount, 15-year versus 30-year fixed | Scheduled principal and interest, APR, points, fees, and total interest under each written offer | The shorter term generally has a higher scheduled payment and less lifetime interest when other assumptions are comparable; check whether that payment fits the budget. |
| Fixed-rate versus ARM | Starting rate and payment, adjustment schedule, index, margin, caps, and possible reset payments | Compare the ARM’s later payment exposure, not only its initial payment, with the fixed-rate offer. |
| Conventional versus FHA or VA, if eligible | Rate, APR, mortgage insurance or program fees, down payment, cash to close, and eligibility terms | A program’s suitability depends on the borrower, property, and actual offer; do not assume one option is universally cheaper. |
For each offer, keep principal and interest distinct from taxes, insurance, HOA costs, and maintenance. A lender’s approval is not a recommendation that the payment fits your household priorities or finances.
FAQ
What is the difference between a fixed-rate and adjustable-rate mortgage (ARM) loan?
A fixed-rate mortgage keeps its interest rate and scheduled principal-and-interest payment set for the term. An ARM may adjust after an introductory period under the contract, which can change the payment. Taxes and insurance may change either way.
Best Value

- Extra large 12-digit angled display.
- Loan Wizard.
- Automatic Tax Keys.
- Selectable decimal setting.
- Input any three loan variables to compute the fourth.
What is an FHA loan?
An FHA loan is made by a private lender and insured by the Federal Housing Administration. It has program rules and mortgage insurance requirements; approval depends on the borrower, property, and lender.
What is a conventional loan?
A conventional loan is not insured or guaranteed by FHA, VA, or USDA. It may be conforming or non-conforming, and a low down payment may mean PMI applies.
How much mortgage can I afford?
There is no single loan approval amount that determines what is comfortable for every household. Build a budget that includes the full housing payment, upfront cash needs, other expenses, and your priorities, then compare that budget with written offers.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




