Recommended Free Tools
For most people in the United States, the standard way to get a debit card is to open a checking account at a bank or credit union. You provide identity information, make any required opening deposit, wait for the institution to issue the card, then activate it and set a PIN. If you do not want a bank account, a reloadable prepaid card is a separate option that you fund before spending.
Get a debit card through a checking account
When you open a checking account at a bank or credit union, you usually receive a debit card, according to Consumer.gov. The card draws from money in that account when you make purchases or withdraw cash.
1. Compare checking accounts
Review the account’s current disclosures before applying. Compare:
- Monthly maintenance fees and ways to waive them
- Minimum opening deposit and minimum-balance rules
- In-network and out-of-network ATM access and fees
- Overdraft settings and fees
- Online and mobile-banking features, including alerts and card controls
- Branch availability and customer support
A bank or credit union may offer several checking products, so confirm that the account includes a debit card and ask when the card will be issued.
#1 Best Overall
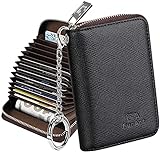
- Special Design: Multi-color optional and wear-proof classic business card holder looking.
- Plenty of Space: 16 card slots only measuring 4.1" x 3.0" x 1.1", including 13 credit card slots, 2 cash slots
- Protect Information Leakage: Prevents your vital information/cards from unnoticed scan with 2 outer layers RFID blocking materials.
- Extra Key Chain & Portable: Extra corns with key chain for your keys or lanyard. Portable use for shopping, traveling, etc.
- Great Gift: Practical compact wallet is the perfect gift. Give a thoughtful surprise to Men/Women on birthdays, holidays, celebrations, or any special occasion (e.g. Valentine's Day, Christmas, etc.).
2. Gather identification and personal information
Institutions commonly request your legal name, date of birth, physical address, Social Security number or Individual Taxpayer Identification Number (ITIN), and a government-issued photo ID. Acceptance rules differ by institution and account type; ask what documents are accepted before you start an application.
3. Submit the application
The Federal Deposit Insurance Corporation (FDIC) says you may apply in person, online, or through a mobile app. The institution may verify your identity and review its account-opening requirements before approving the account.
Rank #2

- 1:[Security Value set]: Ultimate premium identity theft protection sleeve set, made of aluminum foil waterproof materia, protect women,men’s credit cards,debit cards from electronic theft, fit into wallets and travel wallets. includes 12 rfid credit cards protectors in bright colors and 4 rfid passport protectors.
- 2:【Multi-Color, Lightweight Design】:Slim profile design fits easily into your wallet or purse without taking up extra space. these tiny slim RFID blocking sleeves ensures you will never be a victim of high-tech crime.Multiple colors, match your credit card with different color protectors, easy and quick to find the card you want.
- 3:【Safe and Durable】:Made from special RFID Aluminum foil material,High quality aluminum foil material can effectively shield electronic device scanning. Can effectively prevent card degaussing and theft brush, Rfid blocking sleeves envelopes for credit cards protect against scanning of digital and electronic chips by thieves to provide superior travel security.
- 4:【Suitable Size and Wide applicability】:credit card sleeves rfid blocking size : 91mm high / 3.58in, wide 63mm/ 2.48in, Passport Protector Size: 135mm high / 5.3in, wide 10.5mm/ 4.1in.Perfect fit credit cards, bank cards and passports with easy insertion.The ultra-thin design also fits perfectly into most women's and men's wallets. Bring safety and convenience to your life and travel.
- 5:【Perfect service】: Thank you very much for purchasing our products, To provide customers with satisfactory products and services is our eternal pursuit, at any time if you have any questions, please feel free to contact us, we are very happy to help you, and we will provide you with satisfactory service in 24 hours
4. Make the opening deposit and sign disclosures
Deposit requirements vary. A 2017 Consumer Financial Protection Bureau (CFPB) newcomer guide says an initial deposit is usually between $25 and $100 for a savings or checking account. Current FDIC GetBanked guidance notes that some accounts may open with as little as $25. These figures are examples, not a universal price; check the account’s current terms and payment methods.
Complete required agreements and disclosures, including documents describing fees, overdraft services, electronic transfers and privacy practices.
Rank #3
- Material: Genuine leather and PVC card slots.
- Size: 4.72"*3.15"*0.7" (12*8*1.8 CM)
- Large Capacity: The card holder has 26 cards slots. It is enough room for your ID card, credit cards, gift cards and dicounted cards. Small size is perfect to fit in your pockets or handbags.
- RFID Blocking: RFID Blocking designed lining keeps your vital information Secure. Be safe and protected from Electronic Pick pocketing.
- Great Gift Idea: Great gift for mother, daughter, grandmother and so on.
5. Receive, activate and secure the card
After the account is opened and the card arrives, follow the issuer’s activation instructions, which may use its app, website, phone system or an ATM. Set a PIN, enroll in online or mobile banking, and turn on transaction and card-use alerts. Review the first transactions promptly and report anything you do not recognize through the institution’s stated process.
Can you get a debit card without a bank account?
Yes, but the product is generally a reloadable prepaid card rather than a checking-account debit card. The CFPB explains that a prepaid card is not linked to a bank or credit-union account. You load money onto it before spending, and a reloadable card lets you add funds again later.
Rank #4

- Four-slot card holder: The card holder has three card slots for credit, debit or business cards, and a dedicated ID card slot
- RFID Blocking: Equipped with RFID blocking technology, it prevents unauthorized scanning of contactless cards, protecting your sensitive information from digital theft
- Thin and portable: Designed to be thin and portable, it is compact and can be easily put into a pocket or bag without adding bulk
- Long-lasting and Durable: Made of PU leather on the exterior, it is both durable and luxurious in appearance. The smooth surface protects the cards from scratches
- Fashion Design: Combining functionality and style, the stylish and simple appearance is suitable for various occasions, from business meetings to casual outings
Prepaid cards can help you limit spending to the amount loaded, but they are not automatically free or equivalent to a checking account. Read the cardholder agreement and fee disclosure before registering or loading money.
Checking-account debit card versus reloadable prepaid card
| Question | Checking-account debit card | Reloadable prepaid card |
|---|---|---|
| Linked to an account? | Yes, normally to a checking account at a bank or credit union. | No; the CFPB describes it as not linked to a bank or credit-union account. |
| How spending is funded | Uses the available balance in the checking account. | You load money before spending and may reload it later. |
| Potential fees | Account, ATM, overdraft or other fees depend on the institution. | May include monthly, transaction, ATM, cash-reload, customer-service, inactivity, paper-statement, decline, bill-payment, replacement, additional-card, foreign-transaction and cancellation fees. |
| Overdraft | A bank’s overdraft program may approve a purchase or ATM withdrawal above the available balance and charge a fee. | Generally limited to the amount available on the card, but review the specific agreement for any permitted negative balance or related fee. |
| Deposits and reloads | Money can be deposited into the checking account through the institution’s supported methods. | Reload options, locations and fees depend on the issuer and program. |
| Registration and protection | Account protections and error procedures depend on the bank or credit union and applicable law. | Registration may provide additional protections and is needed for FDIC or National Credit Union Administration (NCUA) insurance when the program offers it. |
How much does a debit card cost?
There is no reliable national average for debit-card fees, approval time or delivery time. The cost depends on the bank, credit union or prepaid-card program. A checking account may have a monthly fee, ATM charges, replacement-card charges or overdraft fees. A prepaid program may charge several types of usage, reload, service and replacement fees.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Best Value
- 【Durable Materials】: Our credit card organizer is made of water-resistant and wear-resistant PU, reinforced with sealed edges and durable PVC credit card sleeves. It is scratch-resistant and water-repellent, resistant to dust and sweat, and easy to clean. The edges of the credit card holder are reinforced to provide the advantages of wrinkle resistance and crack resistance.
- 【RFID Blocking】The credit card holder has an anti-shield lining, which can effectively block the electronic scanning instrument from illegally scanning the credit card in the card holder to protect the security of your RFID chip card.
- 【Easy to Find & Read】The internal translucent anti-magnetic PVC card page makes it easy for you to find and read card information and quickly find the card you need.
- 【Large capacity / Multipurpose】A total of 32 card slots, each card can hold 3 cards. A total of 96 card slots, fully meet your needs for card storage. You can hold your important customer business cards, credit cards, debit cards, ID cards, membership cards, VIP cards, invoices, receipts, etc. to prevent loss and damage.
- This is the best choice to keep your credit card and business card organized and easy to manage. Can be used to store credit cards or business cards that are important but not commonly used.
Ask for the complete fee schedule and identify charges that apply to your expected use: routine purchases, cash withdrawals, cash deposits or reloads, foreign transactions, replacement cards and customer-service calls. A card with no purchase fee can still be expensive if you frequently use out-of-network ATMs or reload cash.
How to reduce overdraft risk on a checking-account card
A checking-account debit card normally spends money already in the account. If you opt into or otherwise use a bank’s overdraft service, the bank may approve a transaction or ATM withdrawal above the available balance and then charge an overdraft fee. Ask the bank:
- Whether debit-card and ATM overdraft transactions are covered
- How to decline or opt out of the service
- Whether linked savings or other transfers can cover shortfalls
- When balances and pending transactions update
- What alerts can warn you before the balance is low
Use low-balance alerts and check pending transactions, since the displayed available balance may change as transactions post.
What to check before choosing a prepaid card
- Read the fee disclosure. Add monthly, transaction, ATM, reload, replacement and other applicable charges for your actual usage pattern.
- Confirm reload methods. Check whether you can add money by direct deposit, bank transfer, cash reload or another method, and whether each method has a fee or delay.
- Check registration rules. Find out what information is required, what protections depend on registration and whether the program states that funds are eligible for FDIC or NCUA insurance.
- Review error, loss and theft procedures. Learn how to report unauthorized activity, replace a card and dispute an error.
- Evaluate controls and access. Confirm the app’s alerts and lock features, ATM availability and any limits on purchases, withdrawals or reloads.
Questions to ask the institution
- What is the minimum opening deposit, and are there ongoing balance requirements?
- What monthly, ATM, replacement and foreign-transaction fees apply?
- How can I turn overdraft coverage off or limit it?
- Which identification documents and tax numbers do you accept?
- How do I activate the card and change the PIN?
- What should I do if the card is lost, stolen or used without authorization?
- For a prepaid program, when do insurance and other protections apply, and what registration is required?
Important limits on general advice
This guidance is U.S.-oriented. Eligibility, minimum deposits, fees, insurance, approval decisions and card-delivery times vary by provider and can change. No institution can be assumed to approve an application or provide a particular delivery date without checking its current terms.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




