The closest supported rate snapshot for August 11, 2025 is Bankrate’s end-of-July average: 8.25% for home equity loans and 8.26% for HELOCs. Those are not verified rates for August 11 itself. A national average is a benchmark, not a personal offer, and the right product depends on how you need the money and how you plan to repay it.
What were the average home equity rates?
Bankrate reported that, as of the end of July 2025, the average home equity loan rate was 8.25% and the average HELOC rate was 8.26%. The two averages were nearly even. The report does not verify daily averages for August 11, so these figures should be read as an end-of-July snapshot, not as rates confirmed for that date. Bankrate’s July 31, 2025 report
Rates offered to individual borrowers can differ because lenders consider creditworthiness, financial profile, underwriting, and product terms. The small gap between these national averages does not show which option will be cheaper for a particular borrower.
How HELOC and home equity loan rates differ
HELOCs: typically variable
A home equity line of credit is generally a revolving credit line with a variable rate tied to the prime rate. If prime falls, the rate on a variable-rate balance may fall too, although the change can take time to appear. Bankrate’s reporting says adjustments commonly show up within one or two statement cycles, but can sometimes take three months; the contract governs the timing. If a lender lets you convert part of a HELOC balance to a fixed rate, that converted portion will not respond to later rate changes in the same way.
#1 Best Overall

- ENTER DIMENSIONS JUST LIKE YOU SAY THEM: Input measurements directly in feet, inches, building fractions, decimals, yards and meters, including square areas and cubic volumes; one key instantly converts your measurements into all standard Imperial or metric math dimensions that work best for you and the project you are working on
- DEDICATED BUILDING FUNCTION KEYS: Make determining your project needs easy; just input project measurements, select material type like wallpaper, paint or tile; then calculate the quantity needed and total costs to avoid surprises at the homecenter checkout
- ACCURATE MATERIAL ESTIMATION: Helps you estimate material quantities and costs for your projects, ensuring you never buy too much or too little material; simplifies your home improvement and decorating jobs and cuts down on the number of trips to the hardware store
- PRECISE PAINT CALCULATIONS: Calculate exactly how much paint you need to ensure you finish the job without finding yourself with a half-painted room at night with a wet paint roller, and avoid storing or disposing of excess paint
- 11 BUILT-IN TILE SIZES: Make it easy to estimate the quantity needed to complete your project; simply calculate your square footage, then determine the tile required based on tile size and compare tile usage and costs by size; comes complete with hard cover, easy-to-follow user's guide, long-life battery and 1-year warranty
Home equity loans: typically fixed after origination
A home equity loan generally provides a lump sum at a fixed rate set when the loan is made. A later Federal Reserve rate move does not directly reprice an existing fixed-rate loan. Lenders may change rates on new offers as market conditions shift, but they need not do so at the same time or by the same amount.
Which product may fit how you borrow?
| Consideration | HELOC | Home equity loan |
|---|---|---|
| Access to money | Revolving access to funds, which can suit borrowing in stages. | A lump sum, which can suit a known, one-time expense. |
| Rate behavior | Typically variable and responsive to prime-rate changes, subject to account terms and timing. | Typically fixed once originated; later market changes do not directly alter the existing loan rate. |
| Repayment and payments | Depend on the credit line’s terms and how much is borrowed; check the contract for payment changes and repayment phases. | Repayment terms and payments are set by the loan agreement; compare the full schedule, not just the rate. |
| Fees and closing costs | Vary by lender and offer; review all charges and conditions. | Vary by lender and offer; review all charges and conditions. |
Compare actual offers rather than choosing from the national averages alone. Look at the annual percentage rate and fees, how and when payments can change, the repayment schedule, and the total amount you expect to pay. A lower advertised or introductory rate may not represent the cost over the full borrowing period.
Rank #2
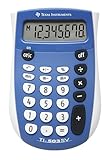
- Easy-to-read 8 digit display
- Large 7-millimeter display height
- Three key memory
- Switch key +/-
- Power saving LCD
What to check before borrowing
- Whether you need money all at once or expect to draw it over time.
- Whether you can manage payments if a variable HELOC rate rises, as well as how quickly a decrease would pass through under the account terms.
- All fees, closing costs, rate conditions, and repayment terms in the lender’s offer.
- Whether the projected total cost works for your budget and purpose.
Both products use your home as collateral. If you cannot repay, you could lose your home. Bankrate’s explanation of home equity borrowing risks
Quick Recap
Rank #4
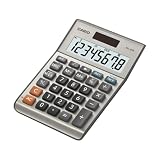
- LARGE EIGHT-DIGIT DISPLAY – Clear and easy-to-read 8-digit display, perfect for everyday calculations and ensuring accurate results in home or office settings.
- TAX & CURRENCY EXCHANGE FUNCTIONS – Effortlessly handle tax calculations and convert home currency to other currencies for easy financial management.
- GENERAL PURPOSE CALCULATOR – Ideal for a wide range of applications, from basic math to business and personal use, with memory keys for quick storage and recall.
- USER-FRIENDLY KEYBOARD – Easy-to-use layout, featuring square root, percent calculation, and simple functions that make it perfect for everyday tasks.
- COMPACT & PORTABLE DESIGN – Space-saving design that fits easily on any desk or in a briefcase, making it ideal for both home and office use.
Rank #3

- COMPACT & PORTABLE DESIGN – Space-saving design that fits easily on any desk or in a briefcase, making it ideal for both home and office use.
- LARGE EIGHT-DIGIT DISPLAY – Clear and easy-to-read 8-digit display, perfect for everyday calculations, ensuring accurate results in home or office settings.
- GENERAL PURPOSE CALCULATOR – Ideal for a wide range of applications, from basic math to business and personal use.
- DUAL POWER SOURCE: Operates on solar power with battery backup to ensure reliable use in any lighting condition.
- DURABLE HARD COVER: Built-in protective case shields the calculator from scratches, drops, and everyday wear.
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




