Free tools Windows power users keep installed
One-click scans. No signup required.
The debt-service coverage ratio (DSCR) compares cash flow available for debt service with the debt service measured over the same period. To calculate it, divide the applicable cash-flow measure by the applicable debt-service amount; the lender’s rules or loan documents determine which inputs belong in that calculation. A result above 1.0 means the selected cash flow exceeds the selected debt service, but it does not guarantee loan approval or show that every other cash need is covered.
DSCR formula
DSCR = cash flow available for debt service ÷ total debt service

For example, a lender might use operating cash flow, EBITDA with specified adjustments, or another defined measure for a business. For a commercial property, the numerator may be net operating income or a lender’s underwritten net cash flow. Debt service generally includes scheduled principal and interest, but lender rules can affect which obligations and payment assumptions are included.
Do not assume that two reported DSCRs are directly comparable. Check the cash-flow definition, included debts, measurement period, amortization and interest-rate assumptions, and whether the ratio is historical, projected, or stressed.
Do these 3 things before closing this tab:
1Fix the driver behind crashes, sound loss and screen glitches2Clear out junk files and repair common Windows errors3Scan for outdated or missing drivers - takes under a minute#1 Best Overall

- Profitability calculations; cash flow function Calculates NPV and IRR for uneven cash flows
- Time-value-of-money and Amortization keys solve problems including: pension calculations, loans, mortgages, etc.
- Ideal calculator for students, managers and statisticians
- Built-in functionality : List-based one- and two-variable statistics with four regression options: linear, logarithmic, exponential and power
- The BA II Plus calculator is approved for use on the following professional exams: Chartered Financial Analyst exam. GARP Financial Risk Manager (FRM) exam. Certified Management Accountants exam
How to calculate DSCR
- Find the applicable cash-flow measure. Use the measure and adjustments specified by the lender or loan documents. For a property, distinguish net operating income from underwritten net cash flow. For a business, check how operating cash flow or EBITDA is adjusted.
- Identify the debt service being measured. Confirm which debts and required payments are included, and whether the calculation uses particular amortization or interest-rate assumptions.
- Match the periods. Compare cash flow and debt service over the same period. Do not divide monthly cash flow by annual debt service.
- Divide cash flow by debt service. The result is the coverage ratio for those selected inputs.
- Check the assumptions before comparing results. When reviewing another calculation or loan offer, compare its cash-flow measure, debt scope, period, and payment assumptions with yours.
Illustrative calculation
The U.S. Small Business Administration’s historical audit report 10-10 gives an illustrative calculation of $125,000 of cash flow available for debt service divided by $50,000 of annual debt service, producing 2.5x coverage. This is an example of the arithmetic, not a universal benchmark or approval standard. A spreadsheet or ordinary financial calculator can perform the division; neither determines which inputs a lender will accept.
What the result means
| DSCR result | What it says about the selected inputs | What it does not establish by itself |
|---|---|---|
| Below 1.0 | The selected cash flow is less than the selected debt service. | It does not, on its own, explain the cause of the shortfall or determine the lender’s decision. |
| 1.0 | The selected cash flow equals the selected debt service, leaving no measured cushion in this ratio. | It does not show that other cash needs are covered. |
| Above 1.0 | The selected cash flow exceeds the selected debt service. | It does not guarantee approval or prove there is enough cash after taxes, capital spending, distributions, or other needs not included in the calculation. |
DSCR is one input into credit analysis. Collateral, guarantors, liquidity, leverage, business risk, and other factors may also matter. A particular ratio should not be presented as a promise of financing.
Why DSCR methods differ
Business lending
Business lenders may begin with historical financial statements and cash flow, then apply adjustments under their own rules. EBITDA may be used with specified adjustments, but it should not automatically be treated as cash available for debt service. The SBA’s historical audit explains that adding back depreciation and amortization without accounting for working-capital movements can overstate available cash: receivables and inventory can absorb cash even when accounting profit plus noncash expenses appears sufficient.
Rank #2

- Solves time-value-of-money calculations such as annuities, mortgages, leases, savings, and more
- Performs cash-flow analysis for up to 32 uneven cash flows with up to 4-digit frequencies
- Calculates various financial functions: Net Future Value Net present Value Modified Internal Rate of Return Internal Rate of Return Modified Duration Payback Discounted Payback
- The Texas Instruments BAII Plus Professional features an Automatic Power Down (APD) function for extended battery life
- Prompted display guides you through financial calculations showing current variable and label. Ten-digit display
SBA requirements are date-sensitive. SBA lender resources identify SOP 50 10 8.1 as effective October 1, 2026, and list a technical-updates notice effective that date. Confirm the applicable program version and calculation requirements with the lender or current SBA materials; do not rely on an older threshold or formula as a universal current SBA rule.
Commercial multifamily property
Fannie Mae multifamily guidance illustrates a program-specific method using annualized underwritten net cash flow divided by annualized debt service. Its guidance addresses different loan structures, including amortizing and interest-only loans, and may include other debt or specified interest-rate assumptions. These are conventions for that program, not a definition that applies to every commercial property loan.
For any property calculation, establish whether the numerator is net operating income or lender-underwritten net cash flow, and whether the denominator includes only principal and interest or other obligations required by the lender.
Using DSCR to compare financing
DSCR can help borrowers and investors understand how selected cash flow compares with selected debt obligations. It may also be used in loan covenants or ongoing monitoring when the loan agreement provides for it. Before comparing borrowers, loan offers, or published ratios, check the following:
| Comparison point | What to verify |
|---|---|
| Cash flow | Which measure is used and what adjustments are made? |
| Debt service | Which debts and payments are included? |
| Period | Are cash flow and debt service measured over the same period? |
| Payment assumptions | What amortization and interest-rate assumptions apply? |
| Type of calculation | Is it historical, projected, or stressed? |
| Governing rules | Which program version, lender policy, or loan-document definition controls? |
FAQ
What is a good DSCR?
There is no single universal “good” DSCR in the research reviewed. Acceptability depends on the lender’s calculation rules, loan context, and other parts of the credit analysis. Ask the lender which definition and requirement apply to your financing.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREEClear out junk files and repair common Windows errorsFree Scan →Does a DSCR above 1.0 mean a loan will be approved?
No. It means only that the selected cash-flow measure exceeds the selected debt service. DSCR is one input into credit analysis, and a result above 1.0 is not a guarantee of approval or proof that all cash needs are covered.
Rank #4
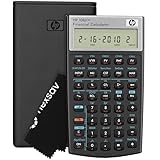
- HP 10BII+ FOR STUDENTS & PROFESSIONALS – This HP calculator is built for business, finance, accounting, and statistics courses. Perfect for learners and professionals who need to solve common financial problems quickly without memorizing formulas or relying on spreadsheets.
- 100+ FUNCTIONS FOR REAL WORLD MATH – Quickly solve time value of money, interest rates, loan payments, NPV, IRR, cash flows, and more. The 10bII+ also includes probability distributions for statistics courses—a feature not often found in financial calculators.
- ALGORITHMIC INPUT WITH DEDICATED KEYS – This high-school/college calculator uses algebraic and chain logic with minimal keystrokes. Layout appears the same as standard calculators for easy learning. Dedicated keys give quick access to commonly used financial and statistical functions
- APPROVED FOR MAJOR EXAMS – The HP 10bII+ algebra calculator is permitted for use on SAT, PSAT/NMSQT, and AP tests. An ideal statistics calculator and business calculator for school finance and accounting students preparing for class, coursework, or standardized exams.
- INCLUDES TRAVEL CASE, CLEANING CLOTH & BATTERIES– Slim, durable, and easy to keep on hand or store in a backpack or locker. Includes a protective case, cleaning cloth, and batteries so it’s ready out of the box. Large screen with clear contrast (non-backlit) is easy to read during exams or lectures.
What counts as debt service?
Debt service generally includes scheduled principal and interest, but the applicable lender rules or loan documents determine which debts, obligations, and payment assumptions are included. Confirm the definition instead of assuming every lender uses the same denominator.
Can I compare DSCRs from different lenders?
Only after checking that the calculations use comparable cash-flow definitions and adjustments, debt scope, periods, and interest-rate and amortization assumptions. Different inputs can produce different ratios for the same borrower or property.
What DSCR formula does the SBA currently require?
SBA lender resources identify SOP 50 10 8.1 as effective October 1, 2026, but the research reviewed did not inspect its full text. Confirm the version and requirement applicable to your application with your lender or current SBA source rather than relying on older material for a current universal formula or threshold.
Quick wins for a faster PC:
Repair Windows errors before they cause bigger problemsFix Now →Fix the driver behind crashes, sound loss and screen glitchesFind Drivers →Clear out junk files and repair common Windows errorsFree Scan →Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




