Do these 3 things before closing this tab:
1Clear out junk files and repair common Windows errors2Fix the driver behind crashes, sound loss and screen glitches3Repair Windows errors before they cause bigger problemsIn MVV Builders v Commissioner of Central Excise and Service Tax, CESTAT Hyderabad held that service tax under the residential-complex service category was not payable on the builder’s own construction services rendered before 1 July 2010. It also rejected Revenue’s challenge to allowing the Works Contract Composition Scheme during recomputation, excluded specified individual buyer contracts to complete unfinished flats, rejected the extended limitation period, and set aside penalties. The Tribunal did not determine a final amount payable: it remitted the matter for calculation of any tax and interest remaining under those directions.
What CESTAT decided in MVV Builders
The cross-appeals concerned residential-complex construction by MVV Builders during financial years 2007–08 through 2011–12 and a demand raised under Works Contract Service. In its order pronounced on 25 November 2025, CESTAT Hyderabad allowed the assessee’s appeal in part and dismissed Revenue’s appeal. Its directions removed several bases for the demand but required the Commissioner to recompute any surviving tax and interest.
- Tax was set aside for residential construction services rendered before 1 July 2010.
- Revenue’s objection to allowing the Works Contract Composition Scheme during adjudication and recomputation was rejected.
- Tax within the otherwise applicable period was set aside for the specified contracts with individual buyers to complete and finish unfinished flats.
- The extended limitation period was not available on the record; any otherwise surviving demand was confined to the normal period.
- Penalties were set aside, while applicable interest on any surviving tax remained payable.
The decision is fact-specific. It does not establish that every builder, every construction arrangement, or every historical service-tax demand has the same outcome.
How the dispute reached the Tribunal
The show-cause notice dated 28 September 2012 demanded ₹5,10,81,932 for 2007–08 to 2011–12 under Works Contract Services. The original adjudication confirmed the full demand and an equal penalty. After an earlier Tribunal remand, the revised Order-in-Original dated 14 March 2014 allowed the composition scheme, confirmed ₹1,60,75,412, and dropped ₹3,50,06,520.
#1 Best Overall

- Valued Carpenter Pencil Set: You will get 2 pcs solid carpenter pencils with 26 piece 2.8 mm refills, 1 replaceable sharpener, 1 plastic storage box.The complete carpenter pencils combination allows you to finish your work faster and more easily
- Deep Hole Marker Pencil: The deep-hole construction pencils adopts 45mm elongated tip design, which is more convenient to mark in the small hole or in other tight areas that other carpenter markers cannot reach
- Carpenter Pencils with Sharpener: The sharpener is screwed into the top of the work pencil, which won't get lost either. Built-in pencil sharpener that keep the lead with pointed and smooth to Improves line of sight in fine work
- Stronger Solid Lead: This work pencil is matched with a 2.8 mm thick lead , which is much thicker and stronger during the drawing process of construction work, it will not break or damage easily
- Marks on Various Surfaces: 3 colors solid construction pencil can marks on various surfaces,such as metal, plastic, wood, paper etc. Ideals for woodworkers, contractors, craftsmen, builders, merchants and masons
MVV Builders appealed the confirmed portion, while Revenue appealed the dropped portion. Those figures describe the stages of the dispute; they are not the final tax amount after the 2025 order. CESTAT’s later directions require a fresh computation, and the order does not state the amount that will be due after that exercise.
Why the pre-1 July 2010 demand was set aside
The Tribunal considered the version of section 65(105)(zzzh) of the Finance Act, 1994 applicable to the residential-complex service category. It noted that the explanation treating specified builder construction as a service to a buyer took effect on 1 July 2010. For the period before that statutory change, it treated construction by a builder on its own project as self-service rather than a service provided to another person.
“Before this amendment, such service was only self service because the builder was constructing his own building and hence service was not provided to any other person.”
Rank #2
Sale DEWALT 20V MAX Cordless Drill and Impact Driver, Power Tool Combo Kit , Includes 2 Batteries, Charger and Bag (DCK240C2)
- Ergonomically Designed: Work in tight areas with a compact design that gets into tough spots
- Compact and Lightweight: Both tools are designed to fit into difficult to reach spaces. The 1/4" impact driver has a length of 5.55 in. and weighs just 2.8 lbs, while the 1/2" drill/driver measures only 7.5 in. and weighs 3.6 lbs
- Both the DEWALT impact driver and electric drill driver feature integrated LED work lights with a convenient 20-second delay, ensuring enhanced visibility in dimly lit or challenging work areas
- One-Handed Loading - Keep one hand free with a 1/4 in. hex chuck that accepts 1 in. bit tips
- Power drill cordless with 1/2" single sleeve ratcheting chuck provides tight bit gripping strength, making bit changes faster and more secure
This is the CESTAT Hyderabad Bench’s statement in paragraph 15 of the order pronounced on 25 November 2025. The Tribunal relied on prior decisions including Aditya Homes, Aditya Construction Company India, and Krishna Homes, and referred to CBEC Circular No. 108/2/2009-ST dated 29 January 2009.
The relevant distinction in the ruling is the date the service was rendered and the statutory rule then in force. The decision should not be reduced to a rule based only on when a buyer paid or when a completion certificate was issued. A dispute involving different contract terms, service dates, payment facts, or historical statutory provisions needs to be assessed on its own record.
Why the composition-scheme challenge failed
Revenue argued that Rule 3 of the Works Contract (Composition Scheme for payment of Service Tax) Rules, 2007 required MVV Builders to exercise its option earlier, so the scheme should not have been allowed during adjudication. CESTAT rejected that challenge, following Hyderabad coordinate-bench decisions in Pragati Edifice and NCC Ltd.
Rank #3

- 【Great Compatibility】This Katerk 1/4 inch hex shank bit holder is specifically designed for 1/4 inch hex shank drill bits. It's compatible with most 1/4 fast hex handles, hex sockets, various electric screwdrivers, and handheld screwdrivers. The bit holder makes it a valuable addition for any handyman.
- 【Secure and Safe】Built with a secure backup nut design, each drill bit holder securely locks onto your bits, ensuring they stay firmly in place. Additionally, our bit holder incorporates a high-quality steel ball rolling design that holds up to several kilograms of weight, ensuring your various drill bits don't fall off.
- 【Easy One-Handed Operation】The bit holder for impact driver allows you to change bits single-handedly, simplifying your workflow. Its multi-color design further allows for quick identification of the drill bit you need.
- 【Compact and Convenient】Thanks to its compact size, this 1/4 inch bit holder is easy to carry around. The bit holder allows for easy attachment to various tools, making this a convenient addition to your construction accessories. The Katerk bit holder is cast from high-quality alloy material, promising a long product lifespan. Despite its rugged strength, the bit holder remains lightweight, making it portable.
- 【Cool Christmas Gift For Men Stocking Stuffers】 This screwdriver bit holder, driver bit holder, impact bit holder, can be given as a gift to your loved one, especially for anyone involved in construction or electrical work. It's a must-have for stocking stuffers for men and women, tools gifts for dad, tech gadgets for men, gifts for dad, gifts for him, gifts for husband, gifts for boyfriend, cool gadgets for men, and cool gifts for dad.
In doing so, the Tribunal relied on the proposition from Pragati Edifice that an assessee could opt for the scheme during recomputation even if it had not opted earlier, with an opportunity to present its case. This resolves Revenue’s appeal on the composition issue in this case; it does not mean that scheme formalities are irrelevant in every dispute or that the order dispenses with an opportunity to address the method of recomputation.
How the individual buyer contracts were treated
The record described a two-stage arrangement: MVV Builders sold undivided shares of land together with semi-constructed houses, then entered separate contracts with individual buyers to complete and finish flats according to their requirements. Applying the version of section 65(91a) quoted in the order, CESTAT treated those individual completion contracts as outside the construction-of-residential-complex service because the definition excluded construction for personal use.
The Tribunal said the result did not turn on whether the buyer personally occupied the flat or let it, referring to the statutory explanation and Modi & Modi Constructions. The holding concerns the individual contracts and evidence described in this case. It should not be generalized to every agreement described as a finishing or completion contract without examining who contracted for the work, what work was performed, and the applicable statutory definition.
Rank #4

- Long Nib and Deep Hole Marker: Our mechanical carpenter pencil with 45mm nib is designed for easy marking of deep holes or narrow areas. These construction pencils are the great choice for woodworking tools, construction tools, carpenter tools, contractor tools, wood carpentry tools and architect tools
- Extra Refills in 2 Colors for Versatile Marking: The construction mechanical pencil comes with 12 extra 2.8mm refills, including 6 red and 6 black refills. The black refill is suitable for light surfaces, while the red wax is perfect for dark surfaces. Our carpenter mechanical pencil makes sure that you'll have an ample supply for extended use
- Built-in Sharpener: Our construction pencil comes with a built-in sharpener to ensure the mechanical pencil tip is always sharp and ready for use. Never buy an extra pencil sharpener again. A great tool for any woodworker pencil, contractor pencils. The refill can easily be extended or retracted with a simple click of the pencils mechanical, allowing you to work more efficiently and accurately
- Portable Clip Design: Our deep hole construction pencil features a portable clip design, easy to carry and attach to your pocket or tool box, so that you can keep the carpenter pencils mechanical close at hand, making it a convenient tool to have on the go. Great gifts choice for carpenters
- Stronger Pencil Lead: The black refills are made of lead, sturdy and smooth. The red refills are made of wax, clear and light. These marking pencils are much thicker and stronger than normal pencils during the marking process of construction work, suitable for various surfaces, such as glasses, metal, boards, floors, walls, furniture, etc. The written marks can be easily wiped with a wet paper towel when needed
Why the extended limitation period and penalties were rejected
The order describes the normal limitation period applicable to the dispute as 18 months and the extended period as five years where the specified statutory grounds are present. CESTAT found no basis on this record to invoke the extended period. It noted that ST-3 returns had been filed and that the department’s officer could scrutinize them and determine the classification.
As a result, any demand otherwise surviving the Tribunal’s other rulings was confined to the normal period, measured from the show-cause notice. The Tribunal also set aside all penalties under section 80. These conclusions depend on the record and the law applicable to the historical period; they are not a general ruling that filing a return always prevents extended limitation.
What happens next under the order
CESTAT remitted the matter to the Commissioner solely to compute tax and interest consistently with its findings. The computation must give effect to the exclusion of services rendered before 1 July 2010, the normal limitation boundary, and the treatment of the specified buyer completion contracts. Applicable interest remains on any tax that survives; penalties have been set aside.
Best Value
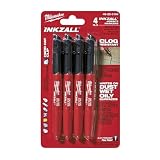
- Milwaukee Ink all Fine Point Marker, Black, 4 Per Pack
- 4 per pack Features Clog Resistant Marker Tip Writes through Dusty, Wet and Oily Surfaces Durable Marker Tip for Writing on Concrete, OSB and Rough Surfaces
- Clog resistant tip writes on dusty, wet and oily surfaces and is optimized for rough surfaces such as OSB, cinderblock and concrete
- Hard hat clip- attaches for easy access
- Quick dry time with reduced smearing and marking
The order therefore does not say that no tax can remain for every part of 2007–08 through 2011–12. Nor do the earlier confirmed and dropped amounts establish the final liability. That figure depends on the recomputation directed by the Tribunal.
How to assess whether the ruling is relevant to another dispute
A builder or recipient considering the decision should compare the case record against the distinctions CESTAT relied on, rather than relying on the headline outcome alone:
- Service date: identify when the relevant construction service was rendered and whether it was before or on or after 1 July 2010.
- Nature of arrangement: distinguish a builder’s construction of its own project from a separate contract with an individual buyer for completion or finishing.
- Statutory definition: examine the historical versions of sections 65(91a) and 65(105)(zzzh), including the personal-use exclusion and the amendment effective 1 July 2010.
- Composition option: check the applicable scheme rules, the history of any election, and whether the assessee had an opportunity to make its case during adjudication or recomputation.
- Limitation and evidence: review the show-cause-notice date, the normal-period calculation, filed ST-3 returns, and whether the record supports the statutory grounds for extended limitation.
The decision concerns historical service-tax provisions and a particular set of contracts and proceedings. Anyone applying it to a live matter should review the actual agreements, invoices, service and payment chronology, notices, returns, and governing statutory text with an Indian indirect-tax professional. The order’s outcome alone cannot establish whether a later appeal, stay, or subsequent contrary decision has affected it.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.




