Free tools Windows power users keep installed
One-click scans. No signup required.
“No tax on overtime” does not mean your entire overtime paycheck is tax-free. For tax years 2025 through 2028, eligible workers can claim a temporary federal income-tax deduction for qualified overtime compensation—generally the extra half-time premium required by the Fair Labor Standards Act (FLSA), not the full amount paid for overtime hours.
For example, if your regular rate is $20 per hour and you work 10 hours at time-and-a-half, you receive $300 in overtime wages: $200 for the regular-rate portion and $100 for the premium. The potential deduction is generally $100. Overtime still generally remains subject to federal income-tax withholding, Social Security, Medicare, and applicable state and local taxes.
This guide reflects the law and IRS guidance available as of August 10, 2026, including the rules for claiming the deduction on a 2025 return filed in 2026 and the separate reporting rules beginning with 2026 wages.
The short version
| Question | Answer |
|---|---|
| Is all overtime pay tax-free? | No. The law creates a federal income-tax deduction, not a complete tax exemption. |
| What amount generally qualifies? | The FLSA-required premium above the regular rate—usually the 0.5× portion of time-and-a-half pay. |
| When is it available? | Tax years 2025, 2026, 2027, and 2028. |
| What is the maximum deduction? | $12,500 for most returns or $25,000 combined for married filing jointly. |
| Do workers with income above $150,000 automatically lose it? | No. The deduction phases out based on modified adjusted gross income (MAGI). |
| Does it eliminate Social Security or Medicare tax? | No. |
| Must you itemize deductions? | No. It is claimed as an additional deduction through Schedule 1-A. |
| Does every worker who receives overtime qualify? | No. The overtime generally must be required under FLSA section 7, and the worker must be covered and nonexempt. |
The provision was enacted as section 70202 of Public Law 119-21, commonly known as the One, Big, Beautiful Bill Act, and added Internal Revenue Code section 225.
#1 Best Overall

- Comprehensive Tax Package Inclusions: The pack includes 1 all in one income tax organizer, 1 sheet of tax category pre printed label sticker, 1 common tax category list, 12 alphabet labels, giving you everything you need for tax preparation
- Build to last: Our tax record organizer is mainly made of plastic, waterproof, tear resistant, and resistant to deformation, while maintaining flexibility, secure button closure design facilitates access and placement of documents while ensuring safe placement of documents, and the closed bottom keeps the file in place
- Large capacity: This tax document organizer has 13 pockets, each holding about 40 sheets of paper, it can be flexibly expanded and shrunk as the number of files increases, holding a total of about 500 sheets of paper, ideal for organizing and protecting important documents, paperwork, bills, tax records, receipts, invoices and more
- Pre Printed Labels and Customizable labels: these pre printed label stickers have common tax categories, such as Medical Expenses, Employment Income, Rental Income, and more, we also included alphabet labels and customizable labels for your personal uses, please note that the customizable labels do not come with adhesive
- Broad uses: this expandable file folder organizer is proper for organizing various financial and tax related documents, with strippable labels and divider labels for sorting, making your tax preparation more systematic and managed, ideal for annual tax returns, document storage and filing, professional tax services, and tax agencies
What the overtime deduction actually covers
Section 225 allows an individual to deduct qualified overtime compensation received during the tax year. It applies to taxable years beginning after December 31, 2024, and ending before January 1, 2029—generally calendar-year tax years 2025 through 2028.
“Qualified overtime compensation” is tied to overtime required under section 7 of the FLSA. The qualifying amount is the portion paid above the employee’s FLSA regular rate. In the usual time-and-a-half arrangement, this is the additional half-time premium.
That distinction matters because an overtime paycheck usually contains two different amounts:
- Regular-rate portion: the employee’s ordinary compensation for the overtime hours.
- Overtime premium: the extra amount required because the hours qualified for FLSA overtime.
Only the second amount is generally eligible. The full overtime wages remain wages and are not removed from income simply because they were earned after 40 hours.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Key rule: The deduction is based on the FLSA-required premium, not whatever amount an employer, union contract, or state law happens to label “overtime.”
Does your overtime qualify? Use this decision path
- Were you an employee covered by the FLSA? The federal overtime rules apply only to covered employment relationships and covered work.
- Were you nonexempt? A worker who is exempt from FLSA overtime generally does not have qualified overtime for this deduction.
- Was the payment required under FLSA section 7? A premium provided only by state law, an employer policy, or a collective bargaining agreement may not qualify if the FLSA did not require it.
- Did you exceed the applicable FLSA overtime threshold? For most covered, nonexempt employees, that means more than 40 hours worked in a fixed seven-day workweek.
- What was your FLSA regular rate? It may be more complicated than your posted hourly wage.
- What portion was the federally required premium? Do not automatically use the full line on your pay stub labeled “OT.”
- Was the compensation received during the tax year? The year of payment controls, not necessarily the year in which the hours were worked.
- Can you support the amount? Use Form W-2 or applicable Form 1099 information, pay stubs, payroll reports, and other records.
- Do you satisfy the filing-status and Social Security number rules? Married taxpayers generally must file jointly, and the recipient must have a valid employment-authorized Social Security number.
- Do the annual limit and MAGI phaseout reduce the amount? Even eligible overtime can be limited or eliminated by these rules.
The IRS qualified-overtime FAQ explains that overtime paid to a worker who is not eligible for FLSA overtime does not become qualified merely because another law or agreement provides premium pay.
What “FLSA overtime” usually means
Under the general FLSA rule, a covered, nonexempt employee must receive at least 1.5 times the regular rate for hours worked over 40 in a fixed seven-day workweek. The workweek is the measuring period; employers generally cannot average 38 hours in one week with 42 hours in the next to avoid overtime.
Federal law generally does not require overtime merely because work occurs:
Recommended Free Tools
- on a Saturday or Sunday;
- on a holiday;
- at night; or
- for more than eight hours in a single day.
Those circumstances may trigger premium pay under state law, an employment contract, a union agreement, or company policy. But they do not automatically create qualified overtime under section 225. The Department of Labor’s overtime guidance and Fact Sheet #23 explain the general federal rules.
Some industries and public-sector jobs use different FLSA section 7 work periods or thresholds. Police and firefighters, for example, may be covered by special section 7(k) rules. Certain hospital and residential-care employees can also have special work-period calculations. Do not apply the ordinary 40-hour formula without checking the applicable category.
How to calculate the qualifying amount
Ordinary time-and-a-half overtime
Suppose you earn $20 per hour and work 10 qualifying overtime hours:
| Calculation | Amount |
|---|---|
| Regular-rate portion: $20 × 10 hours | $200 |
| FLSA premium: $20 × 0.5 × 10 hours | $100 |
| Total overtime wages: $20 × 1.5 × 10 hours | $300 |
| Potential qualified-overtime deduction | $100 |
If your payroll records show only the total amount paid for qualifying overtime hours at exactly 1.5 times the regular rate, the IRS method is generally:
Do these 3 things before closing this tab:
1Repair Windows errors before they cause bigger problems2Fix the driver behind crashes, sound loss and screen glitches3Clear out junk files and repair common Windows errorsQualified overtime = total time-and-a-half overtime pay ÷ 3
For example, $15,000 of total time-and-a-half overtime-hours pay produces a potential qualified amount of $5,000, before the annual cap and MAGI phaseout.
Rank #2

- Ultimate Fireproof & Water-Resistant Protection: Keep your valuables safe with our DocSafe Hard-Shell fireproof file organizer. It is made of thickened silicone coated fireproof heat insulated cotton material and hard-shell material which can stands up against fire and passed the UL94 -V0/5VA flame retardant test. Fireproof box is both fireproof and water-resistant, ensuring your documents stay protected during fires, floods, or wet weather. It may fit both letter and legal-size files
- Upgraded Hard-Shell Design Fireproof Box: Our fireproof document box combines hard-shell construction with fireproof materials, offering unmatched protection and durability. Unlike traditional soft case, our design withstands extreme conditions while maintaining a sleek, professional look. The Non-dusty material actively repels dust,hair and stains, keeping your box clean and tidy for years. It’s the ultimate solution for safeguarding your important documents, laptop, and valuables
- Large-capacity: Outside size: 15.5" x 11.5" x 3"(Thickness can be expanded up to 4"). Our Accordion fireproof document box adopts a multi-layer design that can meet all your storage needs. These include 13 accordion Pockets with labels,1 zipper pocket,4 pen slot,14 card slots,4 passport holder,4 small mesh bags,2 mesh bags,and 1 main pocket. It can store your important documents,money,passport,U Disk,cards,laptop,certificates in a safe and orderly way. Perfect for daily file filing and storage
- Fireproof File Organizer with Lock: Protect your valuables with the built-in high-quality combination lock (No keys required). Featuring a double metal zipper for convenient opening and closing. Design with a strong handle for carrying everything you needed easily. The fireproof file folder is suitable for business, travel, office, school, home storage, you can be 100% sure that your important documents are in a safe place. Of course, giving it as a gift to your family is also a good choice
- Trusted after sales service: Nothing is completely foolproof, but added protection is always a good idea. In an emergency, our fireproof document organizer ensures your files stay intact, giving you time to save your important documents. It is lighter, easier to carry than fireproof safes and quick to grab and go. If there any quality problem, please feel free to let us know. We are committed to solving your problem immediately, your suggestion has a great impact on the upgrade of our products
This shortcut works only when the entire amount represents time-and-a-half pay for qualifying FLSA overtime hours. It is not a universal rule for every payment labeled overtime.
Double time or pay above time-and-a-half
Employers may voluntarily pay double time or another premium higher than the FLSA minimum. The deduction generally covers only the premium needed to satisfy the federal 1.5× requirement—not the entire extra amount.
Windows Errors? Fix Them Before They Spread
Repair common Windows errors and clear accumulated junk for a smoother, more stable PC - no reinstall needed.Free scan · no reinstallCrashes, No Sound, or Screen Glitches?
Random freezes, missing sound and display glitches usually trace back to one bad driver. Find and replace yours safely.Free scan · under a minuteExample:
- Total double-time pay for qualifying overtime hours: $20,000
- Regular-rate portion: $10,000
- FLSA-required 1.5× amount: $15,000
- FLSA-required premium: $15,000 − $10,000 = $5,000
If the pay statement shows only the full 2× amount, $20,000 ÷ 4 is an approximation of the $5,000 qualifying premium. If the statement separately reports a premium calculated at the 2× rate, the IRS example converts that premium to the FLSA-required amount by dividing it by 2.
Any amount above the FLSA-required premium is generally not qualified overtime compensation under section 225.
When the regular rate is not simply your hourly wage
The FLSA regular rate can include more than a stated base wage. The Department of Labor explains in its regular-rate guidance that the calculation generally includes remuneration for employment except for specific statutory exclusions.
Depending on the facts, the regular rate may be affected by:
The Tool Desk
Outbyte Driver Updater FREEFix the driver behind crashes, sound loss and screen glitchesFind Drivers →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →- nondiscretionary bonuses;
- commissions;
- piece-rate compensation;
- multiple pay rates;
- special-rate or locality payments; and
- other compensation that belongs in the FLSA regular-rate calculation.
As a result, a calculation using only base hourly wage × 0.5 × overtime hours can understate the premium. IRS Notice 2025-69 allows an adjustment where a simple method would underestimate qualified overtime because the regular rate increased, such as after a nondiscretionary bonus.
Who can qualify—and who generally cannot
Hourly nonexempt employees
An hourly employee can potentially qualify if the employee is covered by the FLSA, is nonexempt, works hours beyond the applicable federal threshold, and receives the required premium.
Salaried workers
Salary status alone does not decide eligibility. A salaried worker who is nonexempt and receives FLSA-required overtime may potentially claim the deduction. A salaried worker who satisfies an FLSA exemption generally cannot claim qualified overtime for those payments.
Common white-collar exemption categories include qualifying executive, administrative, professional, outside-sales, and certain computer employees. Duties and compensation tests—not job titles alone—determine exempt status. See the Department of Labor’s Fact Sheet #17G for the general salary-basis rules.
Federal employees
Federal employees should check their FLSA classification on Standard Form 50. According to the IRS FAQ, an “N” generally indicates nonexempt and FLSA-overtime-eligible status, while an “E” generally indicates exempt status. The classification and the underlying pay records still control.
The Office of Personnel Management provides federal overtime calculation information in its guide to computing FLSA overtime pay.
Police, firefighters, hospital workers, and public employees
Special FLSA work periods can change the hours threshold and the way the premium is calculated. Police and firefighters may fall under section 7(k), while certain hospital and residential-care employees may use another permissible work period.
Some state and local government employees receive compensatory time instead of cash overtime. The IRS Notice 2025-69 example treats the cash value paid for qualifying compensatory time as potentially eligible in the year it is paid. Because the timing and calculation can be unusual, retain the employer’s records showing how the compensatory time was earned and paid.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Rank #3

- Great way to organize and store vital tax records
- Instruction sheet/checklist and preprinted labels included
- 12 pockets plus one large pocket in back provides ample storage
- Protective flap and elastic cord closure
- Contains 10% recycled content, 10% post-consumer material
Workers paid under state law or an agreement
State law may require overtime after eight hours in a day, or may require premium pay for weekends, holidays, or other conditions. A collective bargaining agreement or employer policy may provide similar benefits.
That payment is not automatically qualified for the federal deduction. The central question is whether the premium was required under FLSA section 7 and whether the worker was covered and nonexempt under the federal law.
People who receive Form 1099
A Form 1099 is a reporting form, not proof of either eligibility or ineligibility. A true independent contractor generally is not an FLSA employee and generally has no FLSA overtime entitlement. Do not treat gig-work, freelance, or contractor compensation as qualified merely because a payer calls it “overtime.”
At the same time, the IRS Schedule 1-A instructions contemplate that some qualifying compensation may be reported on Form 1099-NEC or Form 1099-MISC. The underlying legal relationship and the reason the premium was required must be examined carefully.
Annual limits and the MAGI phaseout
The maximum deduction is:
- $12,500 for most filing statuses;
- $25,000 for married taxpayers filing jointly.
The $25,000 joint limit is a combined household cap, not $25,000 per spouse.
The deduction is reduced when modified adjusted gross income exceeds:
- $150,000 for single, head-of-household, and qualifying-surviving-spouse filers;
- $300,000 for married filing jointly.
The reduction is generally $100 for each $1,000—or portion of $1,000—of MAGI above the applicable threshold. For this purpose, MAGI is generally AGI increased by income excluded under sections 911, 931, or 933.
| Situation | Effect before considering other limits |
|---|---|
| Single filer with $151,000 MAGI | Maximum deduction reduced by $100. |
| Single filer with $160,000 MAGI | Maximum deduction reduced by $1,000. |
| Joint filers with $310,000 MAGI | Maximum deduction reduced by $1,000. |
| Single filer with $160,000 MAGI and $10,000 qualified overtime | $9,000 approximate deduction after the $1,000 reduction. |
A taxpayer with the maximum $12,500 deduction reaches approximately zero at $275,000 of single-filer MAGI. A joint couple claiming the full $25,000 reaches approximately zero at $550,000 of MAGI. But a taxpayer with less than the maximum amount of qualified overtime can lose the entire deduction at a lower MAGI because the phaseout reduction is compared with the taxpayer’s actual qualifying amount.
Therefore, being above $150,000 or $300,000 does not automatically disqualify you. It starts a phaseout calculation.
How much can the deduction save?
A deduction reduces taxable income; it does not reduce tax dollar-for-dollar. The actual federal income-tax effect depends on your marginal tax rate, taxable income, filing status, other deductions, and credits.
| Qualified-overtime deduction | Illustrative marginal rate | Approximate federal income-tax reduction |
|---|---|---|
| $1,000 | 12% | $120 |
| $1,000 | 22% | $220 |
| $1,000 | 24% | $240 |
These are illustrations, not guaranteed refund amounts. A $1,000 deduction does not create a $1,000 refund, and a $100 qualified-overtime amount does not mean $100 of tax disappears. If the deduction lowers taxable income that would otherwise be taxed at 22%, its approximate value is $22.
Do not confuse the deduction with a credit. The deduction lowers the income on which tax is calculated. Your tax savings depend on the rate applied to that income.
How to claim the deduction for tax year 2025
For a 2025 return filed in 2026, use the 2025 version of Form 1040, Schedule 1-A, Additional Deductions. The qualified-overtime calculation appears in Part III.
- Confirm eligibility. Determine whether the work was covered, nonexempt FLSA employment and whether the premium was required under section 7.
- Separate the premium from the total overtime wages. For ordinary time-and-a-half pay, use the separately reported premium or, where appropriate, the IRS reasonable method of dividing the total qualifying overtime-hours pay by three.
- Confirm the payment year. Include compensation received in 2025, even if the hours were worked earlier. Do not include overtime earned in 2025 but paid in 2026.
- Match the compensation to reporting. Confirm that the total compensation is included on the applicable Form W-2, Form 1099-NEC, or Form 1099-MISC.
- Complete Schedule 1-A, Part III. For 2025, enter qualified overtime from Form W-2 compensation on line 14a and qualifying Form 1099-NEC or Form 1099-MISC compensation on line 14b. Line 14c combines the amounts.
- Apply the cap and phaseout. The schedule uses the $12,500 or $25,000 limit, MAGI, the applicable threshold, excess MAGI, the phaseout increment, and the resulting reduction. The final qualified-overtime deduction appears on line 21.
- Carry the result to Form 1040. The 2025 Form 1040 instructions direct the Schedule 1-A total to Form 1040 line 13b.
- Keep your support. Retain pay stubs, payroll reports, employer statements, calculations, and records showing the hours and regular rate.
The relevant forms are the 2025 Schedule 1-A and the 2025 Form 1040 Instructions.
Rank #4
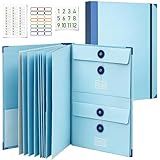
- Keep Important Family Records Together:Keep birth certificates, passports, insurance paperwork, medical records, tax documents, legal papers and other essential family records in one organized place instead of spreading them across drawers, cabinets and separate folders.
- 12 Sections for Different Document Sizes:Three vertical, three horizontal and six half-size sections give different types of paperwork their own space, making this document folder organizer easier to use for full-size papers, passports, certificates, cards and smaller records.
- Fits Standard Letter-Size Papers:Sized for standard 8.5 × 11 in documents, the full-size sections hold important papers while half-size sections provide convenient space for passports, certificates, cards and smaller records.
- Made for Important Life Events:Use this folder for important documents for estate planning, moving, emergency preparedness, insurance matters and other major life events, helping essential family information stay organized and easier to access when needed.
- Practical Home Filing for Everyday Records:Use this family document organizer for household paperwork, personal records, tax-season documents and frequently needed files. A practical home document organizer for keeping important information organized and easier to find throughout the year.
What if your 2025 W-2 does not separately identify qualified overtime?
That does not automatically prevent a claim. Employers and payors were not required to separately report qualified overtime on 2025 Forms W-2, 1099-NEC, or 1099-MISC. Some employers voluntarily used Form W-2 box 14 or supplied a separate statement, but many workers may need to calculate the amount from payroll records.
For tax year 2025, IRS Notice 2025-69 permits reasonable calculation methods using information such as:
- the regular rate paid or reasonably approximated;
- hours worked over the applicable FLSA threshold;
- employer-provided information;
- pay stubs and payroll records; and
- similar documentation.
A single pay stub may not show the complete annual amount or may combine straight-time and premium pay. Gather records for all relevant pay periods and document how you converted the reported wages into the FLSA-required premium.
What changes for 2026 through 2028?
For wages paid during tax year 2026, employers and payors must separately report qualified overtime using the updated reporting fields. The worker will use the applicable Schedule 1-A and instructions when filing in 2027.
| Information return | 2026 qualified-overtime field |
|---|---|
| Form W-2 | Box 12, code TT |
| Form 1099-MISC | Box 14 |
| Form 1099-NEC | Box 1d |
A Form W-2 issued in early 2027 reports wages paid during calendar year 2026. Do not confuse the form’s issue date with the tax year of the wages.
Separate reporting should make the calculation easier, but you should still compare the reported amount with your pay records. A code or box entry does not override the statutory requirement that the amount be FLSA-qualified.
What taxes still apply to overtime?
| Tax or charge | Does the deduction generally remove it? |
|---|---|
| Federal income-tax liability | Potentially reduced by the deduction. |
| Federal income-tax withholding | Usually still withheld through payroll unless withholding information is properly updated. |
| Social Security tax | No. |
| Medicare tax | No. |
| Additional Medicare Tax | No, if applicable. |
| State income tax | Depends on the state’s law. |
| Local income tax | Depends on the jurisdiction. |
For 2026, the employee Social Security tax rate is 6.2% up to the applicable wage base, and Medicare tax is 1.45% with no wage base. Additional Medicare Tax can apply at higher wage levels. The IRS 2026 Publication 15 explains these payroll-tax rules.
The deduction also does not automatically remove state or local income tax. States can conform to the federal Internal Revenue Code, decouple from it, or enact their own treatment. Check whether your state:
- conforms to section 225;
- has enacted a separate overtime deduction;
- starts its return from federal taxable income, federal AGI, or another base; and
- allows local tax treatment to follow the state treatment.
Because state laws can change, use your state’s 2025 or 2026 instructions rather than assuming that federal treatment applies. General reporting about possible differences is summarized by the Associated Press, but the controlling answer is your state’s law.
Withholding versus your final tax bill
Your employer generally does not stop treating overtime as taxable wages during payroll processing. Federal income-tax withholding may continue even though you expect to claim the deduction on your return.
For tax years beginning after 2025, the law directs Treasury to modify withholding procedures to account for the deduction. The IRS instructs employers to use an employee’s updated Form W-4 and the applicable withholding procedures if the employee wants payroll to reflect an expected deduction during the year.
- Do nothing: You may receive the benefit when you file your tax return, assuming you qualify.
- Update Form W-4: You may receive more take-home pay during the year, but an overly optimistic estimate can result in too little withholding and an unexpected balance due or underpayment issue.
Payroll systems will not necessarily adjust every worker’s overtime withholding automatically. Withholding is only a prepayment of tax; it is not the final tax calculation.
Independent reader supportYour contribution helps us test, update, and keep practical guides available for everyone.Timing: the year you receive the pay matters
The deduction is based on qualified overtime compensation received during the tax year. It is not necessarily based on when you worked the hours.
For example, if a pay period ends in December 2025 but the paycheck is issued on January 6, 2026, that overtime is not included in the taxpayer’s 2025 qualified-overtime amount. It belongs to the year in which it was paid under the IRS example in Notice 2025-69.
What’s actually slowing this PC down?
Pick the symptom - the matching free tool is one click away.
Best Value

- FIREPROOF & WATERPROOF DOCUMENT PROTECTION: Fully protect your files and keep them organized with Andyer fireproof accordion file organizer. It features 3 layers of silicone-coated fiberglass which withstand the temperature up to 2500℉ - Has passed global flammability standards and vertical burning tests(SGS UL94 V-1). With a waterproof silicone outer, to stop sprinklers, rain, and water damage
- SECURE COMBINATION LOCK FOR PRIVACY: This important document folder features a resettable 3-digit lock, The locked file organizer prevents unauthorized access to ID, sensitive contracts and financial documents. Our file folder organizer securely stores and organizes your important documents including letters/A4 documents, receipts, bills, USB drives, passports, invoices and more
- LARGE CAPACITY ALL-IN-ONE ORGANIZER: Efficiently organize and easily lookup all your papers in one place with our accordion folders. Featuring a multi-pocket, multi-layer design, you can flexibly organize everything and your papers won't wrinkle. Meets all your storage needs! Includes 13 folded pockets with labels, 1 zipper pocket, 2 pen slots, 6 card slots, 4 USB slots, 4 Passport-sized pockets and 1 main pocket
- INNOVATIVE HUMANIZED DESIGN: Compared with other document organizers, our fireproof expanding file folder comes with an extra front pockets (14.2 x 7.7 inches), which is perfect for storing cash, passports, letters, and other frequently used small items for easy access at any time! No need to open the whole bag to find your urgent needs
- PORTABLE & DURABLE FOR ALL OCCASIONS: Brightly colored tabs are included to make filing and retrieving documents simple. Designed with double zippers and sturdy handles, it's easy to carry and organize your important documents anytime and anywhere. Compared with safes, our important document organizers are lighter, more portable and quicker to grab and go. Perfect for business, travel, office, school, home storage
Pay particular attention to:
- biweekly payroll periods crossing December 31;
- paychecks issued after year-end;
- deferred compensation;
- compensatory-time payouts; and
- final paychecks after leaving a job.
Married couples and Social Security number rules
Married taxpayers generally must file a joint return to claim the deduction. Married filing separately does not qualify.
On a joint return, both spouses’ qualified overtime is combined, subject to one $25,000 household maximum. For example:
- Spouse A qualified overtime: $9,000
- Spouse B qualified overtime: $20,000
- Combined amount: $29,000
- Joint-return cap: $25,000
The recipient of qualified overtime must generally have a valid Social Security number issued for employment and include it on the return. The 2025 Form 1040 instructions state that the number generally must be issued by the Social Security Administration by the return’s due date, including extensions.
Do not assume that an Individual Taxpayer Identification Number (ITIN) satisfies this rule. A valid employment-authorized SSN, an ITIN, and an SSN issued too late to meet the return requirement are different situations. Review the current instructions or consult a tax professional if the taxpayer’s identification status is unusual.
Common overtime payments that do not automatically qualify
| Payment | Usually qualifies? | Reason |
|---|---|---|
| FLSA-required 0.5× premium for hours over the applicable threshold | Yes, potentially | It is the premium above the regular rate required by federal overtime law. |
| Full 1.5× overtime paycheck | No, not in full | Only the premium portion generally qualifies. |
| Pay above 1.5×, such as double time | Only partly, generally | Only the FLSA-required premium is generally eligible. |
| Saturday or Sunday premium | Usually no, by itself | Weekend work alone does not trigger federal overtime. |
| Holiday premium without qualifying FLSA hours | Usually no | Holiday pay is not automatically FLSA overtime. |
| Night or shift premium | Not automatically | The payment must be tied to FLSA-required overtime, not merely the shift. |
| State daily-overtime premium | Fact-specific | It may not be required under FLSA section 7. |
| Premium paid to an FLSA-exempt worker | No, generally | The federal overtime requirement does not apply. |
| Qualified tips | No under section 225 | Qualified tips are excluded from the definition of qualified overtime compensation. |
Records to keep
For each tax year, keep enough information to show both why the payment qualified and how you calculated the premium. Useful records include:
- Forms W-2, 1099-NEC, or 1099-MISC;
- pay stubs for every relevant pay period;
- hours worked by workweek or applicable FLSA work period;
- the regular rate used by payroll;
- separate straight-time and overtime-premium amounts;
- records of nondiscretionary bonuses, commissions, or piece-rate pay;
- employer statements explaining overtime or compensatory-time calculations;
- FLSA classification records, such as a federal employee’s Standard Form 50; and
- your Schedule 1-A calculation, including any adjustment from the IRS reasonable method.
If your pay stub has only one “overtime” line, determine whether it represents the full 1.5× amount, only the premium, double-time pay, or a mixture of payments. The label alone is not enough.
Frequent mistakes to avoid
- Using the entire overtime paycheck. For ordinary time-and-a-half pay, the potential deduction is generally the one-third premium portion of the total, not the full amount.
- Calling the deduction a credit. A deduction’s value depends on your marginal federal tax rate.
- Assuming every hourly employee qualifies. FLSA coverage and nonexempt status still matter.
- Assuming every salaried worker is excluded. Salaried nonexempt workers may qualify.
- Treating a state-law premium as federal qualified overtime. The federal deduction is tied to FLSA section 7.
- Assuming weekend, holiday, night, or daily overtime is automatically eligible. The hours and legal basis for the premium must be examined.
- Claiming the full $25,000 for each spouse. The joint-return limit is combined.
- Calling $150,000 or $300,000 a hard cutoff. Those amounts begin the phaseout; they do not automatically eliminate the deduction.
- Expecting Social Security and Medicare tax to disappear. The deduction generally affects federal income tax only.
- Assuming payroll will stop federal withholding. Withholding and final tax liability are separate.
- Rejecting a 2025 claim because the W-2 has no special overtime box. Separate reporting was not required for 2025, and reasonable calculation methods may be available.
- Including pay in the year the hours were worked instead of the year received. A January paycheck for December work generally belongs to the later tax year.
- Assuming a 1099 proves eligibility. The form does not establish whether the payment was legally required under the FLSA.
A practical pre-filing checklist
- Identify whether the worker was an FLSA-covered employee.
- Confirm nonexempt status and the applicable workweek or special work period.
- Identify the hours that exceeded the federal overtime threshold.
- Determine the FLSA regular rate, including relevant bonuses or other compensation.
- Calculate only the FLSA-required premium above that rate.
- Confirm the compensation was received in the tax year being claimed.
- Match the amount to the W-2, 1099-NEC, or 1099-MISC reporting.
- Use the 2025 reasonable method if the 2025 form does not separately show qualified overtime.
- Check the valid employment-authorized SSN requirement.
- If married, confirm the return is filed jointly and combine both spouses’ amounts.
- Apply the $12,500 or $25,000 cap.
- Calculate the MAGI phaseout rather than treating the threshold as an automatic cutoff.
- Complete the correct tax-year Schedule 1-A and retain your supporting records.
- Check your state and local treatment separately.
IRS FAQs provide useful administrative guidance, but the IRS states that FAQs are general information and are not published in the Internal Revenue Bulletin. If guidance conflicts with the statute, the statute controls. For unusual classifications, complex regular-rate calculations, or large deductions, consult the current form instructions or a qualified tax professional.
Frequently Asked Questions
Is overtime completely tax-free under the new law?
No. The law provides a temporary federal income-tax deduction for qualified overtime compensation received in tax years 2025 through 2028. For ordinary time-and-a-half overtime, only the additional half-time premium generally qualifies. Social Security, Medicare, and potentially state and local taxes still apply.
The Tool Desk
Outbyte Driver Updater FREEScan for outdated or missing drivers - takes under a minuteDriver Scan →Outbyte PC Repair FREERepair Windows errors before they cause bigger problemsFix Now →Can I claim the deduction if my 2025 W-2 does not list qualified overtime separately?
Possibly. Separate reporting was not required for 2025. IRS Notice 2025-69 allows reasonable calculation methods supported by pay stubs, payroll records, the regular rate, qualifying hours, employer information, and similar documentation.
How much is a $1,000 overtime deduction worth?
It depends on your marginal federal income-tax rate and overall return. As an illustration, a $1,000 deduction is worth approximately $120 at a 12% marginal rate, $220 at 22%, or $240 at 24%. It is not a $1,000 tax credit or refund.
Can married spouses each claim $25,000?
No. Married taxpayers must generally file jointly, and the $25,000 maximum is a combined limit for both spouses.
The Bottom Line
The overtime tax break is real, but “tax-free overtime” is an oversimplification. For 2025 through 2028, eligible FLSA-covered, nonexempt workers may deduct the federally required overtime premium—usually the extra 0.5× portion of time-and-a-half pay—subject to the $12,500 or $25,000 cap and the MAGI phaseout. The deduction does not eliminate payroll taxes, automatically eliminate state tax, or guarantee that payroll withholding will stop.
Quick wins for a faster PC:
Scan for outdated or missing drivers - takes under a minuteDriver Scan →Clear out junk files and repair common Windows errorsFree Scan →Start with your FLSA status, calculate the premium rather than the full overtime paycheck, use the correct tax-year reporting rules, and keep the records supporting your calculation.
Quick Recap
Product prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on Amazon at the time of purchase will apply.




